THE GENERATIONAL RESET
Key Proposals
Restore the bank levy to reflect the value of the implicit state guarantee. Priced by independent modelling of what the guarantee would cost as a commercial insurance product.See how Budget 2026 relates to this
Make the Digital Services Tax a permanent instrument. Moving from a provisional 2% charge to a rate set by independent assessment of value extracted from UK user data.
Recycle carbon pricing revenue as a visible energy cost dividend. ETS and CBAM revenue paid per-capita to lower-income households, making carbon revenue recycling politically accountable.
Introduce a phased Land Value Tax. Starting with urban commercial and undeveloped land, where the value gap between current use and development potential is largest and least contested.
Advance unitary corporation taxation internationally. Engaging with the EU's BEFIT framework and positioning the UK as an advocate for apportionment-based taxation in G7 and OECD forums.
Replace council tax and business rates with a comprehensive Land Value Tax. Once the valuation infrastructure matures — simpler, broader-based, and more rationally tied to actual land value.
1. The Problem With a Single Instrument
The Economic Renewal pillar makes the case for moving the tax base from earnings toward inherited wealth. That argument holds. The income tax base is under strain, household wealth keeps growing, and the baby boomers' estates are the fiscal opportunity. Inheritance tax reform is the right centrepiece for a redesigned revenue system.
But a centrepiece is not the whole table.
Inheritance tax reform cannot carry the whole load, and since 14 October 2026 this pillar says so directly. It used to describe a £1–4 trillion gap to be bridged on the way to inheritance tax replacing income tax entirely. On corrected figures for wealth passing between generations (§8.1), even a 95% tax on every pound transferred would raise only about a fifth of what income tax and NI raise. Other taxes have to contribute permanently, not just during a transition. Several of them are worth having in any case, because they correct market failures, close avoidance routes, and tax things that should have been taxed all along.
There is also a resilience argument. A tax system that depends on one instrument, however well designed, is fragile. Demographic change, behavioural responses, capture of how it is implemented, and legal challenge can each erode one instrument's yield. A portfolio of instruments, each with its own justification, is harder to attack and harder to hollow out.
2. The Incidence Question: Who Actually Pays
Before looking at any specific instrument, one principle needs to be set out, because it runs through every argument about tax and is almost never addressed in public debate.
The legal incidence of a tax (who is required by law to pay it) is not the same as its economic incidence (who actually bears the cost).
Corporation tax is legally paid by businesses. But businesses can pass part of the cost to workers through lower wages, to customers through higher prices, and to suppliers through lower prices paid. Shareholders bear what is left. Economists dispute the exact split between these four groups, but not the principle that a tax on a business is not simply a tax on its owners.
Tariffs are paid by importers, who pass the cost to consumers through higher prices. A tariff on washing machines is paid at the border by the importing company and at the till by the household buying the machine.
VAT is charged on businesses at each stage of production. The cost is passed along the supply chain and ends up with the final consumer.
This matters for three reasons. First, a tax that seems to fall on a business or an industry may really fall on ordinary households, especially if the goods are essentials. Second, the distributional effect of a tax depends on who actually bears it, not who formally pays it. Third, incidence is the only fair basis for comparing instruments. Treating a tax on companies and a tax on individuals as different in kind, when in practice both may fall largely on consumers and workers, is rhetoric, not analysis.
With that established, here is the portfolio.
3. Land Value Tax: The Most Underused Instrument
3.1 The Principle
A Land Value Tax is an annual charge on the unimproved value of land: what the land itself is worth, apart from any buildings, infrastructure or improvements on it. It does not tax what you have built. It taxes ownership of land whose value was created by others.
The case for LVT has an unusual feature: it wins agreement across the political spectrum. Economists from Milton Friedman on the right to Joseph Stiglitz on the left have endorsed it. The IMF, the Resolution Foundation, the Institute for Fiscal Studies and successive tax reform commissions have all noted its advantages in principle. It is not a radical or untested idea. It is a well-understood one that has been blocked politically rather than rejected on the analysis.
The main reason for that consensus is that LVT is the only major tax with no significant economic cost in lost activity. Every other tax distorts behaviour: income tax discourages work, corporation tax discourages investment, VAT discourages consumption. LVT cannot reduce the supply of land, because the amount of land is fixed. You cannot make more of it when the tax is low or destroy it when the tax is high. And because land values are largely created by public decisions and public investment (a new transport link, a school, a planning permission), taxing them recovers value the public created and private owners have quietly pocketed, rather than taking something that was earned.
3.2 What It Would Tax and What It Would Not
LVT taxes the unimproved value of land. It does not tax buildings, improvements or productive activity on the land. A developer who builds homes adds to the value of what sits on the land, and that increase is not subject to LVT. A landowner who holds a plot near a planned infrastructure project and watches its value rise while doing nothing is exactly what LVT captures.
The key design distinction is between use value and speculative value. A farm is worth one amount as farmland. It may be worth far more if planning permission for housing were granted. That speculative premium, the gap between the two, comes entirely from planning decisions, not from the landowner. LVT charged on use value does not penalise farmers for owning land near cities. LVT charged on speculative value does.
The right design is to assess LVT on use value when the owner has made a legally enforceable commitment, registered on the title, that the land will not be developed. Land without such a restriction is assessed on its full value, including any speculative premium. The choice is simple: make the conservation or farming commitment legally binding and pay LVT on use value, or keep the option to develop and pay LVT on the full value that option represents.
3.3 Agricultural Land: Getting the Design Right
Farming margins in the UK are thin, and many farms run at a loss without subsidy. An LVT charge that could not be set against farm income would force sales and consolidation, the opposite of the intended effect on how land is looked after.
The right approach links LVT to the Environmental Land Management Scheme. ELMS pays farmers and land managers for delivering public goods: storing carbon, managing biodiversity, reducing flood risk and creating habitat. Under the linked design, ELMS income offsets LVT liability for land in real agricultural or environmental use. A farm actively delivering ELMS public goods earns income that largely covers any LVT charge. Land held at minimal intensity, without qualifying for ELMS payments, pays LVT with no offset. The incentive is right: use your land productively, or pay for holding it idle.
The steel man is serious and deserves a serious answer. Mass land valuation is not simple, but it has been done. The Valuation Office Agency already keeps property valuations for council tax and business rates.1 They are imperfect (council tax is still based on 1991 values), but the infrastructure exists. Moving to LVT needs sustained investment in valuation and a realistic timeline measured in years, not months. Done properly, the administrative cost is manageable; done hastily, it is a disaster. Starting with the simplest cases (urban commercial land and large undeveloped plots) and extending gradually is more credible than a single national launch.
LVT is the only major tax with no significant economic cost in lost activity, because the supply of land is fixed and cannot respond to the tax rate, unlike income tax, corporation tax or VAT, each of which distorts what it taxes. UK land, excluding improvements, is worth in the region of £5 trillion; a 1% rate on assessable land value could in principle raise £30–50bn a year at the outset, an order-of-magnitude estimate rather than a forecast. The Valuation Office Agency already runs mass property valuation for council tax and business rates.1
Because LVT captures value created by public decisions and public investment (a new transport link, a school, a planning permission) rather than value the landowner produced, taxing it does not discourage the productive activity every other major tax in the portfolio has to work around. This connecting argument is this project's own; no single source states it. Whether LVT is sound in principle and whether it can be delivered are different questions. The cross-spectrum consensus among economists settles the first but not the second, which is exactly the point the Steel Man above presses.
The causation above fits responses short of a full national LVT, and the Steel Man names the evidence for them. One is to keep council tax and business rates broadly as they are, accepting their regressive and distorting effects as the price of avoiding a difficult national valuation. Another is a partial or split-rate version that taxes land at a higher rate than buildings without fully moving to unimproved-value assessment; the Australian, Danish and Estonian examples the Steel Man cites show the full model has never been implemented at scale. The third, which this pillar proposes, is a full LVT phased in deliberately, starting with the least contested cases.
Choosing a full, phased national LVT over a partial split-rate model or the regressive status quo rests on a value judgement this pillar makes openly: ending council tax's regressive design and capturing publicly created land value at scale is worth several years of administrative investment and transition risk, rather than a smaller, safer reform that leaves most of the distortion in place. A reader who gives more weight to the Steel Man's operational risks (litigation, valuation disputes, and the gap between elegant theory and the partial versions that exist abroad) than to the efficiency case is not wrong on the evidence. They are weighing the same facts against a different tolerance for administrative risk.
Replace council tax and business rates with a Land Value Tax of about 1% on assessable land value, excluding farmland qualifying for ELMS and certified conservation land, phased in over five to ten years starting with urban commercial land and large undeveloped plots, where the gap between use value and speculative value is largest and least contested. The falsification test below sets out what would show the phased approach is not containing the administrative risk the Steel Man warns about.
3.4 Conservation Land and the Governance Test
Land held for real conservation purposes, whether by a charity, a land trust or a privately funded conservation body, should pay zero or near-zero LVT, because the public benefit it delivers is worth more than the tax forgone.
The test for that exemption must be strict. It has two parts. First, the land must be held under independent charitable governance: no individual or group of connected persons may hold effective control, with "connected persons" defined in line with the Companies Act's Persons with Significant Control rules. A charity run by an independent board, with no controlling individual or family interest, passes. A vehicle designed to shelter personal wealth behind a charitable front does not. Second, the land must be actively delivering its stated conservation purpose, shown through annual public reporting reviewed by the Charity Commission.
Together these two requirements close the avoidance route without penalising real conservation. An owner who places land under the control of an independent conservation body has made a real charitable gift, and the LVT exemption is the right reward. An owner who wants both the exemption and personal control of the land cannot have both. The design makes that choice explicit instead of leaving it implicit and open to gaming.
3.5 What LVT Would Raise and What It Would Replace
UK land, excluding improvements, is estimated to be worth in the region of £5 trillion, most of it urban and residential. A 1% LVT on assessable land value, excluding productive farmland and certified conservation land, could in principle raise £30–50 billion a year at the outset, rising as the valuation system matures. That figure depends heavily on the design of exemptions and the valuation method, so treat it as an order of magnitude, not a forecast.
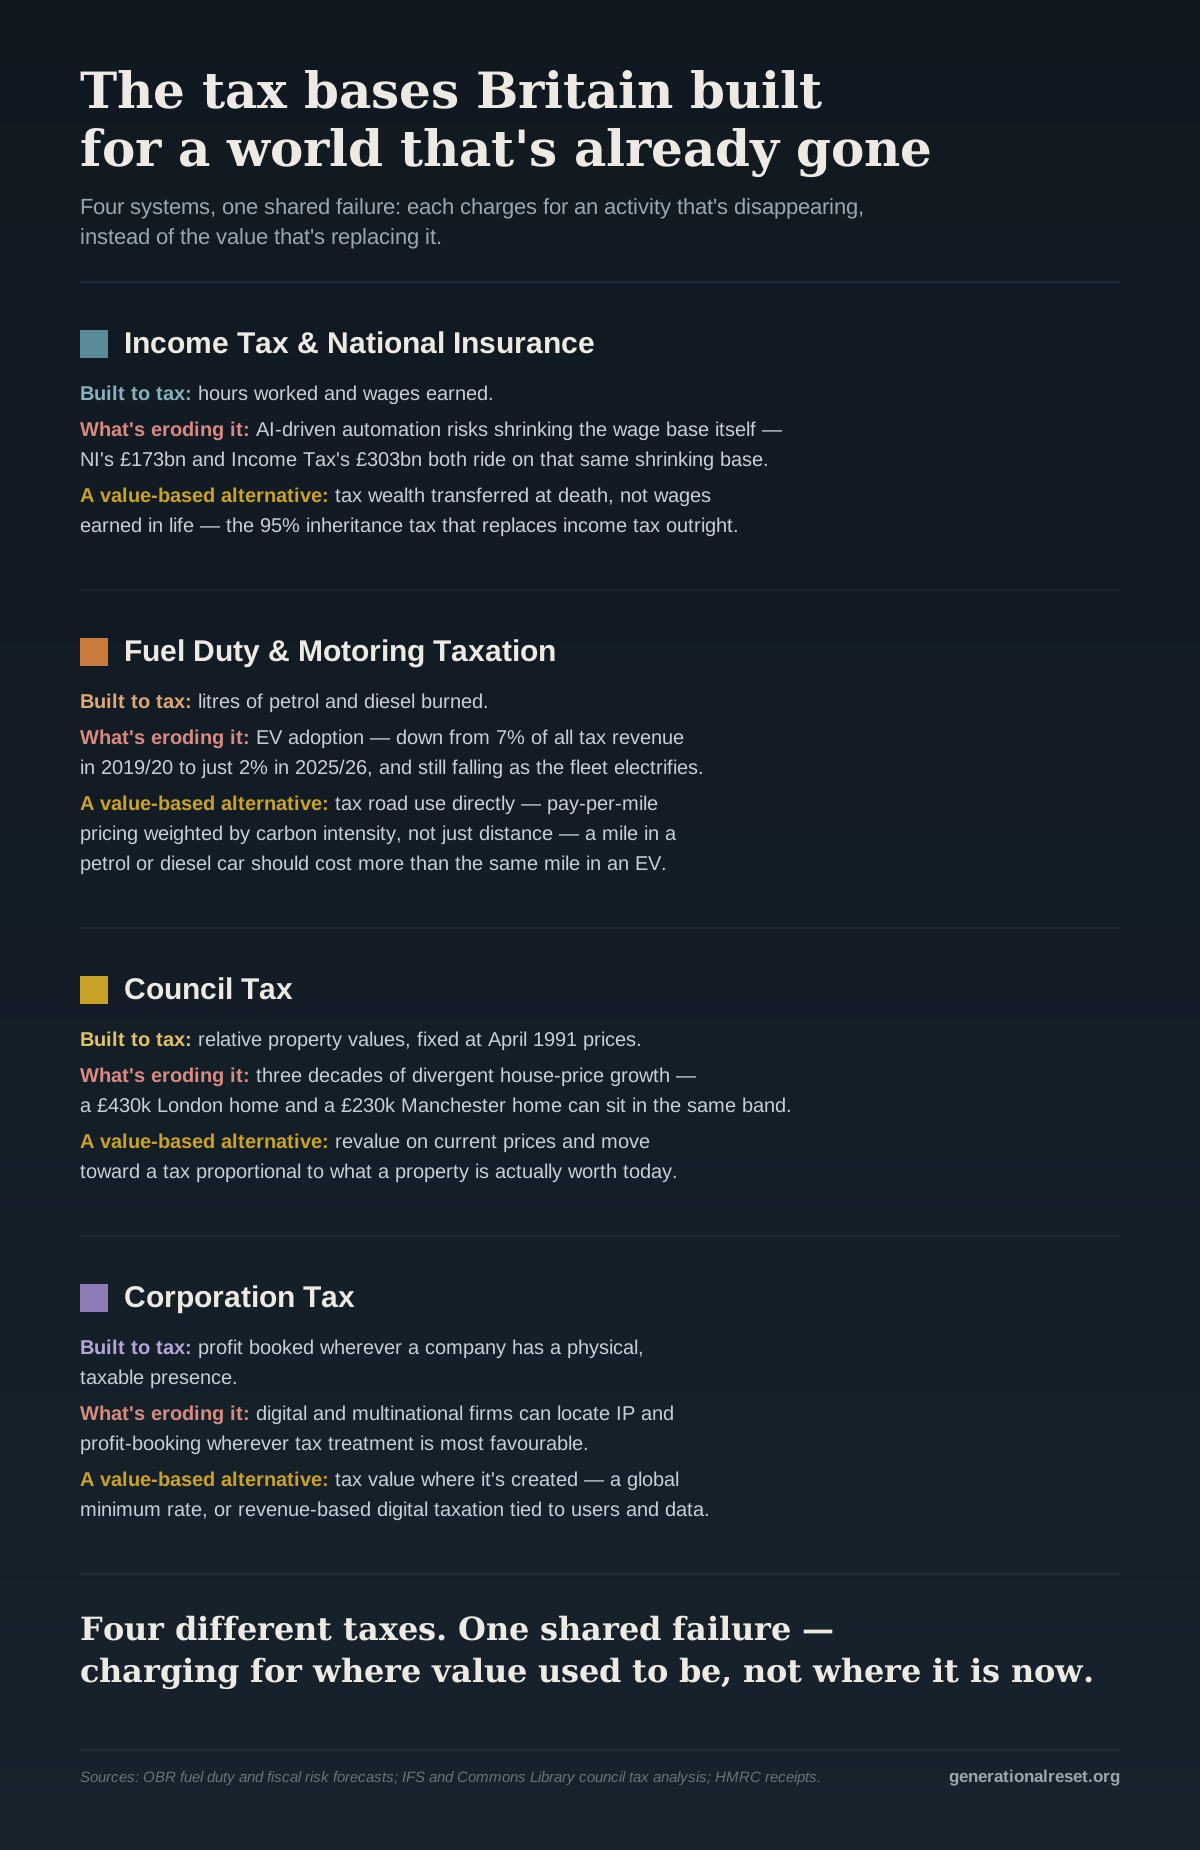
The more important question is what LVT replaces. Council tax is one of the most regressive taxes in the UK: based on 1991 property values, it charges owners of modest homes in low-value areas a higher effective rate than owners of multi-million-pound properties. Business rates distort the commercial property market in ways that hurt high streets compared with out-of-town and online retail. Both could be replaced by a well-designed LVT, in a revenue-neutral reform that taxes land more sensibly and removes two taxes whose distorting effects are well established.
4. Corporation Tax: Fixing the Design, Not Just Raising the Rate
4.1 The Current Position
UK corporation tax raised £93bn in 2023–24 at a headline rate of 25%.2 That rate is among the higher ones in the OECD for mid-sized economies. The effective rate paid by the largest multinationals, especially in technology and finance, is much lower, through mechanisms the Tax Avoidance pillar sets out in detail: transfer pricing, intellectual property held in low-tax countries, full deductibility of capital spending on AI, and the OECD's still-incomplete reforms.
HMRC's corporation tax gap was £21.0bn in 2024/253: the difference between what is owed under current law and what is collected. Small businesses account for £17.3bn of it. The figure covers evasion and error only, not legal avoidance, which is larger and built into how multinationals are organised. See the Tax Avoidance pillar for the full breakdown, including HMRC's unusually high return on its large-business compliance work (£95 recovered for every £1 spent).
4.2 The OECD Framework: What It Does and Doesn't Solve
The OECD's two-pillar agreement of 2021 is the most significant multilateral corporation tax reform in decades. The UK has implemented Pillar Two, a 15% global minimum tax on large multinationals' profits wherever they are booked.4 Pillar One, which would give countries the right to tax some profit where a company's customers are, not just where it books its profits, has stalled.
Pillar Two matters but has limits. A 15% floor is a floor, not a target, and the UK's headline rate is 25%. When a large group books profit in a country that taxes it below 15%, Pillar Two lets other countries charge a top-up, and many low-tax countries, Ireland included, now levy a 15% minimum on large groups themselves to keep that revenue. But a side agreement negotiated by the US exempts US-headquartered groups from the main top-up rules. HMRC estimates the carve-out cuts the UK's expected Pillar Two revenue from about £2.2bn a year to about £1.6bn5: useful, but small next to the scale of the underlying problem.
4.3 Unitary Taxation: The Right Fix
The underlying problem with corporation tax is how it is designed. It treats each subsidiary of a multinational as a separate business, which lets the group steer profits to whichever subsidiary sits in the most favourable country. Transfer pricing rules are supposed to stop this, but they are disputed, expensive to enforce, and routinely gamed through licensing of intellectual property.
Unitary taxation is the right alternative. Instead of taxing each subsidiary on the profits it reports locally, a country taxes the multinational as one business on its global profits and takes a share based on where its economic activity actually happens, measured by employment, sales and assets. A multinational cannot move the UK's share to Ireland by routing sales through a Dublin subsidiary, because the share depends on where its customers, workers and operations are, not where the profit is reported.
Unitary taxation needs some international coordination, but not universal agreement. A coalition of major economies using a common formula would cover most global corporate activity and make the system much harder to escape. The EU has proposed a version of it (BEFIT, Business in Europe: Framework for Income Taxation).6 It is politically difficult, not technically impossible.
4.4 The Digital and Data Economy
The UK Digital Services Tax charges large technology platforms 2% of their UK revenue from search, social media and online marketplaces. It was meant to be temporary, pending the Pillar One agreement that never arrived. Whether 2% is the right rate, and whether the tax captures the full value extracted from UK users, is an open question this project flags for further work.
The deeper question, which links to the AI pillar, is whether there is a principled case for taxing data extraction as an activity in its own right. The large AI models reshaping the UK economy were trained on data generated by UK citizens, businesses and public institutions. That data had value, and the companies that took and commercialised it paid nothing for it. This is the logic of carbon pricing, that polluters should pay for the damage they impose, applied to data: those who extract value from a shared resource should pay for it.
A data levy, charged on companies above a certain size that extract and commercialise data generated by UK users, is sound in principle. The practical problems are significant: how to value data extraction, how to avoid double-counting with the Digital Services Tax, and how to avoid catching legitimate uses of data alongside extractive ones. The Gaps Register should record this as an open question, not a settled answer.
5. Carbon Pricing and the Border Adjustment
5.1 Carbon Pricing as Revenue and Correction
The UK Emissions Trading Scheme, the domestic successor to the EU ETS after Brexit, puts a price on carbon emissions from the sectors it covers (power generation, heavy industry, aviation). Businesses must hold a permit for each tonne of CO₂ they emit. The permits can be traded, and the government auctions some of them each year, raising revenue.
Carbon pricing is the clearest example of a tax that both raises revenue and corrects a market failure. Carbon-intensive activity imposes costs, through climate damage, that market prices do not reflect. Making it pay for its carbon through the ETS builds that cost into prices, reduces carbon-intensive activity, and raises revenue in the process. The UK ETS currently raises around £2–3 billion a year, and that is expected to grow as the scheme expands and the carbon price rises.7
On incidence: carbon pricing costs are passed to consumers through higher energy and product prices. The direct effect is regressive, because lower-income households spend more of their income on energy. The standard answer is to recycle the revenue, paying it back as a per-person dividend or using it to cut other regressive taxes. The UK has put ETS revenue into general spending rather than recycling it explicitly. That choice should be revisited.
5.2 The Carbon Border Adjustment Mechanism
The EU has introduced a Carbon Border Adjustment Mechanism, in effect a carbon charge on imports from countries without equivalent carbon pricing. The UK is introducing its own from 2027. It is the defensible version of the "targeted tariff on certain industries" that trade policy debates sometimes propose.
The CBAM charges for a cost the exporter has avoided; it is not protectionism. If a UK steel producer pays the UK carbon price on its emissions, and a competitor in a country with no carbon price makes the same steel more cheaply by emitting freely, the UK producer is at a disadvantage. That is not because it is less efficient, but because its competitor is pushing costs onto the global climate. The CBAM charges the competitor's product at the border for the carbon it contains.
CBAM revenue goes to the government, and trading partners have an incentive to introduce their own carbon pricing, which removes their exposure to the charge. So the mechanism raises revenue and also pushes other countries toward climate action. It is one of the few cases in trade policy where a tariff-like charge serves a public purpose beyond raising money.
6. Sector-Specific Levies: When They Are and Are Not Justified
6.1 The Principle
A levy on a particular sector is justified when one of three conditions holds.
The sector creates costs it does not pay for. Examples are the carbon from fossil fuel production, the systemic risk in financial services, and the environmental damage from some extractive industries. These costs are real, they fall on others, and the sector's prices do not reflect them. A levy that charges for them corrects a market failure, and the revenue is a by-product of doing the right thing.
The sector benefits from an implicit public subsidy. Financial services is the clearest case. Large banks operate with an implicit government guarantee: the expectation, proven in 2008, that the state will not let systemically important banks fail. That guarantee is a subsidy, estimated at tens of billions a year, for which the sector pays nothing directly. A levy that prices the guarantee charges for a service the public provides; it is not an extra tax piled on the sector.
The sector makes windfall gains from events outside its control. When energy companies make extraordinary profits from a geopolitical supply crisis, not from their own investment or efficiency, part of those unearned gains can be taken without discouraging the investment that normal returns are meant to reward. The test is whether the gain was really unearned and really temporary. A permanent levy on a sector making ordinary profits fails the test and discourages investment. A time-limited charge on extraordinary gains that took no extra effort passes it.
6.2 The Financial Transactions Tax
The UK already has a financial transactions tax on share purchases: Stamp Duty Reserve Tax at 0.5%, which raises about £3 billion a year. That shows a broader financial transactions tax can work at modest rates.
Extending it to derivatives and bonds at very low rates (0.01–0.1% depending on the instrument) would greatly widen the base. The difficulty is that derivatives markets are highly sensitive to transaction costs, and a badly designed tax can drive trading to other countries. The evidence from European experiments is mixed: France and Italy saw equity derivatives trading move elsewhere. A UK tax coordinated with other major financial centres is more workable than a unilateral one, and a unilateral one limited to instruments that cannot easily be traded elsewhere is more workable than a comprehensive one.
So the realistic position is this: extending the existing stamp duty principle to more financial instruments is worth doing at modest rates with careful design. A comprehensive tax at rates high enough to transform the economics of the financial sector is a different and riskier proposal.
6.3 The Bank Levy and the Implicit Guarantee
The UK bank levy, introduced in 2011, charges a percentage of a bank's balance sheet above a threshold. It raised £1.3 billion in 2024-25.8 It was introduced explicitly because large banks benefit from an implicit state guarantee that their depositors and creditors will be protected if they fail.
The economic case for it remains strong. The 2008 financial crisis showed the guarantee is real: the UK government committed over £1 trillion in guarantees, loans and capital to stabilise the financial system. The guarantee still exists, and it lowers large banks' borrowing costs, because lenders assume the state will step in, so they lend more cheaply than the banks' risks alone would justify. The difference between what the banks pay and what they would pay without the guarantee is a subsidy, and the bank levy is the charge for it.
Whether the current rate reflects the guarantee's full value is an open question. The guarantee is worth more in a financial system that is larger, more leveraged and more interconnected, and the levy has been cut several times since it was introduced. Restoring it to a level that reflects the guarantee's current value, rather than a level its payers lobbied down, is the right correction.
7. Trade Tariffs: A Realistic Assessment
7.1 Tariffs as Revenue: What Trump's Policy Shows
The United States under Trump's 2025 tariff programme has shown, at scale, what happens when tariffs are used mainly to raise revenue and make political points rather than as a targeted trade tool. The evidence on who pays is clear: tariff costs are passed to consumers in higher prices. The Federal Reserve Bank of New York and several peer-reviewed studies of the 2018–2019 US tariffs9 found that the full cost was passed to US consumers, with little sign that foreign exporters bore any of it.
This is the incidence point again. The importer formally pays the tariff but passes it on in higher prices, so it falls on the final consumer. And because tariffed goods (electronics, clothing, household goods, food) take up a larger share of lower-income households' budgets, the effect is regressive.
Tariffs also invite retaliation. A tariff on one sector brings a matching tariff on another from trading partners, and the revenue from one is offset by the cost to exporters of the other. The net effect on the public finances is unclear; the net effect on the economy is usually negative.
7.2 Where Targeted Tariffs Are Legitimate
Four situations justify tariff-like charges, and none is mainly about raising revenue.
Anti-dumping. A foreign producer selling below cost to grab market share destroys domestic industry and creates long-term strategic weakness. WTO rules allow anti-dumping tariffs once dumping is proven. These are legitimate, time-limited and targeted.
Carbon border adjustment. As described in Section 5, this charges for a cost that was avoided; it is not protectionism. It raises revenue as a result of correcting a market failure, not as its main purpose.
National security. Chip supply chains, medicines, critical minerals and strategically important manufacturing. The economic cost of a national security tariff is accepted as insurance against supply disruption. This is a legitimate use of trade policy with a clear, limited scope.
Infant industry protection. Shielding a new domestic industry while it reaches competitive scale makes sense in theory but has a poor record in practice, because once interests form around the protection it is politically almost impossible to remove. The argument holds together in theory and has almost never worked. It deserves strong scepticism.
7.3 What the UK Cannot Afford to Get Wrong
UK imports of goods and services are worth about a third of GDP, making it one of the most trade-exposed major economies in the world. Tariffs on imports, especially broad ones, translate directly into higher prices in an economy with inflation worries, heavy reliance on imported food and manufactured goods, and a current account deficit that depends on international capital flows.
Brexit has already reduced the UK's tariff-free access to its largest trading partner. Further unilateral tariff increases, outside the narrow legitimate uses above, would worsen the UK's economic weaknesses rather than address them. Tariffs are a limited and largely unsuitable tool for funding the services the Generational Reset argues are needed.
8. The Portfolio: How the Instruments Fit Together
No single instrument in this document is enough on its own. Each has strengths and weaknesses, different timing, different incidence and different politics. Together they make a coherent tax system for an economy in which earnings are under pressure and asset wealth (in land, companies and financial instruments) is growing.
8.1 The Numbers Ledger
The figures are set out as two separate ledgers. Table A is the inheritance tax track: inheritance tax and the two financing mechanisms Economic Renewal §4.1 names alongside it, which together pay for the income tax cut. Income tax and NI are shown for scale, so it is clear how much of them inheritance tax can fund. Table B is the wider revenue portfolio (LVT, corporation tax, carbon pricing, FTT, bank levy, DST), which funds other public spending. Economic Renewal §4.1 does not count any of it toward the income tax cut, so adding it to Table A's total would overstate what inheritance tax achieves, the instrument-stacking error the Gaps Register and Economic Renewal both warn against. Every cell marked "not quantified" is left as a gap rather than filled with an invented number, so the totals are floors, not false precision.
Table A: The Inheritance Tax Track
| Today | Stage 1 (Years 1–7) | Stage 2 / Full (Years 15–25+) | |
|---|---|---|---|
| Income tax + NI (for scale) | £475bn | £475bn: no income tax cut yet, per Economic Renewal §4.5 | Cut by as much as inheritance tax revenue pays for, lowest rates first |
| Inheritance tax revenue | £8.2–8.7bn | £10–15bn | Ceiling ~£95–110bn on today's transfers (95% of every pound, no threshold, exemptions, avoidance or spend-down); perhaps £190–340bn by the 2040s in cash terms |
| Transition bonds + Sovereign Wealth Mechanism | £0 | Not quantified: §4.1 now gives the bonds a narrower job, bringing forward cuts that later inheritance tax revenue pays for | Not quantified |
| Total inheritance tax track | £8.2–8.7bn | £10–15bn + unstated | Ceiling ~£95–110bn at today's values + unstated |
| Share of income tax + NI this could fund | ~2% | ~2–3% | ~20–23% at today's values, even at the ceiling |
The bottom-right cell is the one to dwell on. Corrected 14 October 2026: this ledger previously used an annual wealth transfer of £200–400bn now, rising to £350–450bn at the 2035–2045 peak, and concluded that inheritance tax could match the £475bn income tax base at the top of that range. No source supports those figures. The best estimates put transfers between generations at roughly £100–115bn a year now. Cebr's projection for Kings Court Trust puts total transfers at death and in lifetime gifts at £115bn in 2027, and the Resolution Foundation, using HMRC data, put estates passing on death at £87bn in 2014–15 and expects inheritances to double over the next two decades.10 A 95% tax on every pound of that raises roughly £95–110bn, about a fifth of £475bn. Transfers may be two to three times larger by the 2040s in cash terms, but income tax and NI grow in cash terms too, so the share barely moves. Matching income tax is out of reach, and Economic Renewal's goal has changed accordingly: from abolishing income tax to a permanent income tax cut sized to what inheritance tax actually raises. Table B could add more, but neither Economic Renewal nor this pillar currently earmarks it for that rather than for the spending it already funds.
Table B: The Wider Revenue Portfolio (parallel, not counted in Table A)
| Instrument | Today | Near Term | Long Term |
|---|---|---|---|
| Land Value Tax | £0 (doesn't exist) | £0: 5–10 years to build the valuation system, per §9.2 | £30–50bn, "an order of magnitude, not a forecast" |
| Corporation tax (baseline + Pillar Two) | £93bn | ~£95bn (+~£1.6bn Pillar Two, already in force) | ~£95bn + unquantified gain from unitary reform |
| Carbon pricing (ETS + CBAM) | £2–3bn | £2–3bn+, growing; no target set | Growing, not quantified |
| Financial Transactions Tax | £3bn (existing SDRT only) | £3bn: extension to derivatives and bonds not quantified | Not quantified |
| Bank levy | £1.3bn | £1.3bn: restoration target not stated | Not quantified |
| Digital Services Tax | £0.8bn (2024–25 actual) | £0.8bn+: extension not quantified (OBR projects £1.4bn by 2030–31 under the current design) | Not quantified |
| Windfall levies | Occasional; no steady baseline by design | Excluded from totals | Excluded from totals |
| Total (floor, excl. windfall) | ~£100bn | ~£102bn | £125bn+ and rising, but most cells still open |
How the Table A Stage 1 figure was built. HMRC's Inheritance Tax statistics (Table 12.1a, 2023–24, the latest full year) show 3,520 taxpaying estates valued at £2 million or more, paying £3.79bn in tax between them at effective rates of 18–25%. Table 12.3a shows the same £2m+ band holding £21.1bn in total net capital across all 4,620 estates notified, taxed and untaxed; the roughly 1,100 untaxed estates are mainly explained by the spouse exemption. Working back from the taxed estates' effective rates gives a taxable base of about £17.4bn for the 3,520 estates already paying tax. Applying Stage 1's proposed 60–70% rate to that base gives £10.4–12.2bn a year if the spouse exemption stays during Stage 1, or £12.7–14.8bn a year on the full £21.1bn if it is closed too, hence the £10–15bn range. This is one year's stock of estates, not a forecast. It will grow with wealth, but not tenfold within Stage 1's 5–7 years.
8.2 The Assumptions Register
The two tables rest on assumptions that are not always stated next to the numbers. Listing them here is what turns a set of estimates into something a critical reader can test.
- Whether Stage 1 closes the spouse exemption. Economic Renewal §4.5 describes Stage 1 as "60–70% on estates above £2 million" with real measures to close avoidance routes, but does not say whether the spouse exemption survives Stage 1. This is not a rounding error: it is the difference between £10–12bn and £13–15bn a year, and a much larger share of the eventual base at the full 95% rate. Economic Renewal should state it explicitly.
- Transition bonds and the Sovereign Wealth Mechanism have no revenue target. Both are named in Economic Renewal §4.1, but neither has a £ figure attached anywhere, so Table A's total is a floor, not a complete account.
- Wealth keeps growing through 2035–2045 without a correction. The full-rate ceiling (~£95–110bn on today's transfers, rising by the 2040s) assumes household wealth keeps growing at its recent pace, undisturbed by a housing correction (including one LVT itself might cause) or by the reform's own effect on asset prices and how people hold wealth.
- The valuation system and constitutional protections hold. Getting near the full-rate ceiling assumes the reforms in Economic Renewal §4.3–4.4 stop the effective rate drifting down the way today's 40% rate has, to 12–25% depending on estate size, per the calculation above. If they don't fully hold, revenue at a legal rate of 95% could sit well below the headline figure, nearer the bottom of the range.
- Superseded 14 October 2026: the £1–4tn transition gap. With no transition to replacing income tax entirely, this range no longer applies. The earlier note, kept for the record, said the range was a plausible span rather than a costed scenario: no year-by-year model had been published, and the fourfold range reflected uncertainty about pacing between Stage 1 and Stage 2.
- The wider portfolio (Table B) is not earmarked for the income tax cut. Nothing in Economic Renewal or this pillar says LVT, corporation tax, carbon, FTT, bank levy or DST revenue is available to fund a bigger income tax cut; it funds other priorities. If that changes, more of income tax could be cut. As things stand, treating the two tables as one total would be exactly the instrument-stacking error this pillar warns against in §1.
- Almost all of Table A's revenue arrives late. £10–15bn a year in Stage 1, against a full-rate ceiling of ~£95–110bn a year at today's values, means the first 5–7 years raise a small fraction of the eventual amount. That is why Economic Renewal §4.5 makes no income tax cut in Stage 1: the cuts follow the revenue rather than running ahead of it, except where transition bonds bring forward cuts that proven later revenue will pay for.
9. The Timing Question: Sequencing the Portfolio
9.1 Instruments Available Immediately
An extended financial transactions tax, a restored bank levy and a strengthened Digital Services Tax can all raise revenue within one parliament. None needs the years of infrastructure that LVT does, or the 15-year path of the inheritance tax reform. Together they are a meaningful down payment while the longer-term instruments are built.
Carbon pricing revenue is already flowing and will grow as the UK ETS matures and the CBAM starts. It is the easiest revenue to expand: tightening the ETS cap raises the carbon price and the revenue, and speeds up decarbonisation. Recycling the revenue, using ETS and CBAM income to offset higher energy prices for lower-income households, should be built in from the start.
9.2 The Medium-Term Build
LVT needs investment in valuation before it can yield at scale. The Valuation Office Agency would need to expand significantly, the law for development restrictions registered on title would need to be created, and the link with ELMS would need to be working. A realistic timeline for LVT to contribute meaningfully is five to ten years from a decision to go ahead.
Corporation tax reform, specifically the move to unitary taxation, needs an international coalition willing to adopt a common formula. That is a diplomatic project as much as a legislative one. The EU's BEFIT framework is the most likely vehicle, and UK engagement with it, as a non-member, through bilateral agreements or matching legislation, is the practical route.
9.3 The Long-Term Architecture
The inheritance tax reform, the centrepiece of the whole architecture, is a 15–25 year project. Under the two-stage path in the Economic Renewal pillar, the full 95% rate and the income tax cut it pays for are the end of a journey that begins with Stage 1. The portfolio in this document is not an alternative to the inheritance tax reform. Since inheritance tax receipts will never be large enough to replace income tax (§8.1, corrected 14 October 2026), the rest of the portfolio is a permanent part of the system, not a bridge.
Once fully in place, the system would tax:
- Wealth when it passes between generations (inheritance tax)
- The value of land, the most basic form of unearned wealth (LVT)
- Carbon and other harms, so that what damages shared resources pays for the damage
- Financial activity at modest rates, paying for the public backstop the financial sector relies on
- Company profits where the economic activity happens, not where the accountants book it
What would be taxed less: earnings, productive investment and real enterprise. Income tax would be cut, not abolished. The architecture is coherent, the direction is clear, and the instruments reinforce rather than compete with each other. More of the cost of public services would fall on wealth, land, environmental harm and financial activity, and less on workers whose earnings are already under pressure from the forces this project describes.
10. The Steel Man: The Case for Simplicity
The steel man is partly right. Complexity is a real problem in tax design. Every boundary creates an opportunity to game it, and every exemption becomes a target for lobbying. Broad bases and low rates is a principle with real force.
But the instruments proposed here are not complex for the sake of it. Each tackles a specific market failure or closes a specific avoidance route the current system has failed to deal with. LVT is simpler than the council tax and business rates it would replace: a single annual charge on a registered asset, with fewer reliefs and fewer valuation disputes than the systems it supersedes. Carbon pricing through an ETS is a market mechanism that needs little administration once the cap and auctions are set up. A modest extension of the existing stamp duty adds a little complexity at the margin, not throughout the system.
The aim is not more instruments but the right ones, designed to tax things that should have been taxed all along and to close the routes that let them escape. That is a different argument from complexity for its own sake, and should be judged as such.
Cross-Pillar Dependencies
| This document | Relates to | Nature of dependency |
|---|---|---|
| S3_05 Revenue Architecture | S3_04 Economic Renewal | The inheritance tax reform is the centrepiece of the system described here, and this document sets out the portfolio around it. Neither is complete without the other. |
| S3_05 Revenue Architecture | S3_02 Tax Avoidance | The Tax Avoidance pillar shows how every margin of the current system is already being exploited. The instruments proposed here address specific failures that document identifies. |
| S3_05 Revenue Architecture | S1_04 Housing | Land Value Tax tackles the planning and land-banking failures the Housing pillar diagnoses. LVT on undeveloped land near development zones changes the incentive to build. |
| S3_05 Revenue Architecture | S4_01 Energy | Carbon pricing and the CBAM link to the Energy pillar's analysis of transition costs and competition. Carbon pricing revenue should be considered alongside the Energy pillar's investment proposals. |
| S3_05 Revenue Architecture | S4_03 Artificial Intelligence | The questions about taxing data extraction and digital services link directly to the AI pillar's analysis of who captures AI's economic gains. Revenue design and AI governance are the same problem seen from different angles. |
| S3_05 Revenue Architecture | S1_07 Public Debt | How to time the income tax cut against inheritance tax revenue, including whether transition bonds bring cuts forward, is the same question the Public Debt pillar addresses from the side of managing the public finances. |
| S3_05 Revenue Architecture | S3_03 Economy | The productive economy the Economy pillar argues for (more investment, a better regional spread, less dominance by finance) is both a goal of the revenue system proposed here and a precondition for it. |
| S3_05 Revenue Architecture | S5_01 Gaps Register | Several instruments here (data extraction taxes, LVT valuation methods, unitary corporation tax) are open questions rather than settled designs and should be registered as open gaps. |
12. Proposals for Change
These proposals are ordered by when they can be implemented and what they depend on.
Immediate (Years 1–3)
-
P1 Restore the bank levy to a rate that reflects the current value of the implicit state guarantee, using independent modelling, which doesn't yet exist and would need to be commissioned, of what the guarantee would cost if sold as commercial insurance.11
-
Extend Stamp Duty Reserve Tax to exchange-traded derivatives at 0.01%, in line with the existing principle and set low enough not to drive trading offshore. Review annually.
-
P2 Turn the Digital Services Tax from a temporary 2% revenue charge into a permanent instrument, at a rate based on an independent assessment of the value extracted from UK user data, pending the outcome of the stalled Pillar One negotiations.
-
P3 Use ETS and CBAM revenue explicitly for a per-person energy cost dividend to lower-income households, making the recycling of carbon revenue visible and politically accountable.
Medium Term (Years 3–10)
-
P4 Invest in the Valuation Office Agency to build the land valuation system LVT needs, starting with urban commercial land and large undeveloped plots, where the gap between use value and development value is largest and least contested.
-
P4 Introduce a Land Value Tax in phases, urban commercial and undeveloped land first, with a legally enforceable development restriction as the condition for reduced farmland and conservation rates.
-
Link LVT to the Environmental Land Management Scheme, so that ELMS payments offset LVT liability for land in real agricultural or environmental use.
-
Legislate the connected-persons governance test for charitable landholdings: no individual or connected group may hold effective control as a condition of the LVT charitable exemption, using the Companies Act's PSC definitions.
-
P5 Engage actively with the EU's BEFIT framework for unitary corporation taxation, seeking bilateral alignment or matching UK legislation that applies the same apportionment principle.
Long Term (Years 10+)
-
P6 Once the LVT system has matured, replace council tax and business rates with a comprehensive LVT: simpler, broader-based and more closely tied to actual land value than either tax it replaces.
-
P5 Advance unitary taxation through international coalition-building, with the UK as its leading advocate in G7 and OECD forums.
-
As inheritance tax receipts grow and income tax is cut, rebalance the portfolio: less weight on instruments that fall mainly on ordinary consumers, more on those that fall on wealth, land and unearned returns.
Document status: Living. The sections on data extraction tax, LVT valuation methods and unitary corporation tax contain open questions registered in the Gaps Register pending further analysis. Version 1.0, June 2026.
The Generational Reset | S3_05: The Revenue Architecture | For public discussion. Not affiliated with any political party. | generationalreset.org