THE GENERATIONAL RESET
This document sits in Section Four, The Context, because demographics is less a spending question or a question of political structure than the slow-moving physical reality within which every other policy question has to be answered. The age structure of the population decides who pays taxes and who draws on public services. The fertility rate decides whether there will be enough future contributors to meet the commitments made today. Where people live shapes housing demand, infrastructure needs and political voice. None of this comes from a single policy choice, but all of it can be shaped, or ignored, by policy. The Generational Reset argues it cannot be ignored any longer.
Executive Summary
The UK has an ageing population, a fertility rate below replacement level, a lopsided geographic spread of people, and a widening gap between the wealth older generations hold and the prospects open to younger ones. None of this is new, and all of it gets too little weight in public debate.
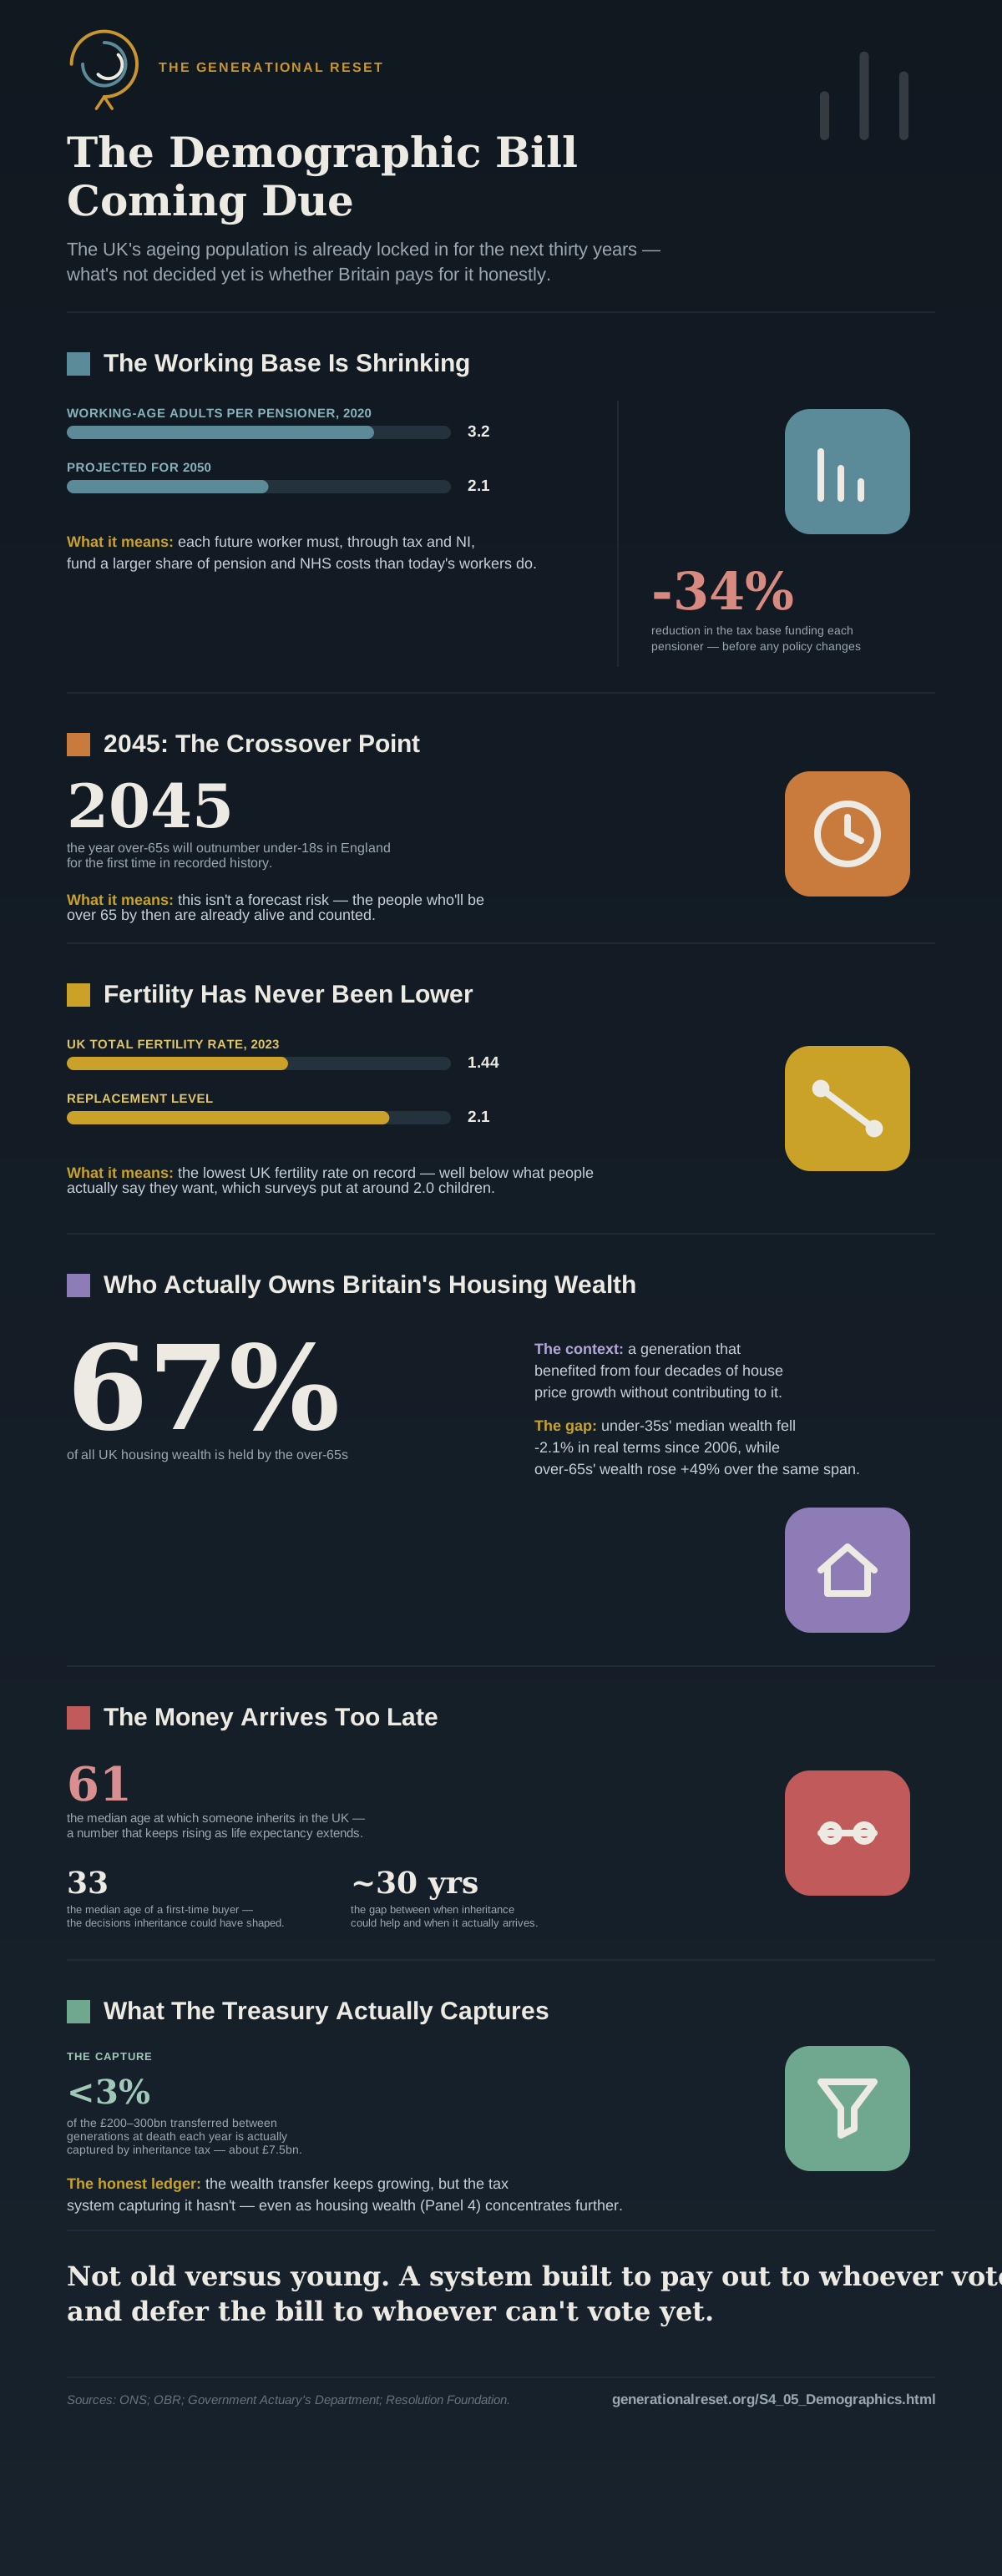
The fertility rate in England and Wales was 1.41 in 2024, the lowest since records began in 1938 and well below the replacement level of 2.1.1 The population is ageing: the ONS projects the number of people of pension age in the UK to rise from 12.4 million in mid-2024 to 15.3 million by mid-2049, while the working-age population grows by about 5%. That takes the number of people of pension age for every 1,000 of working age from 280 to 329, even with the State Pension age rising to 67.2 The state pension costs £146.5 billion a year. NHS and social care costs are projected to rise from 9.0% of GDP today to over 15% by the 2070s, driven almost entirely by an older population.
These numbers are not a crisis in themselves. They are long-term conditions that call for a frank policy response, and none is being made. Instead, the political system makes short-term transfers to the group with the most electoral power, older voters who own assets, and pushes the long-term consequences onto younger generations with less political voice, fewer assets, and a lower chance of ever matching their parents' living standards.
Geography makes it worse. England's population is concentrated in ways that unbalance housing demand, infrastructure and political representation. The South East takes growth the planning system will not accommodate. Post-industrial regions have ageing populations, shrinking working-age populations and weakening local economies. These outcomes are not natural. They are the result of decades of underinvestment in regional infrastructure and an economic model that reinforces concentration.
This pillar does not propose a single demographic policy, because demographics cannot be reformed the way a tax system or an electoral system can. It argues that no other pillar in this project can be read properly without understanding its demographic context, and that today's political choices on welfare, housing, NHS funding, immigration and public debt are all, at root, choices about who bears costs and who receives benefits across generations. As set out above, the target is the system that has favoured a wealthy minority, not older people as a whole.
Key Proposals
Recycle a high inheritance tax into early-life public goods as demographic policy. Housing, childcare, and a citizen's endowment, moving capital from the point in the life cycle where it can no longer influence family formation to the point where it determines whether family formation is financially viable.
Close the healthy life expectancy gap rather than set a fertility or demographic target. Housing, childcare, employment, and welfare reforms that remove the structural barriers to family formation and extend working lives, with honest accounting for the fiscal consequences of current demographic trends.
1. Population Structure: What the Data Shows
1.1 Fertility: The Floor Keeps Falling
Fertility in England and Wales has been below replacement level since 1973, so that much is not new. What is new is the speed and depth of the recent fall. In 2010 the total fertility rate was 1.92: below replacement, but stable enough that debate about the long-run population could be put off. By 2024 it had fallen to 1.41, a drop of half a child per woman in fourteen years, with a new record low in each of the last three years.1 Scotland's rate is lower still, at 1.25.
The causes are familiar across developed economies: people form families later because housing costs delay leaving home; childcare is expensive relative to wages; work is insecure for the age group most likely to have children; and there is a growing gap between the number of children people say they want, consistently around two in surveys, and the number they have. That gap is itself a signal for policy. People are not simply choosing smaller families. Many are being priced out of the families they want.
| Country | Total Fertility Rate (2024) |
|---|---|
| England and Wales | 1.41 |
| Scotland | 1.25 |
| France | 1.61 |
| Norway | 1.45 |
| Sweden | 1.43 |
| Netherlands | 1.43 |
| Germany | 1.36 |
| Italy | 1.18 |
| Spain | 1.10 |
| Replacement level | 2.10 |
Sources: ONS and National Records of Scotland for Great Britain; Eurostat for other countries.13
The UK is not an outlier. It sits in the middle of a Europe-wide decline. France is higher but has fallen sharply since 2010, and no major developed economy is at replacement level. The question is not why the UK is unusual but what persistently low fertility means for public finances, and the answer is the same everywhere: fewer future contributors for each person drawing on the state.
1.2 Ageing: The Long-Term Shift
An ageing population is the arithmetic result of low fertility combined with longer lives. UK life expectancy at birth is 79.0 years for men and 82.9 for women4, both far higher than fifty years ago. Longer lives are an achievement, not a problem. The fiscal difficulty arises because the welfare, health and social care systems were designed for a population structure that no longer exists, and are kept going by politicians who have updated neither the systems nor their public account of what those systems cost.
The old-age dependency ratio is the most important single demographic number in UK public finance. The ONS measures it as the number of people of pension age for every 1,000 people of working age. It was 280 in mid-2024, about 3.6 working-age people for each person of pension age, and is projected to reach 310 by mid-2034 and 329 by mid-2049, about 3.0, even after the State Pension age rises to 67.2 On a simple over-65 measure the fall is steeper, because pension-age rises don't count. Each working-age adult will have to fund, through tax and National Insurance, a larger share of pension, health and social care costs than the generation before.
1.3 Life Expectancy: The Inequality Hidden in the Average
The headline life expectancy figure hides a divergence that matters both morally and fiscally. In the most deprived tenth of areas in England, men's healthy life expectancy, the years expected to be lived in good health, was 49.8 years in 2022–24. In the least deprived tenth it was 69.2 years. That is a gap of almost 20 years in healthy life within one country, tracking deprivation, and it widened after the pandemic.
The fiscal consequence is direct. People in deprived areas rely on the NHS, social care and disability benefits for a larger share of their lives, relative to their years in work and paying tax. They are not choosing this. It follows from decades of underinvestment in housing quality, air quality, diet and food environment, primary care, and working conditions in post-industrial regions. The healthy life expectancy gap is an inequality statistic that shows up in health outcomes.
2. Generational Wealth: A Transfer System Running in Reverse
2.1 The Asset Price Boom and Who Gained
Between 1990 and 2024, UK house prices rose by about 385% in cash terms (the average home cost almost five times as much) and roughly doubled in real terms. Real median pay grew far more slowly: by 17% between 1999 and 2023, on the Low Pay Commission's analysis of official earnings data, and by an estimated 35–40% across the whole 1990–2024 period.6 The gap between asset prices and incomes is the defining economic change of the past thirty years. It has redistributed wealth between generations in a way policy has not addressed and political debate has mostly avoided.
People who already owned property in 1990 gained most of that rise passively, without working for it, investing in anything productive, or paying meaningful tax on the gain. People who reached working age after 1990 have faced housing costs that take a growing share of income, leaving them less able to save, build assets, and gain the financial security earlier generations got from buying homes at lower multiples of income.
| Metric | Data |
|---|---|
| Average UK house price (1990) | ~£54,000 |
| Average UK house price (2024) | ~£261,000 |
| Increase in cash terms (1990–2024) | +~385% |
| Increase in real terms (1990–2024, CPI-adjusted) | +~100% |
| Real median hourly pay increase (1999–2023, CPI-adjusted) | +17% |
| Real median hourly pay increase (1990–2024, estimated) | +~35–40% |
| Homeownership, middle-income 25–34-year-olds born late 1960s | 65% |
| Homeownership, middle-income 25–34-year-olds born early 1980s | 27% |
| Average age of first-time buyer (2024) | 33 |
| Boost to lifetime income from inheritance, 1980s-born, parents in top wealth fifth | 29% |
| Boost to lifetime income from inheritance, 1980s-born, parents in bottom wealth fifth | 5% |
2.2 Inheritance: The Transfer Between Generations
Wealth passing between generations, at death and through lifetime gifts, is worth roughly £100–115 billion a year now, and is projected to double or more by the 2040s as the baby boomers, the main beneficiaries of the asset price boom, reach the end of their lives. The Resolution Foundation, using HMRC data, put estates passing on death at £87 billion in 2014–15 and expects inheritances to double over the next two decades. Cebr's projection for Kings Court Trust puts total transfers at £115 billion in 2027 and £355 billion by 2047 in cash terms.8 This is the largest transfer of wealth between generations in British history. Inheritance tax captures about £7.5 billion of it, around 7%.9
The argument most often used against reforming inheritance is that younger people will eventually inherit, closing the housing and wealth gap in time. It fails on three separate counts, and each is worth examining, because the argument is repeated as if it settles the matter when it describes a system that is failing the people it is meant to reassure.
The Timing Problem
The Resolution Foundation estimates, from their parents' life expectancies, that the most common age at which today's young adults will inherit is 61, about thirty years after the age at which they typically start having children.8 Inheritance comes late because parents live longer: a parent who dies at 85 leaves children in their late fifties or early sixties.
The decisions that shape a life are made between about 20 and 40: whether to rent or buy, where to live, whether to start a business or study further, whether to have children and how many. An inheritance at 61 influences none of them. It arrives after the mortgage has been paid off or given up on, after the children have grown up in whatever housing was available, and after a career has been set by whatever capital was available at the time. It can make retirement more comfortable. It does not reach people when capital would have changed the course of their lives.
The Distribution Problem
"The younger generation will inherit" hides an inequality within that generation at least as important as the one between generations. Inheritance does not flow evenly. It goes to people whose parents had assets: the children of homeowners rather than renters, of professionals rather than low-paid workers, of people who built up property wealth rather than those who never had anything to pass on.
The children of homeowners in the South East will inherit six- or seven-figure estates. The children of private renters in post-industrial towns will inherit little or nothing. The children of parents who spent their last years in residential care, at £5,000 a month or more paid out of housing equity, will inherit much less than they expected. Inheritance does not close the wealth gap within the generation receiving it. It reproduces and widens the gap that existed within the generation passing it on.
| Parents' place in the wealth distribution | Projected boost to lifetime income from inheritance, people born in the 1980s |
|---|---|
| Top fifth | 29%10 |
| Bottom fifth | 5% |
For people born in the 1960s the gap was 17% against 2%. People whose parents live in London stand to inherit about twice as much as those whose parents live in the North East or Yorkshire and the Humber. | Children of private renters (all regions) | ~£0 – £15,000 | | Children of social renters | Effectively nil in most cases |
Geography makes the picture starker. A child inheriting a house in Guildford inherits a very different sum from a child inheriting a house in Grimsby, even if both sets of parents spent the same share of income on housing all their lives. The planning system and the concentration of economic activity created that price difference; the heirs did not. But one child gets it and the other does not.
The Care Cost Problem
The third failure of the "they will inherit" argument gets almost no attention: a growing share of the housing wealth the baby boomers built up, which younger people are told will eventually solve their problem, is being spent on social care before it can be passed on.
The means-test threshold for social care in England has been frozen at £23,250 since 2011. Residential care homes now cost about £4,800 a month on average, and nursing care about £6,200. Someone who enters residential care at 82 and lives three more years will spend roughly £173,000 to £224,000 on fees before the state pays anything. Without significant savings, that comes out of housing equity, the asset that was expected to form the inheritance. The wealth does not disappear; it goes to care providers instead of children. For the next generation the effect is the same: the promised inheritance is much smaller, or gone.
The Dilnot Commission identified this problem in 2011 and proposed a £35,000 lifetime cap on care costs, above which the state would pay. A version was legislated in 2014, delayed in 2015, revived with an £86,000 cap in 2021, and abandoned in 2024. Thirteen years have passed without action on a known, costed problem. Meanwhile, hundreds of thousands of families have seen housing wealth meant for inheritance spent on care fees, not through any deliberate policy but because no government chose to fix the system.
2.3 The Two Top 1%s: Wealth and Income Are Different Groups
The "top 1%" is not one group. The top 1% by income (£207,000 a year, about 367,000 of 36.7 million taxpayers) and the top 1% by wealth (about £3.6 million in net worth) are different populations, and the wealthy group is older.11 ONS Wealth and Assets Survey data shows median household wealth peaks at ages 65–74, driven by property (around 40% of total wealth) and pensions (around 35%), both of which build up with age and time. One analysis of the same data found the top 10% of the wealth distribution dominated by people aged 55 and over: a 35-year-old with a £400,000 London flat sits around the 70th percentile of wealth, while a 65-year-old who owns the same flat outright, plus a similar pension, is comfortably in the top 5%.12
That is why "the top 1% pay 28% of income tax" and "wealth is concentrated among older people" do not contradict each other: they measure different things. How concentrated income tax is says almost nothing about the wealth gap between age groups, which is what this pillar's arguments on fertility and inheritance timing depend on.
2.4 The Fertility Consequence: How Late Inheritance Holds Back the Next Generation
The three failures of the inheritance argument (timing, distribution and care costs) do more than let down the generation that receives its inheritance too late. They help suppress the generation that might otherwise have been born. Public debate almost never makes this connection, and it may be the most important consequence of the current system.
Decisions about whether to have children, and how many, are made mostly between 25 and 40. That is when housing is least affordable, childcare costs are highest relative to income, and finances are least secure. Surveys consistently show that people in the UK want around two children on average, but the fertility rate is 1.41. The gap between the two is not a preference. It reflects a financial constraint, and housing cost is its main form.
The inheritance that could have eased that constraint, by providing a deposit that turns renting into owning, lowering housing costs, or giving the security that makes a second or third child feel affordable, arrives at 61. By then the window for having children has closed. A family that might have existed did not, not because the parents chose against it, but because the capital that would have made it possible was tied up in assets held by the generation above and passed on thirty years too late.
This sets up a self-reinforcing spiral that the current inheritance system sustains. Low fertility is partly caused by the financial barriers to starting a family. Those barriers partly reflect wealth being locked in property held by older generations instead of being available to younger people when it would matter. Fewer children means a smaller working-age population in future, which means a weaker tax base, which means less money for the childcare, housing and public services that would make children more affordable. That holds fertility down further.
It is important to be clear about what this argument is and is not. The Generational Reset does not propose a fertility target. It does not propose natalist policy, with the state telling people how many children to have. It proposes removing the financial barriers that explain the gap between the families people say they want and the families they can afford. That is a very different thing: the state ceasing to prop up a system that stops people living the private lives they would choose, rather than the state directing private life.
As inheritances double over the next two decades while earnings grow slowly, what people inherit will matter more and more to their living standards compared with what they earn.8 The more that happens, the more living standards in the UK depend on what people's parents happened to accumulate in an asset price boom they did not create, rather than on their own work and ability. That is a policy outcome, not a market one: the product of specific choices about tax, planning and public investment that could be made differently. The demographic consequences of not doing so are already visible in the fertility data.
Recycling a high inheritance tax at death into public goods for people early in life (housing, childcare and a citizen's endowment) is this pillar's own proposed use for a share of that revenue, and it is demographic policy as much as fiscal policy. It moves capital from the point in life where it can no longer affect decisions about having a family to the point where it decides whether a family is affordable. It does not push anyone to have children. It removes the financial barrier that currently stops people having the children they say they want. It is not part of the Economic Renewal pillar's financing plan: that pillar's §4.1 puts all the projected inheritance tax revenue toward cutting income tax, leaving nothing over on this project's own numbers. This proposal is therefore unfunded within the current model. It states what this pillar thinks a share of that revenue should eventually pay for; it is not a costed commitment.
The fertility rate in England and Wales fell from 1.92 in 2010 to 1.41 in 2024, a record low for the third year running, against survey evidence that people want around two children on average.13 UK house prices rose about 385% in cash terms (roughly doubling in real terms) between 1990 and 2024, against an estimated 35–40% real rise in median pay.6 Today's young adults are most likely to inherit at 61, after the 25-to-40 window in which most decisions about having children are made.8
A gap between the family size people want and the family size they have is consistent with a financial constraint. The timing mismatch is what makes inheritance part of that constraint rather than part of the solution. This connecting argument is this project's own, not a finding any single source states. Capital that could pay for a deposit or childcare during the years when people have children arrives about two decades after that window has closed for most heirs. That is why the sheer size of the wealth does not ease the constraint as much as it might.
The causation above fits responses other than recycling inheritance earlier. One is to treat the fertility gap as mainly a change in preferences rather than a financial constraint, in which case no change to the timing of transfers would close it. Another is to tackle the financial constraint through housing supply alone, building enough homes to bring prices down, without changing how or when wealth passes between generations. A third is direct pronatalist incentives, such as cash payments or tax breaks for having children, as some European governments use, rather than a general early-life transfer with no condition attached. The fourth, this pillar's proposal, is to remove the timing mismatch by recycling a share of inheritance tax revenue into early-life public goods, without steering family size at all.
Choosing an unconditional early-life transfer over direct pronatalist incentives rests on a value judgement this pillar makes openly: removing a financial barrier to something people already say they want is legitimate, while the state paying people to have children, or tying support to family size, is not, even though a conditional incentive might raise fertility more directly and cheaply than a general transfer. A reader who thinks the fertility gap is mainly about preferences, or who would accept direct pronatalist incentives as a more targeted tool, is not wrong on the evidence. They are weighing the same data against a different view of what drives the gap and what the state should do.
Recycle a share of inheritance tax revenue into early-life public goods (housing, childcare and a citizen's endowment) delivered between 25 and 40 rather than at death, as in P1 above. The falsification test below sets out what would show whether the timing mismatch, rather than preference, is the binding constraint on fertility.
3. Geographic Distribution: The Country Within the Country
3.1 The Concentration Problem
England is unevenly populated, and the imbalance is growing. London and the South East produced 39% of UK output (gross value added) in 2023, up from 36% in 2005.14 Some concentration is natural: cities are more productive because they bring labour, capital and knowledge together in ways spread-out areas cannot. But the UK's concentration is extreme by international standards. The productivity gap between London and the rest of the country is larger than the equivalent gap in Germany, France, the Netherlands, or any other comparable European economy.
The demographic side of this is specific. Regions outside London and the South East have older populations, more economic inactivity, lower life expectancy, more disability, and lower average earnings. Their public finances are weaker too, with less tax revenue and more welfare spending per head, because they have more of the groups that cost the public purse most. This is not a moral failing. It is the geography of an economy that has concentrated opportunity for decades and is now paying the growing fiscal cost of that choice.
| Region | Median age │ GVA per head │ Healthy life expectancy (men) |
|---|---|
| London | 37.0 │ £60,500 │ 64.9 years |
| South East | 41.2 │ £33,800 │ 64.3 years |
| East of England | 41.8 │ £29,200 │ 63.6 years |
| South West | 44.1 │ £26,000 │ 64.4 years |
| East Midlands | 41.3 │ £25,400 │ 62.8 years |
| West Midlands | 39.3 │ £25,900 │ 61.4 years |
| Yorkshire & Humber | 40.5 │ £24,100 │ 61.6 years |
| North West | 39.7 │ £25,600 │ 61.3 years |
| North East | 41.4 │ £22,300 │ 60.0 years |
| Wales | 42.5 │ £21,800 │ 61.9 years |
3.2 Internal Migration and What It Reveals
People move between regions in large numbers, for work, cheaper housing and quality of life. The net flow has consistently run from the rest of the country into London and the South East, especially among working-age adults aged 22–35. The logic is simple: opportunity concentrates in high-productivity areas and working-age people follow it. Regions that lose young workers lose tax base and keep ageing populations, which worsens the dependency ratio locally.
The South West shows a different pattern: older people move in to retire to the coast and countryside, while younger adults move out, priced out of local housing. The result is the oldest median age of any English region, and housing markets where demand from retirees crowds out the starter homes that would let local young people stay.
4. The Fiscal Consequence: What the Demographics Cost
4.1 The OBR Long-Run Projection
The Office for Budget Responsibility regularly publishes long-run fiscal projections, and they are sobering. Under unchanged policy, the OBR's central case puts public debt at around 300% of GDP by the mid-2070s, and its own sensitivity tests find that almost every plausible variation still ends on an unsustainable path, driven mainly by age-related spending. NHS costs are projected to rise from 7.6% to 12.2% of GDP, social care from 1.4% to 3.5%, and pensions from 5.1% to 7.9%. Each projection is driven by demographics, not by waste, mismanagement or any particular policy failure. It is simply the cost of an ageing society under the current entitlements.
The OBR's sensitivity analysis shows the path changes a lot under different assumptions. Faster productivity growth lowers the debt path, as does higher net migration; lower fertility raises it. The projection is not a forecast. It shows what happens if nothing fundamental changes, and it is published to create pressure for change. That pressure has not produced change, because the political system rewards short-term responses to high-turnout groups over long-run fiscal responsibility.
4.2 The Dependency Ratio and the Tax Base
Every reform proposed in the Generational Reset, from investment in the NHS and social care to education, housing and criminal justice, depends on a tax base that can pay for it. That base depends on how many working-age contributors there are relative to dependants. As the number of working-age people for each person of pension age falls from about 3.6 to 3.0 by 2049, each working-age adult carries about 17% more of the cost of supporting them at today's level, before the rising health and care costs of an older population are counted.2
This is the reasoning behind the Immigration pillar's "two levers" framing. GDP grows either through more workers or through each worker producing more. In a low-productivity economy with a falling dependency ratio and low fertility, both levers are under pressure at once. Any credible fiscal plan has to face this arithmetic, including whether immigration can be cut to the levels politicians across the spectrum are now competing to promise.
5. What Policy Can and Cannot Change
5.1 What Cannot Be Changed
The shape of the population over the next twenty to thirty years is already set. Everyone who will be over 65 in 2045 is alive now, and their ages are known. The working-age population of 2040 is in school today. Short of dramatic and implausible changes in fertility or radical life-extension technology, the broad shape of the dependency ratio to 2050 is fixed. Policy cannot undo it.
That is not a counsel of despair. It describes the kind of problem this is: a known, long-term adjustment that needs well-designed institutions, not a crisis any single policy can make go away. The countries that have handled similar transitions best, such as Japan, Germany and the Nordic states, did so by building institutions able to run an ageing society without fiscal disaster, not by reversing their demographics.
5.2 What Can Be Changed, and What the Evidence Shows
Fertility policy has a poor record in developed economies. Countries that have tried direct financial incentives, such as baby bonuses, longer parental leave and childcare subsidies, have seen at best modest and temporary rises in fertility. The most effective measures appear to be those that remove the barriers to starting a family rather than those that reward having children: affordable housing that lets young adults set up their own homes; affordable, accessible childcare that makes it viable for both parents to work; and employment conditions that do not penalise career breaks for raising children. These are social policies with a demographic dividend, not fertility policies.
Healthy life expectancy is easier to change than fertility, and the returns are higher. Closing the roughly 20-year gap between the most and least deprived areas would substantially reduce NHS demand and disability benefit claims, and lengthen the working lives of people in post-industrial communities who currently leave work a decade earlier than people in wealthier areas. The investment needed, in housing quality, primary care, air quality, food environment and active help into work, is not speculative. It follows from the existing evidence on what drives the gap.
The Generational Reset does not propose a fertility policy. It proposes the housing, childcare, employment and welfare reforms that remove the barriers explaining the gap between intended and actual fertility. It does not propose a demographic target. It proposes a full public account of what current demographic trends will cost, and the institutional reforms needed to manage those costs without loading them onto the people with the least political voice.
5.3 State Pension Age: A Fair Adjustment
The state pension age is 66 for men and women and is rising to 67 between 2026 and 2028, then to 68 by the mid-2040s under current law. When the state pension was set at 65 in 1948, men reaching that age could expect to live about 12 more years. Today it is about 19. The pension system was designed for a population that no longer exists.
Further rises are contested because they fall unevenly across the healthy life expectancy gap. A man in Kensington can reasonably expect to live and work in good health to 68 or beyond. A man in Middlesbrough or Merthyr Tydfil, where men's healthy life expectancy is below 60, would have to work well past his healthy years before receiving a pension he may never collect. Any further rise in the state pension age must come with credible reform of disability and out-of-work support for people in poor health before pension age. Otherwise it is not a reform but a transfer of cost from the Treasury to the people least able to bear it.
6. The Political Economy of Demographics
The core problem with UK demographic policy is electoral. Older voters turn out more reliably, make up a larger share of the electorate than ever before, and have gained most from forty years of rising asset prices and from the current welfare entitlements. Under first-past-the-post, no governing party has an electoral reason to change any of this, and every reason to protect it.
The result is a feedback loop. The political system over-rewards older voters who own assets. The policies it produces (the triple lock, protected housing wealth, low effective inheritance tax, no capital gains tax on main homes) widen inequality between generations. That raises the stakes for younger voters who cannot use the route to wealth their parents had. When they do engage with politics, it is with little trust in institutions that have repeatedly put someone else first. The Political Renewal pillar is the precondition for breaking this loop. Changing the electoral system does not change demographics, but it does change whose interests the system has to answer to.
7. The Steel Man
The mechanism does move resources across age lines; that is not in dispute. But the objection is about who the policy targets, not what it moves. A high inheritance tax does not fall on older people as a group. Most pensioners are not wealthy: about 1.7 million live in poverty15, and the average State Pension payment was about £10,500 a year in May 2024.16 Estates large enough to face the tax are concentrated in a wealthy minority of the older generation, not the generation as a whole, which is exactly the distinction this pillar draws in rejecting an "old versus young" framing.
The tax targets concentrated wealth wherever it sits in the age distribution. Today that wealth sits mostly in older people's estates because of how four decades of rising asset prices played out, not because age is the target. If the same concentration of wealth belonged to people in their forties instead of their seventies, the same tax would apply to them. That is the difference between a generational policy and a policy on concentrated wealth that currently has a generational shape.
8. Counter-Arguments
'The demographic situation is overstated: fertility rates will recover'
No major developed economy has seen fertility recover for any sustained period. Countries that have seen temporary rises have generally seen them reversed. The underlying drivers (housing costs, childcare costs, insecure work) are not weakening. The bigger risk is that fertility falls further. Building policy on the assumption of recovery is not optimism; it is putting the problem off.
'Immigration can solve the dependency ratio problem'
Immigration helps the dependency ratio a great deal but cannot fix it alone at politically sustainable levels. The OBR's modelling shows that even with fairly high net migration, the dependency ratio falls through 2050. Immigration buys time and softens the adjustment; it does not remove the need to reform entitlements and spending. The Immigration pillar makes this argument in detail.
'Productivity growth can make up for demographic decline'
In principle, yes: if each worker produces enough more, the dependency ratio matters less for the public finances. In practice, UK productivity growth has averaged 0.4% a year since 2008, against 2.2% before. The OBR's scenarios show that even with optimistic productivity assumptions, the long-run debt path remains worrying under current policy. Productivity growth is necessary but not enough. The Economy pillar sets out what has to change to make it more than a theoretical possibility.
'Older people have paid in all their lives and are entitled to what they receive'
This argument deserves a direct and respectful answer. The state pension is not paid from a pot built up from contributions. It is a pay-as-you-go transfer from today's workers to today's retirees. Today's pensioners are paid from today's workers' taxes, and what those workers receive in retirement depends on what the workers of the future are willing and able to pay. This is not a criticism of pensioners. It explains why the sustainability of the system depends on the dependency ratio, and why protecting it means facing the demographic arithmetic, not avoiding it.
Cross-Pillar Dependencies
| Pillar | Connection |
|---|---|
| Political Renewal | Proportional representation, votes at 16, and citizens' assemblies selected to reflect every age group directly change the age balance of political voice. The dependency ratio problem is partly a problem of representation: those who will live longest with today's decisions have the least say in making them. |
| Welfare | The triple lock, the state pension age, and how the welfare budget is split between pensioners and working-age people are all demographic choices. They decide how the cost of an ageing society is shared between generations, and the Welfare pillar cannot be read without the context this pillar provides. On childcare: Welfare's £3bn a year universal early years commitment, funded from triple-lock reform savings, is this project's only currently funded early-years proposal. The childcare mentioned in this pillar is part of the same unfunded recycling idea as the housing and citizen's endowment elements, not a second funded programme. The two pillars do not conflict, but should not be read as funding two separate childcare schemes. |
| NHS | Age-related demand is the main driver of rising NHS costs. The 20-year healthy life expectancy gap is at once an NHS failure, an inequality failure and a fiscal problem; closing it is the best-value investment available for cutting NHS demand and extending working lives. |
| Social Care | Social care costs are almost entirely demographic, driven by the number of people over 80 and how much care they need. The projections are arithmetic, not guesswork. Failing to build a sustainable funding model for social care is a choice to push known costs onto future working-age taxpayers. |
| Housing | The collapse in homeownership among under-35s is a demographic event: it decides whether the generation now renting builds the wealth earlier generations built through property. A generation that reaches retirement without property and with smaller pensions will create fiscal costs that have not yet been fully modelled. |
| Education | The early years are the highest-return demographic investment available. Development at age five predicts educational attainment, lifetime earnings, health and reliance on welfare. Investing in early years is not sentimental. It is the most cost-effective way to enlarge the future tax base and cut future public costs at the same time. |
| Immigration | Immigration is the most direct short- and medium-term lever on the dependency ratio. The Immigration pillar's central argument, that sound immigration policy has to start from a realistic productivity and demographic plan, is this pillar's argument applied to a specific policy area. |
| Economic Renewal | The inheritance tax proposed in the Economic Renewal pillar is demographic policy as much as economic policy. The baby boomers' deaths will bring transfers of roughly £100–115 billion a year now, projected to double or more by the 2040s. That is the moment when wealth passing between generations can either deepen existing inequality or be partly redirected to the public investment a younger generation needs. Correction, 21 September 2026: this pillar's §2.4 previously attributed the idea of recycling revenue into early-life public goods to Economic Renewal. Economic Renewal's §4.1 in fact puts all the projected revenue toward cutting income tax and never proposes this. It now reads as this pillar's own proposed use for a future share of that revenue, flagged as unfunded within the current model. |
| Public Debt | The OBR's long-run projection of debt reaching around 300% of GDP by the mid-2070s is driven almost entirely by demographics. Understanding the debt path means understanding the demographic path, and this pillar is the analytical foundation for the Public Debt pillar's sense of urgency. |
10. Proposals for Change
This pillar does not make reform proposals in the way the spending pillars do, because demographics cannot be reformed, only responded to. The two proposals below are restated for completeness. The pillar's main contribution is the factual foundation the rest of the project rests on.
-
Recycle a share of future inheritance tax revenue into early-life public goods (housing, childcare, a citizen's endowment), moving capital from the point in life where it can no longer affect decisions about having a family to the point where it decides whether a family is affordable. This is unfunded within the project's current model, since Economic Renewal's §4.1 puts all the projected IHT revenue toward cutting income tax.
-
Close the healthy life expectancy gap rather than set a fertility or demographic target, through housing, childcare, employment and welfare reforms that remove the barriers to starting a family and extend working lives, with a full public account of what current demographic trends will cost.
11. What the Evidence Settles
Fertility is at a record low and its drivers are not easing. The population is ageing at a pace that is known, measurable and given too little weight in public debate. By 2049 there are projected to be about three working-age people for each person of pension age, down from 3.6 today, even after the State Pension age rises to 67. The gap in healthy life expectancy between the richest and poorest areas is about 20 years and widened after the pandemic. The transfer of wealth between generations is the largest in British history, and the tax system captures only around 7% of it. Economic activity is concentrating further in a small part of the country, leaving post-industrial regions with older populations, weaker finances and higher public costs.
None of this is secret. All of it is in the published data of the ONS, the OBR, the Resolution Foundation, the Health Foundation and the Government Actuary's Department. The failure is political, not analytical: a system built to answer the short-term demands of high-turnout groups at the expense of everyone else's long-run interests. The Generational Reset is a project to change that.
The Generational Reset | generationalreset.org | Not affiliated with any political party | All documents published under open licence for public discussion and adaptation
The Generational Reset | S4_05: Demographics | For public discussion. Not affiliated with any political party. | generationalreset.org