THE GENERATIONAL RESET
Both sides lied. Here is what trade actually is, what the UK actually sells, and what leaving the single market actually cost.
Executive Summary
The Brexit trade debate was argued in bad faith on both sides, and each side's misrepresentation needs naming. No serious Remain figure claimed Britain would be unable to trade with China, the United States or the rest of the world; that claim doesn't survive a look at what was actually said. The UK traded with every major economy while inside the EU and still does under WTO rules. Rolls-Royce sold engines in Beijing before the referendum, Scotch whisky reached Tokyo, and Range Rovers filled American driveways. EU membership wasn't what made any of that possible, and leaving didn't threaten it.
Where Remain did overstate things was the short-term shock. HM Treasury's May 2016 pre-referendum analysis predicted a year-long recession within two years of a Leave vote, with GDP 3.6–6% smaller, unemployment up by around 500,000 and house prices down by as much as 18%. Those forecasts earned the label "Project Fear", and not entirely unfairly.1 None of it happened at anything like the predicted speed or scale; the UK didn't enter the forecast recession, and the gap between prediction and outcome became one of Leave's most durable lines of attack. Separately, Barack Obama's warning that Britain would go "to the back of the queue" for a US trade deal outside the EU2 was about negotiating priority, not a claim that trade would stop, though campaigners on both sides often blurred it into the stronger, false version. Remain was wrong on timing and severity rather than direction. The Treasury's short-term predictions were too fast and too severe, but its core logic, that leaving the single market would make trade with Britain's largest and nearest partner harder and cost GDP in the long run, has held up. The OBR's long-run estimate is 4%, and comparable estimates from NIESR and the LSE (Section 7.1) run somewhat higher.
Leave's misrepresentation was the mirror image. The campaign accepted that Britain could trade with the world; its claim was narrower, and still wrong: that the EU was stopping Britain from trading with those countries on its own terms, and that independent deals would be clearly better than the ones the EU had negotiated for it. That was false, or at best a sustained overstatement. The EU wasn't blocking Britain from bilateral deals in any commercially meaningful way, and British goods reached world markets under WTO rules that apply to everyone. What the EU gave Britain was negotiating weight, as part of a bloc of 450 million people, that Britain doesn't have alone. Leaving didn't unlock better deals. It handed negotiations to a smaller party with less leverage, and the results since 2021 bear that out.
A trade deal isn't a declaration of friendship between countries. It's an exchange of concessions: lower tariffs for lower tariffs, regulatory alignment for market access, and dispute-resolution arrangements that limit sovereignty in the act of protecting trade. The freedom to negotiate your own deals is real. The claim that those deals would be better, or would make up for leaving your largest and nearest trading partner, wasn't.
The pillar makes five arguments: - The public deserves a clear account of how trade works: what it is, what negotiations involve, and what countries give up to get access. - The UK hasn't been a goods-trading powerhouse for decades. It runs a persistent goods deficit, and its real export strengths are in services, where WTO rules offer almost no protection. - The single market was a different kind of thing from a trade deal, and no outside arrangement can replicate what it provided. - The measurable costs of leaving are real: the OBR's 4% long-run GDP estimate and the recorded friction in sectors where the UK is strong. - The question now is a realistic trade strategy, not a rerun of the referendum: one fit for a mid-sized, services-led economy with particular high-value export strengths and a complicated relationship with its nearest neighbours.
The Generational Reset doesn't campaign to rejoin the EU. It asks for a straight account of what membership provided, what leaving cost and what the realistic options are, because no credible trade policy can be built without one.
Key Proposals
Require an annual OBR Trade Impact Assessment. Quantifying the measured effects of post-Brexit trade arrangements on UK GDP, sectoral output, FDI, and business investment, replacing political assertion with independent measurement.
Enshrine food safety standards in primary legislation. Removed permanently from any trade negotiating mandate without explicit parliamentary approval, rather than left to executive discretion.
Publish negotiating mandates touching NHS pricing before deals conclude. Where NHS pharmaceutical pricing, procurement access, or NICE methodology are relevant to a counterpart's objectives, the public has a right to know what is being offered in their name before negotiations close.
Pursue a UK-EU Services and Investment Framework as the primary trade objective. Stable financial services equivalence, mutual recognition of professional qualifications, and a creative industries protocol.
Establish a Services Export Strategy with binding sectoral targets. Financial services, professional services, creative industries, and higher education — the UK's genuine competitive strengths — rather than a goods-tariff-led trade policy.
Commission an independent assessment of UK–US trade arrangements before any further concessions. Including the December 2025 medicines deal: what the US has offered against what the UK has conceded and would need to concede on agriculture, food standards and NICE pricing, pursued mainly through the defence and security relationship that gives the UK its real leverage.
1. How Trade Works: What Both Campaigns Got Wrong
The most useful correction this pillar can offer is a basic one. Most people in Britain don't have an accurate picture of what international trade is, how it's governed or what trade agreements do, and both Brexit campaigns exploited that.
1.1 The WTO Baseline: The Floor Both Sides Ignored
The World Trade Organization governs trade between its 166 members through agreed rules, the most important being Most Favoured Nation (MFN). Under MFN, a tariff rate offered to one WTO member on a product must be offered to all of them. That creates a worldwide floor of market access, whether or not two countries have a bilateral trade agreement.
The UK traded with China, the United States, Japan and every other major economy while inside the EU. That wasn't because the EU allowed it, but because WTO rules guaranteed basic access. Rolls-Royce doesn't need an EU-China trade deal to sell aero engines in Beijing, and Scotch whisky reaches Japan under MFN tariffs that apply to everyone. As the Executive Summary says, no serious Remain figure claimed leaving the EU would cut this off. Remain's overstatement lay elsewhere: in how severe and how fast it said the short-term shock to the whole economy would be.
1.2 What a Trade Deal Actually Is
A trade deal is an exchange of concessions. Both sides give something up to get something back, a basic fact almost no Brexit commentary acknowledged.
The concessions come in three kinds. First, tariff cuts: you lower your import tariffs on their goods and they lower theirs on yours. Your exporters gain, but domestic producers face cheaper imports, so tariff cuts never come free. Second, regulatory alignment or mutual recognition: you accept their standards, or agree that yours are equivalent. This is the part that limits sovereignty. You can't have full regulatory independence and frictionless market access at the same time; the two pull directly against each other. Third, dispute resolution: you accept some mechanism for settling disputes. Critics called this surrendering control of British law, but every trade deal needs it, because without it agreements can't be enforced. The Leave campaign promised trade deals without these costs. No such deals exist.
1.3 The Leverage Problem: Size Sets the Terms
Negotiating leverage in trade comes from market size. The EU negotiates as a bloc of 450 million consumers, the largest market-access prize in the world. The UK on its own has about 69 million consumers and roughly 3.4% of global GDP. Against the United States, with 340 million consumers and 26% of global GDP, the imbalance is severe. The US can wait; it has other priorities. The UK needs a deal more obviously and more urgently, and the American negotiators know it.
That imbalance comes from the numbers, not from diplomacy, and no amount of negotiating skill changes it. A country with a large home market and varied trading relationships can walk away from a bad deal. A country that has just left its main trading bloc and needs to show a trade dividend can't. That has been the UK's position, and it has shaped every significant trade negotiation since 2016.
2. What the UK Trades: The Real Picture
The second basic correction concerns how the UK economy is actually made up. The image of Britain as a trading nation, with its merchant fleets, imperial commerce and "workshop of the world", is historically true and misleading today. The UK of 2025 isn't the UK of 1885. Its competitive strengths are in services, and its goods trade has been in deficit for decades.
2.1 The Goods Trade Reality
The UK has run a goods trade deficit every year since 1983. In 2024 the deficit was more than £200 billion: the UK imported far more goods than it exported. That isn't a temporary imbalance. It's the long-term result of four decades of moving away from manufacturing and towards services.
The goods the UK does export successfully are concentrated in a few high-value categories: aerospace (Rolls-Royce engines, Airbus wings), pharmaceuticals, Scotch whisky, luxury cars (Range Rover, Bentley, Jaguar) and specialist chemicals. They are world-class products that compete on quality and brand. But they were already doing well inside the EU, and they're too few and too small in total to carry the broad export growth the Leave campaign implied was available.
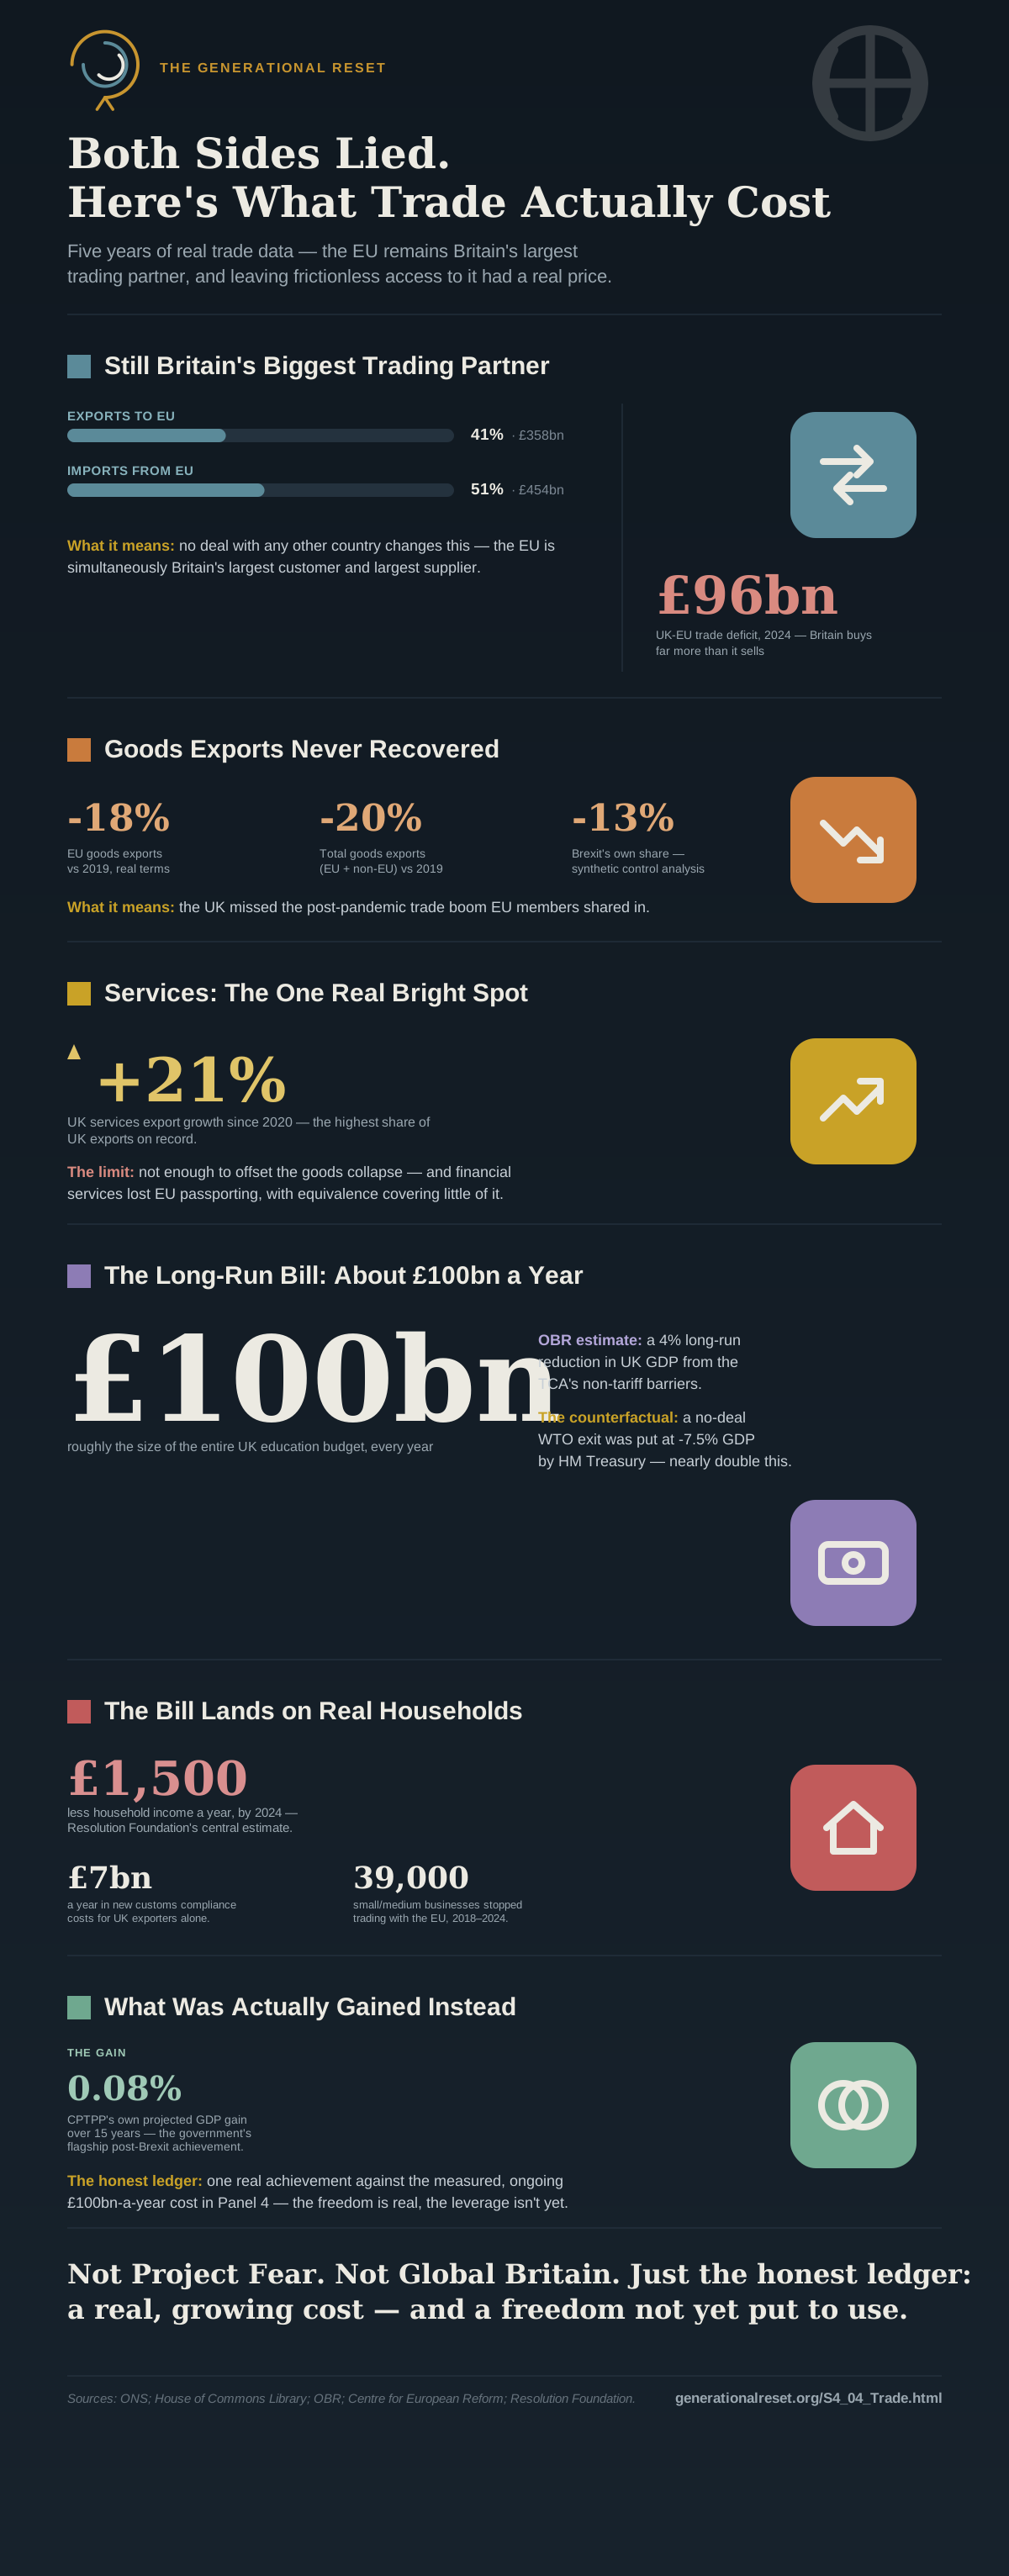
The UK has run a goods trade deficit every year since 1983, more than £200bn in 2024, while financial services alone generate £209bn of GVA and the creative industries about £146bn, sectors where Britain competes at world level. Services trade sits almost entirely outside the WTO framework; GATS provides only a thin baseline, far short of the market access goods enjoy. Services exports have grown 21% since 2020, the one clear bright spot, but not by enough to offset the fall in goods exports.3
Global and bilateral trade rules are built overwhelmingly to cut barriers to goods, not services. (This step is the project's own reasoning, drawing the facts above together; no single source makes it.) Because the UK's real advantage lies in services while the available trade-deal toolkit addresses goods, a trade strategy built mainly around signing new agreements will consistently underserve the sectors that hold up the UK economy. Financial services shows this clearly: passporting is gone, equivalence is one-sided and can be withdrawn at 30 days' notice, and jobs, regulatory capital and decision-making have measurably moved to Dublin, Luxembourg, Amsterdam and Frankfurt.
That reasoning allows for responses other than deeper ties with the EU. One is to pursue new goods-focused trade deals on the CPTPP model, on the view that a mismatched toolkit beats none, while accepting that such deals mostly help a small UK export base that's already competing successfully. Another is to focus industrial strategy at home on broadening and strengthening goods exports, instead of chasing services access no partner is offering. The third, which this pillar proposes, is to prioritise a negotiated deepening of UK-EU services trade specifically, on the basis that no other partner can stand in for the UK's largest and nearest market.
Putting deeper EU services access ahead of new global trade deals is a value judgement this pillar states openly: realistic gains in the sector the UK actually depends on matter more than the political story of new "Global Britain" agreements, even though re-engaging with the EU is politically harder than signing deals with distant partners. A reader who values the diversification that new goods deals bring, or who thinks renewed EU services talks are politically unrealistic whatever their economic logic, isn't wrong about the evidence; they read the same trade data with a different view of what's achievable.
Make a negotiated deepening of UK-EU financial and professional services trade a strategic priority, as the Reform Commitment below sets out, instead of treating new goods deals with distant partners as the main answer to Brexit's trade costs. The falsification test below says what would show this priority is actually closing the gap in services access, rather than just moving political attention.
2.2 Where the UK Is Strong: Services
The UK's real competitive advantages are in financial services, professional services, the creative industries, higher education and specialist consulting. Financial services alone produce £209 billion of GVA and make London the world's second-largest financial centre. The creative industries contribute about £146 billion a year. These are the sectors where Britain competes at world level.
The difficulty is that services trade sits almost entirely outside the WTO framework. The General Agreement on Trade in Services (GATS) provides a thin baseline, far short of the access goods get under WTO rules. Services access is negotiated country by country and sector by sector, and usually delivers much less than the political language around trade deals suggests. That is the basic mismatch at the heart of UK trade policy: the country is strongest where the global trade system is weakest.
2.3 Financial Services: Passporting Is Gone and Equivalence Is No Substitute
EU passporting let UK-based financial firms sell their products and services across all 27 member states under a single authorisation. The Trade and Cooperation Agreement says almost nothing about financial services. The UK asked for equivalence, a ruling by the EU that UK regulation is close enough to its own to allow market access, and the EU has granted it only in a few narrow areas. Equivalence is decided by the EU alone, can be withdrawn at 30 days' notice and covers a fraction of what passporting did. It isn't a substitute.
As a result, UK financial firms that need EU market access have set up subsidiaries in Dublin, Luxembourg, Amsterdam and Frankfurt, and the jobs, the regulatory capital and, increasingly, the decision-making have followed. London is still formidable. But the direction of travel, with EU financial centres gaining at the margin what UK-based operations lose, shows up in the data and is unlikely to reverse under current arrangements.
3. The Single Market: What It Was
The biggest conceptual mistake in the Brexit trade debate was treating the single market as if it were a trade agreement. They are different kinds of thing, and the difference is essential to understanding what the UK gave up.
A trade agreement lowers barriers between two parties, mainly tariffs, while each keeps its own rules at home. A customs union goes further, adding a common external tariff so goods can move without rules-of-origin checks. The single market goes further still. It harmonises the underlying rules, so a product approved in one member state is automatically approved in all of them, a service provider licensed in one country can operate in every country, and capital and people move freely.
The TCA restored zero tariffs on goods traded between the UK and the EU, a real achievement. But it didn't and couldn't restore the shared rulebook that made the single market what it was. Customs declarations are now required. Rules-of-origin certificates have to be produced. Separate regulatory approvals have to be obtained, professional qualifications revalidated and work permits applied for. None of this is EU spite. It follows mechanically from having two different sets of rules, which is what leaving the single market means.
3.1 The Standards Nobody Named: What the Single Market Did for British Consumers
The single market didn't just provide market access. It set a regulatory floor for product safety, food, the environment and chemicals that applied to everything sold within it, wherever it was made. British consumers benefited for decades without knowing it, because the standards worked, and regulation that works is invisible. A food scandal that never happens makes no headlines.
EU food and farming standards are among the highest in the world and rest on the precautionary principle: where the science on a risk is uncertain, the burden is on proving something safe, not on proving it harmful. That is why chlorine-washed chicken isn't sold in British supermarkets. No specifically British law banned it; EU standards for the single market did, and the UK benefited automatically as a member. The same principle covers hormone-treated beef, certain pesticide residue limits, labelling of genetically modified food, and a range of food additives allowed in the United States but not in the EU single market.
Beyond food, EU product safety standards (the CE marking system) covered toys, electrical goods, medical devices, cosmetics and thousands of other kinds of product. A toy sold anywhere in the EU had to meet standards that applied across the whole market, so a British parent buying a toy from a European maker was protected by a system they had probably never heard of. Since Brexit the UK has set up its own UKCA mark, broadly equivalent to CE, but UK manufacturers exporting to the EU still need CE certification. They haven't gained regulatory sovereignty; they've gained a domestic mark and lost the seamless recognition membership gave them.
3.2 The Rule-Taker Problem: Sovereignty in Practice
The Leave campaign's central promise was to restore British sovereignty: the power to make British rules for British people. That's a legitimate value. The question is what it means in practice for a country that sells a large share of its exports into the EU single market.
Inside the EU, the UK had a vote on the single market's rules. British ministers sat in the Council, British MEPs sat in the Parliament, and British officials helped draft technical standards in the regulatory committees. In trade-policy language, the UK was a rule-maker. The rules weren't always the ones it would have chosen on its own; that's the nature of collective decisions. But British influence was real, on the record and significant. British positions on financial regulation, data protection and competition policy shaped the rules of the world's largest single market.
Outside the EU, any UK business that exports to the EU still has to meet EU standards, which haven't been lowered because Britain left. A British drug company selling into the EU must meet European Medicines Agency standards; a British food exporter must meet EU food safety rules; a British carmaker must meet EU vehicle type approval. The rules are the same as under membership. The difference is that Britain no longer helps write them. In practice, regulatory sovereignty has meant freedom to set standards for the home market, plus an obligation to meet EU standards for exports, with no say over what those standards will be next year or the year after.
4. The Deal Britain Had: What the Campaigns Never Said
There's a simple test of how much sovereignty EU membership took out of everyday British life, and it's in every room of every house in the country.
The British plug socket, BS 1363, with three rectangular pins in a triangle, its own fuse and shuttered live and neutral slots, is unique to Britain; no other country uses it. It was designed in 1946 and has been the British standard ever since. Britain was an EU member for 47 years, and not once in that time was the British plug changed, threatened or harmonised away. It's exactly as it was before the UK joined the European Economic Community in 1973.
That's more than a curiosity. It shows as concretely as anything can how the single market worked. It harmonised where that served the purpose of a single market: safety standards for goods traded across borders, regulation of capital moving between member states, food standards for farm products sold throughout the union. It left alone the things that were distinctively national and didn't affect cross-border trade. The British plug is in every British home because no European lorry driver ever needed to use one.
The car makes the same point even more vividly. Britain drives on the left, unlike every continental EU member. British number plates follow a British format, British speedometers read in miles per hour, MOT standards are set by the DVSA, road tax is run by the DVLA, and motor insurance is regulated by the FCA under British law. EU membership touched none of it, and none of it was ever under threat. The Leave campaign's picture of faceless Brussels bureaucrats dictating to Britain never stretched to asking why, after 47 years, the British were still driving on the left.
Free movement worked the same way, in both directions. The campaign presented it as Europeans coming to Britain, but it ran both ways. At the time of the referendum, about 1.3 million British citizens were living and working in EU countries, in Spain, France, Germany, Italy, Portugal and across the continent. More than 200,000 young British people had studied at European universities through Erasmus, with their fees subsidised and their credits recognised. The right to work in Paris, retire to Tuscany or study in Amsterdam was a British right that British people used, and it was given up in the same vote that promised to take back control.
4.1 The Exceptional Position Britain Had, and Won't Have Again
Britain wasn't an average member state. Decades of negotiation had given it an arrangement no other country had, and no country leaving and then trying to rejoin would ever be offered again.
The UK kept the pound. Every other major EU economy uses the euro or is committed to adopting it. Britain's monetary policy was set by the Bank of England, not the European Central Bank, and British interest rates, quantitative easing and currency management stayed fully under British control throughout membership.
Britain was outside Schengen. The passport-free travel area covering most of continental Europe never included the UK. Passport checks at Dover, Heathrow and St Pancras were British decisions throughout membership, and the UK could and did enforce them.
Britain had the Thatcher rebate, a permanent reduction in its budget contribution negotiated in 1984, which brought the UK's net payment down to about £9 billion a year. Other member states resented it, and it would not be available to any new or returning member.
Britain had an opt-out from the domestic application of the Charter of Fundamental Rights, and chose case by case whether to join justice and home affairs measures instead of taking part automatically. Altogether it had more formal opt-outs and special arrangements than any other member state.
The £9 billion net contribution, the figure the Leave campaign cited most, needs context. It was about 0.4% of GDP, and it bought membership of a market the OBR estimates was worth 4% of GDP in trade and investment. That isn't a hard sum. And the deal that delivered it (the rebate, the opt-outs, the pound) took decades to negotiate and will never be available to Britain again in any form.
5. The World's Trading Blocs: Gains, Losses and Where the UK Sits
To see what leaving the single market meant strategically, you have to understand how global trade is organised. Most of the world's economic weight sits in a handful of large trading blocs. The Brexit debate presented this as an opportunity: Britain free to deal with all of them on its own terms. The reality is more complicated. The UK already traded with most of these blocs before Brexit, the EU had negotiated most of those relationships on Britain's behalf, and leaving the EU changed Britain's leverage with every one of them.
5.1 The EU Single Market: What Was Lost
The EU single market is more than a trading bloc. It's a regulatory union of 27 member states, 446 million consumers and about 18% of global GDP. As a member, the UK had zero-tariff, frictionless access to all of it, for goods, services, capital and people. It helped set the rules, and it benefited from the EU's negotiating weight in every other relationship in the world.
What the UK gained from membership: frictionless access for goods and services to a £14 trillion market next door; passporting for financial services across all 27 states; free movement for the 1.3 million British citizens living and working in Europe; Erasmus for 200,000 British students; EU food and product safety standards protecting British consumers; the EU's bargaining power with the US, China and every other major economy; and a seat at the table writing the rules for the world's largest trading area. What the UK gave up: a net budget contribution of £9bn a year, some regulatory independence in areas harmonised for the single market, and the constraints of collective decision-making. It wasn't a close call.
Since Brexit, the TCA has kept zero tariffs on goods but put up a full regulatory border, ended passporting and free movement, and taken the UK out of the EU's negotiating bloc. UK goods exports to the EU are 18% below their 2019 level in real terms. Financial services operations have moved to Dublin, Amsterdam and Frankfurt. Small and medium-sized exporters have stopped trading with Europe rather than absorb the paperwork costs.
5.1a Defence: The Dimension the Brexit Debate Ignored
One part of the UK-EU relationship the Brexit trade debate almost entirely ignored is defence. EU membership was never mainly about defence, which was NATO's job, and Leave campaigners rightly said defence cooperation would continue outside the EU. It did. What that obscured was how much the EU relationship supports the practical side of European defence: industrial cooperation, joint procurement, and the political conditions for security partnerships.
The Defence pillar of the Generational Reset covers this in detail. UK defence procurement depends on European industrial partners: MBDA for missiles, Airbus for transport aircraft, the GCAP programme with Italy and Japan, and a submarine industrial base that relies on specialist European components. These aren't formally EU programmes, but they work within a political and regulatory environment shaped by the UK-EU relationship. Post-Brexit friction in defence cooperation (customs classification of dual-use parts, movement of defence engineers, data-sharing arrangements) adds cost and delay to programmes that are already persistently over budget.
More significantly, Macron's dissuasion avancée initiative of March 2026 and the July 2025 UK-France nuclear coordination agreement, the biggest change in European nuclear posture since de Gaulle, were made possible partly by the wider UK-EU rapprochement that followed the Labour government's reset in 2024–25. The conditions for closer defence cooperation and for closer trade cooperation are the same: a UK-EU relationship run as a partnership rather than an adversarial negotiation. This project's Trade and Defence pillars aren't separate arguments. They're one argument about the consequences of where Britain has placed itself strategically, seen from two angles.
5.2 USMCA: The Bloc We're Not In
The US-Mexico-Canada Agreement covers about 510 million people and roughly 28% of global GDP, making it the largest trade zone by nominal GDP. Trade in goods and services between its three members reached $1.9 trillion in 2024. The US is the UK's largest single-country trading partner, with total bilateral trade of £329.5bn in the year to September 2025, up from £314.6bn in 2024.5 But the UK isn't in USMCA and has no full trade agreement with the US. The Economic Prosperity Deal of May 2025 is a limited tariff arrangement: it cut the US tariff on a quota of 100,000 UK cars a year to 10%, with separate arrangements for steel and, later, pharmaceuticals.6
What the UK could gain from a US deal: the US is already the biggest buyer of UK services exports, £140bn in 2024, led by business services (£61bn), financial services (£28bn) and insurance (£12bn). A deal with real services coverage could protect and grow those flows, give certainty on data, and add digital trade rules that suit UK strengths. What the UK would have to give: access for American farm exports produced to standards below those EU membership required (chlorine-washed chicken, hormone-treated beef), and higher NHS spending on medicines, which the UK has already conceded in part (Section 8.3). The imbalance in leverage is severe: the US is 26% of global GDP, the UK about 3.4%.
So a full UK-US deal is possible in theory but stuck in practice. The US wants farm and NHS concessions the UK won't make, and the UK wants deeper services access than the US will give. Leaving the EU didn't bring a US deal closer; it took the EU's scale off the table and widened the leverage gap. With 69% of UK exports to the US being services, any deal has to put services first, and no government has negotiated seriously on that basis.
5.3 RCEP: The Bloc the UK Can't Join
The Regional Comprehensive Economic Partnership is the world's largest free trade agreement by GDP: 15 Asia-Pacific countries including China, Japan, South Korea, Indonesia and the ASEAN states, together about 30% of global GDP and 2.2 billion people. Trade between its members has grown fast since it came into force in January 2022; China's trade with RCEP partners passed $5.4 trillion in the three years to 2024. RCEP aims to remove tariffs on more than 90% of goods traded between members within 20 years, and sets common rules of origin across the whole bloc.
The UK isn't in RCEP and has no real prospect of joining. RCEP was designed as an Asia-Pacific agreement, and the UK has no geographical case for membership. It trades with China, Japan, South Korea and the ASEAN economies on WTO MFN terms, the same terms any WTO member gets, with no preferential access. UK exports to China fell 11% in the year to the third quarter of 2025, partly because of geopolitical distance and partly because RCEP members get preferential access to each other that the UK doesn't.7
The Leave campaign promised that outside the EU, Britain could build its own relationships with these fast-growing Asian economies. The arithmetic: UK trade with Southeast Asia and China would need to grow by 15–20% a quarter for 18 months just to match UK trade with the euro area. That isn't a realistic near-term path. And RCEP's trade diversion, from non-members to members, will increasingly put UK exporters at a disadvantage in Asian markets against competitors inside the bloc who pay no tariffs while UK exporters pay MFN rates.
5.4 CPTPP: What Was Gained
CPTPP is the UK's biggest post-Brexit trade achievement. It covers 12 countries including Japan, Canada, Australia, Mexico, Vietnam and Singapore, about 15% of global GDP. The UK joined in 2024, the first country to join after the founders. The agreement removes tariffs on goods comprehensively and includes digital trade rules, services commitments and modern rules on intellectual property and investment.
What the UK gained: new preferential access to Brunei, Malaysia, Vietnam and Chile, with which it had no previous deal; better access to Canada in some areas than the inherited EU-Canada deal; a closer institutional relationship with Japan, Singapore and Australia beyond the existing bilateral deals; and digital trade and services commitments more up to date than those in the inherited EU agreements.
What the UK didn't gain: meaningfully better access to Japan, Singapore, Australia, New Zealand or Canada, where inherited EU-era deals already provided most of the preferential access. The government's own modelling projected a GDP gain of 0.08% over 15 years. That isn't because CPTPP is worthless, but because the agreements it replaced had already done most of the work. CPTPP's deeper value is institutional: membership of a growing Asia-Pacific group that could expand to include South Korea, India and possibly China gives the UK a platform for future relationships rather than an immediate trade dividend.
5.5 The UK Alone: Where It Stands
View underlying data as a table
| Trading Bloc | Global GDP share | UK status | Net gain or loss vs pre-Brexit position |
|---|---|---|---|
| EU Single Market | ~18% | TCA; outside the single market | NET LOSS. Zero tariffs on goods kept; passporting gone; regulatory border put up; goods exports -18% in real terms vs 20193; small exporters stopped trading. OBR: -4% GDP in the long run8 |
| USMCA / US | ~28% | Limited 2025 tariff deal; no full trade agreement | NEUTRAL to SLIGHT LOSS. The UK already traded freely with the US under WTO rules. No full deal has materialised, the 2025 arrangement mainly limits new US tariffs, and the EU's negotiating scale has been lost. UK exports to the US remain strong (£203bn) |
| RCEP (China/Japan/ASEAN) | ~30% | Outside RCEP; WTO MFN terms only | LOSS vs RCEP members. UK exports to China -11% in the year to Q3 2025. RCEP trade diversion increasingly disadvantages UK suppliers against competitors with tariff-free access to ASEAN. Brexit didn't cause this, but it removed the EU weight that might have addressed it |
| CPTPP (Pacific 11 + UK) | ~15% | Full member since 2024 | MARGINAL GAIN. New access in Brunei, Malaysia, Vietnam and Chile; better terms with Canada. GDP impact +0.08% over 15 years on the government's own assessment. The real long-term case is as a platform for future Asia-Pacific relationships |
| UK standalone | ~3.4% | Negotiating alone | Net position vs pre-Brexit: negotiating with blocs 4–9 times its economic size, without the EU's scale behind it. The freedom is real, the leverage is smaller, and so far the results reflect the leverage rather than the freedom |
The table above is the ledger. The UK traded with most of these blocs before Brexit; EU membership didn't stop it. What Brexit changed was the terms: the UK lost the EU's negotiating scale and the single market's depth of access, and gained the freedom to negotiate on its own. That freedom has produced one significant new achievement, CPTPP, and so far nothing else. The effect shows in the data.
6. The Trade Data Before and After: What Changed by Sector
The overall picture matters, but the sector-by-sector picture tells you more. It shows where Brexit friction has hit hardest, where other forces (the pandemic, global supply-chain disruption, commodity price swings) are the main explanation, and where Leave's promise of new export opportunities has and hasn't come true.
6.1 Goods Trade: The Headline Picture
UK goods exports to the EU were above £170 billion in each of 2017, 2018 and 2019, and haven't reached that level in any year since; in 2024 they were 18% below the 2019 level in real terms.3 Not all of that is Brexit: the pandemic badly disrupted world trade, and UK goods exports to non-EU countries also fell, to 14% below their 2019 level in real terms. But the fall in exports to the EU is bigger, more persistent and concentrated in the sectors most exposed to the new non-tariff barriers, which is what you'd expect to see if Brexit friction is a major cause alongside the global disruption.
The most striking finding concerns small firms. Research by the LSE's Centre for Economic Performance, using data on more than 100,000 firms, found that about 16,400 businesses, 14% of those that had exported goods to the EU, stopped doing so once the TCA came into force in 2021, and that the TCA cut total UK goods exports by about £27bn (6.4%) in 2022. Most of those that stopped were smaller firms.9 These aren't multinationals with compliance departments. They're the businesses for which customs declarations, rules-of-origin certificates and sanitary checks cost too much relative to their European sales.
| Sector | 2019 (pre-Brexit) | 2024 (post-Brexit) | Primary driver of change |
|---|---|---|---|
| UK goods exports to EU (total) | Over £170bn a year (2017–19) | 18% below 2019 in real terms | Brexit friction and the pandemic, both significant; the fall in EU exports is larger and more persistent than in non-EU exports |
| UK services exports to EU | Pre-TCA level | Higher than in 2019 | Services trade proved more resilient than goods, with growth led by financial and professional services, though below what it would have been with passporting intact |
| Food & drink exports to EU | Pre-TCA peak | Sharply lower | Mainly Brexit: sanitary and phytosanitary checks at the border hit fresh produce hardest. 64% of UK food exports still go to the EU, but volumes are well down |
| Automotive (car exports to EU) | ~£10bn+ | The EU is still the largest market for UK-built cars | Mixed. Stricter TCA rules of origin for electric vehicle batteries, postponed by UK-EU agreement in 2023, apply from 2027 and are a major risk for UK manufacturing |
| Aerospace (Rolls-Royce, Airbus) | ~10% of goods exports | Recovering but below 2019 | Mainly the pandemic: global aircraft deliveries halved between 2018 and 2020. Brexit-specific friction is smaller but real in certification and parts supply |
| Pharmaceuticals to EU | £12bn+ (2024) | Broadly maintained | Long supply contracts cushion short-term friction, but UK firms now need separate EMA and MHRA approvals, adding to regulatory costs |
| Financial services surplus (EU) | ~£26bn surplus | £34bn exports, surplus maintained | The headline holds up, but a deeper shift is under way: EU subsidiary assets now exceed €1 trillion, and London is losing market share in euro clearing, share listings and derivatives |
7. The Hard Brexit Counterfactual: What Was Avoided
One argument that keeps coming back, especially from Leave supporters, is that the trade problems since 2021 come from a Brexit that was "not done properly". It comes in two forms: that a harder, cleaner WTO Brexit would have been better than the half-in, half-out TCA; and that staying a full member, had Remain won, would only have continued an unsatisfactory status quo. Both deserve a serious answer.
7.1 The WTO No-Deal Scenario: What the Numbers Show
The OBR modelled a no-deal, WTO-terms Brexit in its November 2020 forecast, alongside its assessment of the TCA. Its central estimate was that trading on WTO terms without the TCA would reduce UK GDP by about 6% in the long run, against 4% for the TCA as implemented. The National Institute of Economic and Social Research estimated a 5–6% reduction under WTO terms against 3–4% for a standard free trade agreement, and the LSE's Centre for Economic Performance estimated 5.5–7% for WTO terms.
So the TCA was worth about 2 percentage points of long-run GDP compared with no deal, roughly £50 billion of output a year at 2024 prices. That's a substantial gain. The TCA, concluded on Christmas Eve 2020 after years of political chaos, delivered something clearly better than the alternative, and that deserves credit. The fair benchmark for judging the TCA is the no-deal cliff edge that was the realistic alternative in late 2020, not EU membership.
The OBR's long-run estimate is that the TCA's non-tariff barriers reduce UK GDP by about 4%, over £100bn a year at 2024 levels, close to the size of the entire education budget.8 UK goods exports to the EU are 18% below their 2019 level in real terms.3 The EU is still the UK's largest single trading relationship: 41% of exports and 51% of imports.4 The same OBR modelling found that the no-deal WTO alternative would have cost about 6% of GDP; NIESR estimated 5–6% and the LSE 5.5–7% for the same scenario.
The TCA removed tariffs but couldn't recreate the single market's shared rulebook, and it's the loss of that frictionless alignment, not tariffs, that drives both the 18% fall in goods exports and the 4% GDP estimate. (This step is the project's own reasoning; no single source makes it.) Customs declarations, rules-of-origin certificates and separate regulatory approvals are what link a zero-tariff deal to a measurable loss of GDP: friction from a regulatory border, not from what goods cost at that border.
That reasoning allows for responses other than deepening the TCA. One is a harder, cleaner WTO Brexit, on the theory that a clean break would allow faster divergence and bigger gains. This pillar's §7.2 rejects that as unsupported by the evidence, and the OBR, NIESR and LSE modelling above shows it would have cost 5.5–7% of GDP, clearly worse than the TCA's 4%. Another is to campaign to rejoin the single market and restore the shared rulebook entirely, a position this project explicitly doesn't take. The third, which this pillar proposes, is to deepen the existing TCA through a negotiated UK-EU Services and Investment Framework, narrowing the regulatory gap in the sectors where the cost is concentrated (financial and professional services) without reopening single market membership.
Choosing to deepen the TCA rather than campaign to rejoin or diverge further is a value judgement this pillar states openly: practical, negotiable improvement within the current framework is worth more than refighting a settled referendum, even though full single market membership would recover more of the estimated 4% GDP gap than a Services and Investment Framework plausibly could. A reader who puts recovering the full economic cost ahead of political feasibility, and thinks rejoining is worth reopening that fight, isn't wrong about the evidence; they weigh the same OBR figures against a different tolerance for political cost.
Make a UK-EU Services and Investment Framework the main trade objective (financial services equivalence, mutual recognition of professional qualifications and a creative industries protocol) and require an annual OBR Trade Impact Assessment to measure whether it is actually narrowing the 4% GDP gap. The falsification test below says what would show this approach isn't closing that gap.
7.2 The 'Clean Brexit' Argument: Why It Doesn't Hold
The harder version of the argument, that a clean WTO Brexit would have been better, rests on the idea that a complete regulatory break would have allowed faster divergence and bigger regulatory gains than the TCA's hybrid. That hangs together in theory but has no evidence behind it. Under WTO terms, UK cars would have faced the EU's 10% tariff and many farm products much higher ones, often 40% or more for lamb and beef. Medicines and most civil aircraft parts are tariff-free under WTO agreements, so the exposure is uneven, but it falls on some of the UK's most important goods exports. Those tariffs matter for industries working on thin margins in competitive global markets.
The "not done properly" argument also struggles to say what "properly" would have meant. The TCA is a shallow agreement, covering goods thoroughly and services barely at all, because the UK government chose regulatory divergence over deeper market access. A deeper TCA, with more services coverage and less regulatory distance from the EU, would have meant accepting more EU rules. The choice about how deep to go was made, and what we see now is its consequence. To argue that a different choice, towards less integration rather than more, would have done better, you'd need to name the extra regulatory freedoms that would have produced enough gain to outweigh the extra trade barriers. Nobody has made that case rigorously.
8. The Rest-of-World Deals: What They Delivered
Leave's central trade promise was that Brexit would let the UK negotiate better deals with the rest of the world than the EU could get for it. Eight years on, the results are in.
8.1 The Inherited Deals
When the UK left the EU, it also left the trade agreements the EU had negotiated on its behalf with more than 70 countries. The first job of post-Brexit trade policy was to roll these over into bilateral deals on broadly the same terms. That was largely done, but it wasn't a triumph of British negotiating power: most countries agreed to copy the existing terms because it cost them nothing. The rolled-over deals gave no better access than the EU agreements had. They gave continuity, a floor rather than an improvement.
8.2 CPTPP: The Government's Flagship
The government presented joining the Comprehensive and Progressive Agreement for Trans-Pacific Partnership as a landmark. Its own modelling projected a GDP gain of 0.08% over 15 years. That is a considered estimate of almost no economic effect. The reason is that the UK already had deals, inherited from EU membership, with most CPTPP members: Japan, Canada, Australia, New Zealand and Singapore. The new access was limited. CPTPP is a real institutional achievement. It isn't the compensation for leaving the single market that it was presented as.
8.3 The US Deal: The NHS Question
A UK-US trade deal was the most symbolically important promise of Leave's trade agenda. A full deal hasn't happened; the limited tariff deal of May 2025 is no substitute. The reasons show the leverage problem clearly. The US wants wider access for American farm exports (chlorine-washed chicken, hormone-treated beef, American dairy) that UK food standards currently ban. Granting it would mean either changing those standards or accepting a two-tier system, and no government has found either politically acceptable. That follows directly from the standards point in section 3: the EU food safety floor is now a British standard, and dropping it is the price of a US deal.
The farm question got most of the public attention. NHS access got almost none. US pharmaceutical and healthcare companies have a long-standing, published interest in two parts of any UK-US deal. The first is drug pricing. The National Institute for Health and Care Excellence uses an explicit cost-effectiveness threshold, currently about £20,000–30,000 per quality-adjusted life year, to decide which drugs the NHS will fund and at what price. US drug companies see this as a form of price control that holds down returns on medicines for which American patients pay full commercial prices. In December 2025 this moved from risk to reality. As part of a UK-US arrangement giving UK medicines a 0% US tariff for at least three years, the government raised NICE's threshold to £25,000–35,000 per QALY from April 2026, the first change since NICE was set up in 1999, and committed to higher spending on medicines. The deal has been estimated to cost the NHS about £3bn a year, and critics have called for a published impact assessment.6
The second is NHS procurement. US healthcare companies have sought access to NHS service contracts: diagnostics, elective procedures and back-office work. This came up in the 2019 election and was dismissed as scaremongering, but it appeared in formally published US trade negotiating objectives, and the US Trade Representative's 2019 report on trade barriers specifically named NHS pricing as a market-access concern. Any government negotiating with the US needs to say clearly what is and isn't on the table. The medicines arrangement shows why: a change to how the NHS values medicines was agreed as part of a tariff negotiation, not debated as health policy first.
9. What a Good Brexit Looks Like Now: Taking the Pain and Moving On
The pain has been taken. The costs are real and, in the short term, mostly irreversible. What matters now isn't whether Brexit was the right decision (that has been settled democratically, if not intellectually) but what the best available future for British trade looks like from where the country stands in 2025.
From here, a good Brexit isn't a return to the single market, a pretence that CPTPP makes up for what was lost, or an insistence that a WTO no-deal would have been cleaner. It's a clear-eyed strategy built on four facts: what the UK actually exports and where its strengths lie; what the EU relationship can realistically offer under the TCA; what the US relationship can deliver given the imbalance in leverage; and what regulatory freedoms, used ambitiously, might eventually earn to offset the costs.
9.1 Acknowledge the Cost, Then Build From It
A good Brexit starts by facing the numbers. Four per cent of GDP is over £100 billion of output a year that the UK economy isn't producing compared with staying in the single market. It can't be wished away, recast as Project Fear proved right, or offset by pointing at CPTPP. It's the baseline the strategy has to start from, and acknowledging it is a precondition for credibility.
That also means saying who bears the cost, because the 4% falls unevenly. Small exporters that stopped trading with Europe took it directly. Financial firms that moved capital and compliance to Dublin, Amsterdam and Frankfurt took it in how they're organised. Farmers who lost EU market access took it commercially. Workers in industries deeply integrated into EU supply chains took it through job losses and pressure on wages. A good Brexit strategy deals with these groups specifically, with targeted measures for the most exposed sectors and places rather than the general language of Global Britain.
9.2 Make the Most of the TCA: It's a Floor, Not a Ceiling
The TCA is the most underused asset in UK trade policy. It provides the legal framework for a much deeper relationship than exists today, and its text explicitly allows for review and deepening in several areas. The data makes the priorities clear: stable, comprehensive and lasting financial services equivalence; mutual recognition of professional qualifications in architecture, law, accounting and engineering; a protocol for the creative industries and touring; and sanitary and phytosanitary arrangements that reduce border friction for food and farm exports without the UK simply accepting EU rules wholesale.
None of these needs a treaty renegotiation or a referendum. All of them need sustained diplomacy, a willingness to offer the EU something in return, and a political culture that treats trade diplomacy as a commitment spanning several parliaments rather than a talking point for the next news cycle. The UK-EU summit of May 2025 moved in this direction, and that momentum needs to be kept up and built on, not treated as a one-off reset.
9.3 Use the Regulatory Freedom That Brexit Actually Provides
Brexit's real benefit, the one the Leave campaign pointed to but which hasn't yet been realised at scale, is regulatory independence. The UK can now design financial regulation for its own market without agreeing it with 26 other countries. It can approve clinical trials at the MHRA's pace without waiting on the EMA. It can design AI rules that reflect UK priorities instead of EU caution. It can give state aid in forms EU competition rules would have restricted.
A good Brexit uses these freedoms deliberately and ambitiously, as specific, named policy choices with identified beneficiaries rather than abstract claims of sovereignty. Which industries gain from which rule changes? How long before the benefits arrive? How do they compare in size with the costs being paid? Those questions haven't been answered with anything like the rigour that would justify the cost already paid. A good Brexit commits to answering them.
9.4 Build a Services Trade Strategy Around Actual Strengths
Britain's export strengths are in financial services, professional services, the creative industries and higher education. A good Brexit builds its trade strategy around these sectors explicitly, instead of around goods deals better suited to countries with strong manufacturing exports. That means making financial services equivalence the first priority in every significant negotiation, putting digital trade rules in every bilateral agreement, building frameworks that ease short-term professional work across borders, and protecting universities' income from international students, which is tied directly to immigration policy, instead of treating student visas as a way to cut migration numbers.
10. The Way Forward: What a Realistic Trade Policy Looks Like
The Generational Reset doesn't argue for rejoining the EU. The referendum result was a democratic decision, and future UK-EU relations have to be approached from where the UK is now, not where it was before 2016. But good policy has to tell apart the options that are realistic from the ones that are politically comforting and empty.
10.1 The TCA Is a Floor, Not a Ceiling
The Trade and Cooperation Agreement is the legal floor of the UK-EU relationship, not its final form. Several areas are explicitly marked for review, and in practice the relationship is still being negotiated, on financial services equivalence, data adequacy, how the Windsor Framework works and defence cooperation. The UK has more room to deepen its trade with the EU within the TCA than political debate admits, without treaty renegotiation or a referendum. What it takes is sustained diplomacy and a willingness to offer the EU something in return, the same logic as every negotiation the UK says it wants to lead.
10.2 A Services-First Trade Strategy
The UK needs a trade strategy built around its actual economic strengths, which means putting services first: market access for financial services as the main objective in every significant bilateral negotiation; digital trade rules that protect UK technology and creative exports; mobility frameworks that ease the way for consultants, lawyers, architects and other professional exporters; and higher education partnerships that keep the UK a first choice for international students.
It also means being realistic about what goods deals can do for an economy that runs a persistent goods deficit. Tariff cuts on goods help exporters, and the UK exports relatively few goods at scale. A realistic view of a UK-US deal would accept that it would help American farm exporters more than UK goods exporters, while possibly offering real gains in services that negotiations have so far failed to unlock.
10.3 The Geopolitical Dimension
The UK's position is complicated: outside the EU but aligned with it on security and values, close to the US but without a trade deal. The opportunity is to act as a credible bridge: a country that helps US-EU commerce along, hosts financial infrastructure for both, and uses its place in NATO and Five Eyes to anchor a relationship with Washington that goes beyond ordinary commercial bargaining. The risk is trying to be everything to everyone and ending up without enough leverage with any of them.
The UK should pursue a formal UK-EU Services and Investment Framework. That isn't a return to the single market but a structured deepening of the TCA's services provisions, built on stable financial equivalence, mutual recognition of professional qualifications in key sectors, and a digital trade chapter. It can be done within the existing legal framework, needs no referendum, and goes straight at the area where the current arrangement costs most.
11. The Steel Man
The imbalance is real, and it's better to admit it than explain it away. But it reflects an imbalance in the available evidence, not a thumb on the scale. The OBR's cost estimate is a measured result, with a published method and years of post-2021 trade data behind it. What regulatory freedom could deliver is more speculative by nature, for a reason this pillar itself sets out: most of that freedom is unused, by the government's own choice. That's a finding about what has and hasn't been done, not a way of hedging. An accurate account of a lopsided situation looks lopsided. Forcing artificial balance between a measured cost and an undelivered, hypothetical benefit would be the real distortion.
The clearest evidence against a hidden Remain bias is what the pillar actually proposes. It doesn't argue for rejoining the single market or the customs union. Its main recommendation, a UK-EU Services and Investment Framework, deliberately stops short of membership and is built around sectors where the UK has real, proven strength. A pillar quietly arguing to rejoin would centre on regaining what was lost. This one centres on what a mid-sized, services-led economy should do next, on its own terms, from where it stands.
12. Counter-Arguments
'The 4% GDP cost estimate is speculative: nobody can know what would have happened if we had stayed'
The counterfactual problem is real; no economist can run a controlled experiment. But synthetic control studies, such as the Centre for European Reform's10, which compare the UK with a weighted basket of similar economies that didn't go through the same shock, are the most rigorous approach available. The OBR's 4% draws on a range of external studies. Findings from the OBR, the CER and academic researchers using different methods point the same way, which gives reasonable confidence in the direction and rough size of the effect, even if the exact figure is uncertain. Uncertain doesn't mean zero, and the government's own fiscal watchdog stands behind the estimate.
'The UK always traded with the world, and the EU was holding us back from better deals'
The first half is true. The second half needs you to say what the EU was stopping the UK from achieving, and to show those achievements have arrived since leaving. The UK has had full control of its trade policy since 2021. A full US deal hasn't materialised and the 2025 tariff deal is narrow, CPTPP delivers 0.08% of GDP, and the India deal, signed in 2025, took years longer than expected. Post-Brexit experience hasn't borne out the claim that EU membership was the binding constraint on UK trade ambitions.
'Regulatory autonomy will deliver long-run gains that the short-run costs obscure'
This is the strongest argument for Leave's trade agenda, and the Generational Reset takes it seriously. Regulatory freedom is real. The UK has moved faster than the EU on fintech regulation, clinical trial reform and some areas of AI rules, and if those advantages build over decades they could produce real returns. But it's too early to know, and getting the dividend needs a sustained, coherent regulatory strategy, which hasn't consistently been in evidence.
'Geography doesn't matter: we can trade with growing economies further afield'
This may be the most contested claim in the whole Brexit trade debate. The gravity model of trade, one of the most reliable findings in international economics, shows that trade falls with distance, consistently and significantly, even after allowing for every other factor. The EU is 22 miles away across the Channel. A lorry loaded in Birmingham on Monday morning can be in Warsaw by Tuesday. No trade deal with New Zealand, however well designed, changes the physics of geography. A £14 trillion market on Britain's doorstep wasn't a political convenience. It was an economic advantage that no amount of diplomatic creativity can recreate with markets ten times further away.
'Better negotiators would have got better deals'
Negotiating leverage doesn't come from determination. It comes from what you have to offer and how much the other side needs it. The UK can't negotiate its way to US financial services access if the American mandate doesn't include it, and better ministers wouldn't change the US farm lobby's influence in Congress. The answer to the leverage problem is to build the economic strengths that create real leverage, not to suggest that different personalities would have got different results from the same position.
Cross-Pillar Dependencies
| Pillar | Connection |
|---|---|
| Economy | The UK's goods deficit and its strength in services exports reflect the economic weaknesses the Economy pillar diagnoses: underinvestment in productive capacity, the decline of manufacturing, and high-value activity concentrated in a few regions. Trade policy can't make up for a weak economy; it can only work with the strengths that exist. |
| Immigration | Free movement was the single market's most politically contested feature and its most important for services trade. UK professionals losing the right to work freely across the EU is friction in services trade; the loss of EU workers in farming and food processing is friction in goods supply chains. The immigration debate and the trade debate are the same debate about the single market, separated for political convenience. |
| Energy | The TCA did too little on UK-EU energy market integration, such as shared interconnectors and carbon market alignment. The UK's exit from the EU Emissions Trading Scheme, and its replacement with a domestic scheme, creates complications with carbon border adjustments that grow more costly as the EU's CBAM is phased in. |
| AI | Digital trade rules on data flows, intellectual property and cross-border AI services are the frontier of trade policy for a services-led economy. Leaving the EU's digital single market created data adequacy requirements, settled in the TCA but subject to review. UK AI services exported to the EU face a patchwork of national rules instead of the single framework membership would have provided. |
| Political Renewal | The trade policy failures described here (the stalled US deal, the thin CPTPP gains, the unaddressed services gap with the EU) are partly the result of a political system that rewards announcements over delivery, can't sustain a negotiating strategy across several parliaments, and has treated trade policy as messaging rather than strategy. |
| Economic Renewal | A UK with a more productive, less financialised economy and a sturdy domestic tax base has more real leverage in trade talks. The sovereign wealth fund proposed in the Economic Renewal pillar could anchor long-term investment in export capability, particularly in services, technology and high-value manufacturing, which any trade strategy depends on. |
| Defence | The UK's biggest unused trade asset is its defence and security relationship with the US and Europe. A deeper UK-US defence industrial partnership builds the government and commercial relationships in which progress on trade is most likely. Defence cooperation is security policy and trade policy at once. |
14. Proposals for Change
The proposals below are this pillar's evidence-based recommendations, put forward for public discussion and challenge.
Accurate Accounting: The Starting Point
-
P1 Require the OBR to publish an annual Trade Impact Assessment measuring the effects of post-Brexit trade arrangements on UK GDP, sectoral output, foreign direct investment and business investment, so that independent, checkable measurement replaces political assertion.
-
P1 Publish a full public account of the economic gains and costs of every significant trade agreement concluded or under negotiation, using a consistent method and including an analysis of who bears the costs and who gets the benefits.
-
Stop presenting 15-year GDP estimates for trade deals without also showing how they compare with the costs already paid for leaving the single market. The public deserves the whole ledger, not selected lines from it.
Standards: Protect What the Single Market Provided
-
P2 Put into primary legislation the commitment that UK food safety standards won't be lowered as part of any trade agreement. That makes food standards a matter of domestic law instead of ministerial discretion, and takes them out of any trade negotiating mandate unless Parliament explicitly agrees.
-
P3 Publish the full UK negotiating mandate for any trade deal in which NHS drug pricing, NHS procurement access or NICE's methods are relevant to the other side's stated objectives, before negotiations conclude, not after. The public has a right to know what is being offered in its name.
-
Commission an independent assessment of what diverging from EU standards means for consumer protection: where UK standards have diverged since Brexit, whether that helps or harms UK consumers, and what it means for exporters who must still meet EU standards anyway.
The EU Relationship: Deepen What Exists
-
Make a UK-EU Services and Investment Framework the main diplomatic trade objective, covering stable, lasting financial services equivalence; mutual recognition of professional qualifications in architecture, law, accounting and engineering; and a creative industries protocol that removes the carnet and work permit requirements now holding the sector back.
-
Negotiate UK association with the EU Emissions Trading Scheme, or full alignment of the two carbon markets, to remove the carbon border adjustment friction that grows as the EU's CBAM is phased in.
-
Extend UK participation in EU research programmes beyond Horizon to other areas where UK science and industry make a net contribution to both sides.
Services Trade: Build on Real Strengths
-
P5 Set up a Services Export Strategy with binding targets for financial services, professional services, the creative industries and higher education, the sectors where the UK has a real competitive advantage, instead of a trade policy centred on goods tariffs, where the UK's position is weaker.
-
Negotiate digital trade chapters in every future bilateral agreement, with stable provisions for data flows, protections for AI services exports, and intellectual property rules suited to an economy that exports creative work and technology.
-
Create a Professional Mobility Framework with key partner countries, giving simpler routes for short-term cross-border professional work and removing immigration friction from brief professional assignments.
The US Relationship: Realism Over Rhetoric
-
P6 Commission and publish an independent assessment of what a UK-US trade deal could realistically include: what the US is actually willing to offer on financial services and digital trade, what the UK would have to concede on farming and food standards to get it, and whether the achievable deal would be good for the UK economy given what it actually exports.
-
P6 Pursue the US relationship mainly through defence industrial cooperation and the intelligence partnership. That builds the government and commercial relationships in which trade progress is most likely, instead of treating trade talks as a separate track cut off from the security relationship that gives the UK its main leverage.
15. A Note on Tariff Exposure: What Happens When a Large Economy Acts Alone
This pillar has argued throughout that trade leverage comes from market size, and that the UK negotiating alone as about 3.4% of the world economy is in a weaker position than it was as part of a bloc of 18%. The Trump tariffs of 2025–26 demonstrate the point live, and show what lack of leverage looks like in practice.
In April 2025 the United States imposed a baseline 10% tariff on all UK goods, on top of existing 25% tariffs on steel and aluminium. The UK's response showed the leverage problem with uncomfortable precision. The government won a partial exemption, a quota system for steel and aluminium, but accepted the 10% baseline on everything else. It couldn't credibly threaten to retaliate: its goods imports from the US are smaller than its exports, and a tariff war would hurt UK businesses more than American ones. The deal announced in May 2025 cut some sector tariffs in return for preferential access for American beef, the very farm concession that had stalled the wider US trade deal for five years, extracted under pressure.
The EU's response to the same tariffs was very different. It threatened immediate, calibrated retaliation on $95 billion of American goods, aimed at politically sensitive sectors in swing states and drawn up by trade lawyers with decades of WTO litigation behind them. In fairness to the other side of the argument, scale didn't spare the EU either. Its July 2025 deal with the US accepted a 15% US tariff on most EU goods, higher than the UK's 10%, along with commitments to buy American energy. The EU could credibly threaten retaliation and the UK couldn't, but in the end both accepted terms set largely in Washington. What scale buys is the ability to push back; it doesn't guarantee a better outcome against a counterpart willing to use tariffs.
This isn't a hypothetical about future trade relationships. It's what has happened when the UK negotiated without the EU's scale behind it. The Leave campaign promised independence would let Britain set its own terms with the world. The Trump tariffs show what "our own terms" means for a mid-sized economy outside a bloc: accepting terms set by bigger players, with little recourse, and making concessions under pressure that a stronger position wouldn't have needed.
There's a further side to the tariff episode that has had almost no public attention. The beef concession of May 2025 matters in itself: farm access refused through five years of formal talks was obtained through tariff pressure in weeks. But it matters just as much as a signal. Under tariff pressure, the UK showed it will concede rather than bear the cost of holding firm, and every future negotiating partner can now see that, including the US pharmaceutical industry.
This pillar has already set out that US drug companies have a long-standing, formally stated aim in any UK-US deal: changes to the NICE cost-effectiveness threshold that decides which drugs the NHS funds and at what price. The US Trade Representative's 2019 National Trade Estimate Report named NHS pricing explicitly as a market-access barrier. That change wasn't won in formal trade talks either. It came in December 2025, when the UK raised the threshold from £20,000–30,000 to £25,000–35,000 per quality-adjusted life year as part of an arrangement that spared UK medicines from US tariffs.6
Earlier versions of this pillar warned that the pressure that won beef access would be used on NICE next. That is what happened. There's no conspiracy in it; it's the logic of negotiating in sequence with a much more powerful counterpart. A country that gives way under pressure on one issue shows that pressure works. The UK's ability to resist the next demand depends on the same thing its ability to resist the tariffs depended on: leverage it doesn't currently have.
Sources: OBR Economic and Fiscal Outlook March 2025; OBR Brexit Analysis 2023; Centre for European Reform, Brexit Cost Tracker 2024 and Perfect Storm 2025; Resolution Foundation, Living Standards Outlook 2024; ONS Trade in Goods and Services 2024; HMRC Trade Statistics 2024; HM Government, CPTPP Impact Assessment 2023; UK in a Changing Europe, The Economic Impact of Brexit 2024; TheCityUK, Key Facts about UK Financial and Related Professional Services 2024; House of Commons Library, Statistics on UK Trade with the EU 2025; DBTIS, US Trade and Investment Factsheet 2026; US Trade Representative, 2019 National Trade Estimate Report.
The Generational Reset is a non-partisan, public-interest project. Not affiliated with any political party. | generationalreset.org
The Generational Reset | S4_04: Trade & Global Britain | For public discussion. Not affiliated with any political party. | generationalreset.org