This document sits in Section Three, The Wider Conversation. Energy policy involves contested questions about economics, timescales and trade-offs on which reasonable people disagree. The Generational Reset sets out the strongest arguments on all sides, including steel man cases for positions it ends up challenging, and bases every conclusion on evidence rather than ideology.
Executive Summary
The UK energy system has a basic flaw: much of the electricity consumers buy is priced as if it came from gas, even when 70% of the grid is running on renewables with almost no fuel cost.1 Under marginal pricing, the most expensive generator needed at any moment sets the price for all of them. That turns a gas supply crisis into an electricity pricing crisis, and gives generators that are not on fixed-price contracts a windfall from the clean energy transition.
This pillar makes four arguments. First, the wholesale electricity market needs reform, not for ideological reasons but because its current design overcharges consumers for renewable power they are already paying to build. Second, the North Sea debate, usually framed as immediate closure against unlimited expansion, misrepresents what the evidence supports: strict fiscal discipline on existing fields, no new exploration that needs public money, and a funded transition for workers. Third, the delay in the clean energy transition is mainly political, not technical or economic. The technology exists and keeps getting cheaper; the delay has been driven by lobbying interests with a documented financial stake in it. Fourth, conflicts of interest in energy policy, the same problem the Public Office Covenant addresses, are the main reason policy has consistently served established companies rather than citizens.
The barriers to a better energy system are not technical. The technology exists, and the economics increasingly favour the transition. The barriers are political: markets built for the old world, a planning system that cannot move fast enough, and a lobbying machine that has delayed action for three decades.
Key Proposals
Reform the wholesale electricity market to decouple consumer prices from gas. A transition timetable protecting existing investment contracts, extending Contracts for Difference to legacy generation.See how Budget 2026 relates to this
Mandate Vehicle-to-Grid ready standards for all new EVs from 2027. Standardised communication protocols and smart tariff infrastructure.
Maximise North Sea revenue under strict fiscal discipline. No additional public co-investment or tax relief, cash decommissioning security at licence transfer to sub-investment-grade buyers, and no new exploration licences requiring subsidy to be viable.
Fund a fully costed Just Transition plan. Financed from a ring-fenced levy on current production revenues, with specific retraining pathways into offshore wind, CCS, and hydrogen.
Fix the grid connection queue. Binding connection timelines backed by regulatory consequences for Ofgem.
Invest in long-duration storage and reform the capacity market. Enough storage to cover multi-day low-wind, low-solar periods without gas backup, with firm backup power priced at its genuine long-run cost.
1. How Electricity Is Priced, and Why It Fails Consumers
1.1 The Marginal Pricing Problem
The UK uses marginal pricing, also called the merit order. Generators bid into the market, and all of them are paid the price set by the most expensive one needed to meet demand at that moment. That generator is almost always a gas plant. So even when 70% of the grid is running on wind with no fuel cost, generators selling at the market price are paid the gas price. Wind farms on fixed-price Contracts for Difference pay the excess back, but older generators on the Renewables Obligation, and nuclear plants selling at market prices, keep it as a windfall. Consumers pay as if the grid ran on gas.
The 2022 energy crisis showed this with brutal clarity. Wholesale gas prices spiked, and marginal pricing spread that spike across every unit of electricity on the grid, including the large share from renewables with no fuel cost. The price cap for a typical household reached £4,279 a year in early 2023; the government's Energy Price Guarantee held actual bills to about £2,500, paid for by taxpayers.2 Oil and gas companies made extraordinary profits while households were at their most exposed. The system turned a gas supply crisis into an electricity pricing crisis, by design.
1.2 The Real Cost of Generation
The table below shows the levelised cost of electricity for each type of generation: what it costs to build and run each technology per unit of output. Sources: DESNZ, Arup research4, and CfD auction results (2025)5. These figures do not include grid connection, transmission, balancing, or the system cost of intermittent supply.
View underlying data as a table
| Source | Low p/kWh | High p/kWh | Key note |
|---|---|---|---|
| Onshore Wind | 4.0p | 5.5p | Cheapest source. Recent auction contracts at ~7p because of real-world build costs. |
| Solar PV (utility) | 4.0p | 5.5p | Very cheap globally. UK sunshine limits output compared with southern Europe. |
| Offshore Wind (fixed) | 5.5p | 9.5p | Real-world ~8.9p/kWh. Grid connection adds ~2p. Core of the UK clean energy strategy. |
| Offshore Wind (float) | 12p | 18p | Early-stage, for deep waters. Costs expected to fall through the 2030s. |
| Gas CCGT (unabated) | 9p | 14p | Sets the marginal price for the whole grid, which is the heart of the bill problem. |
| Nuclear (large, new) | 9.3p | 16p+ | Hinkley C strike price now worth ~13–15p with inflation. Firm, always on. |
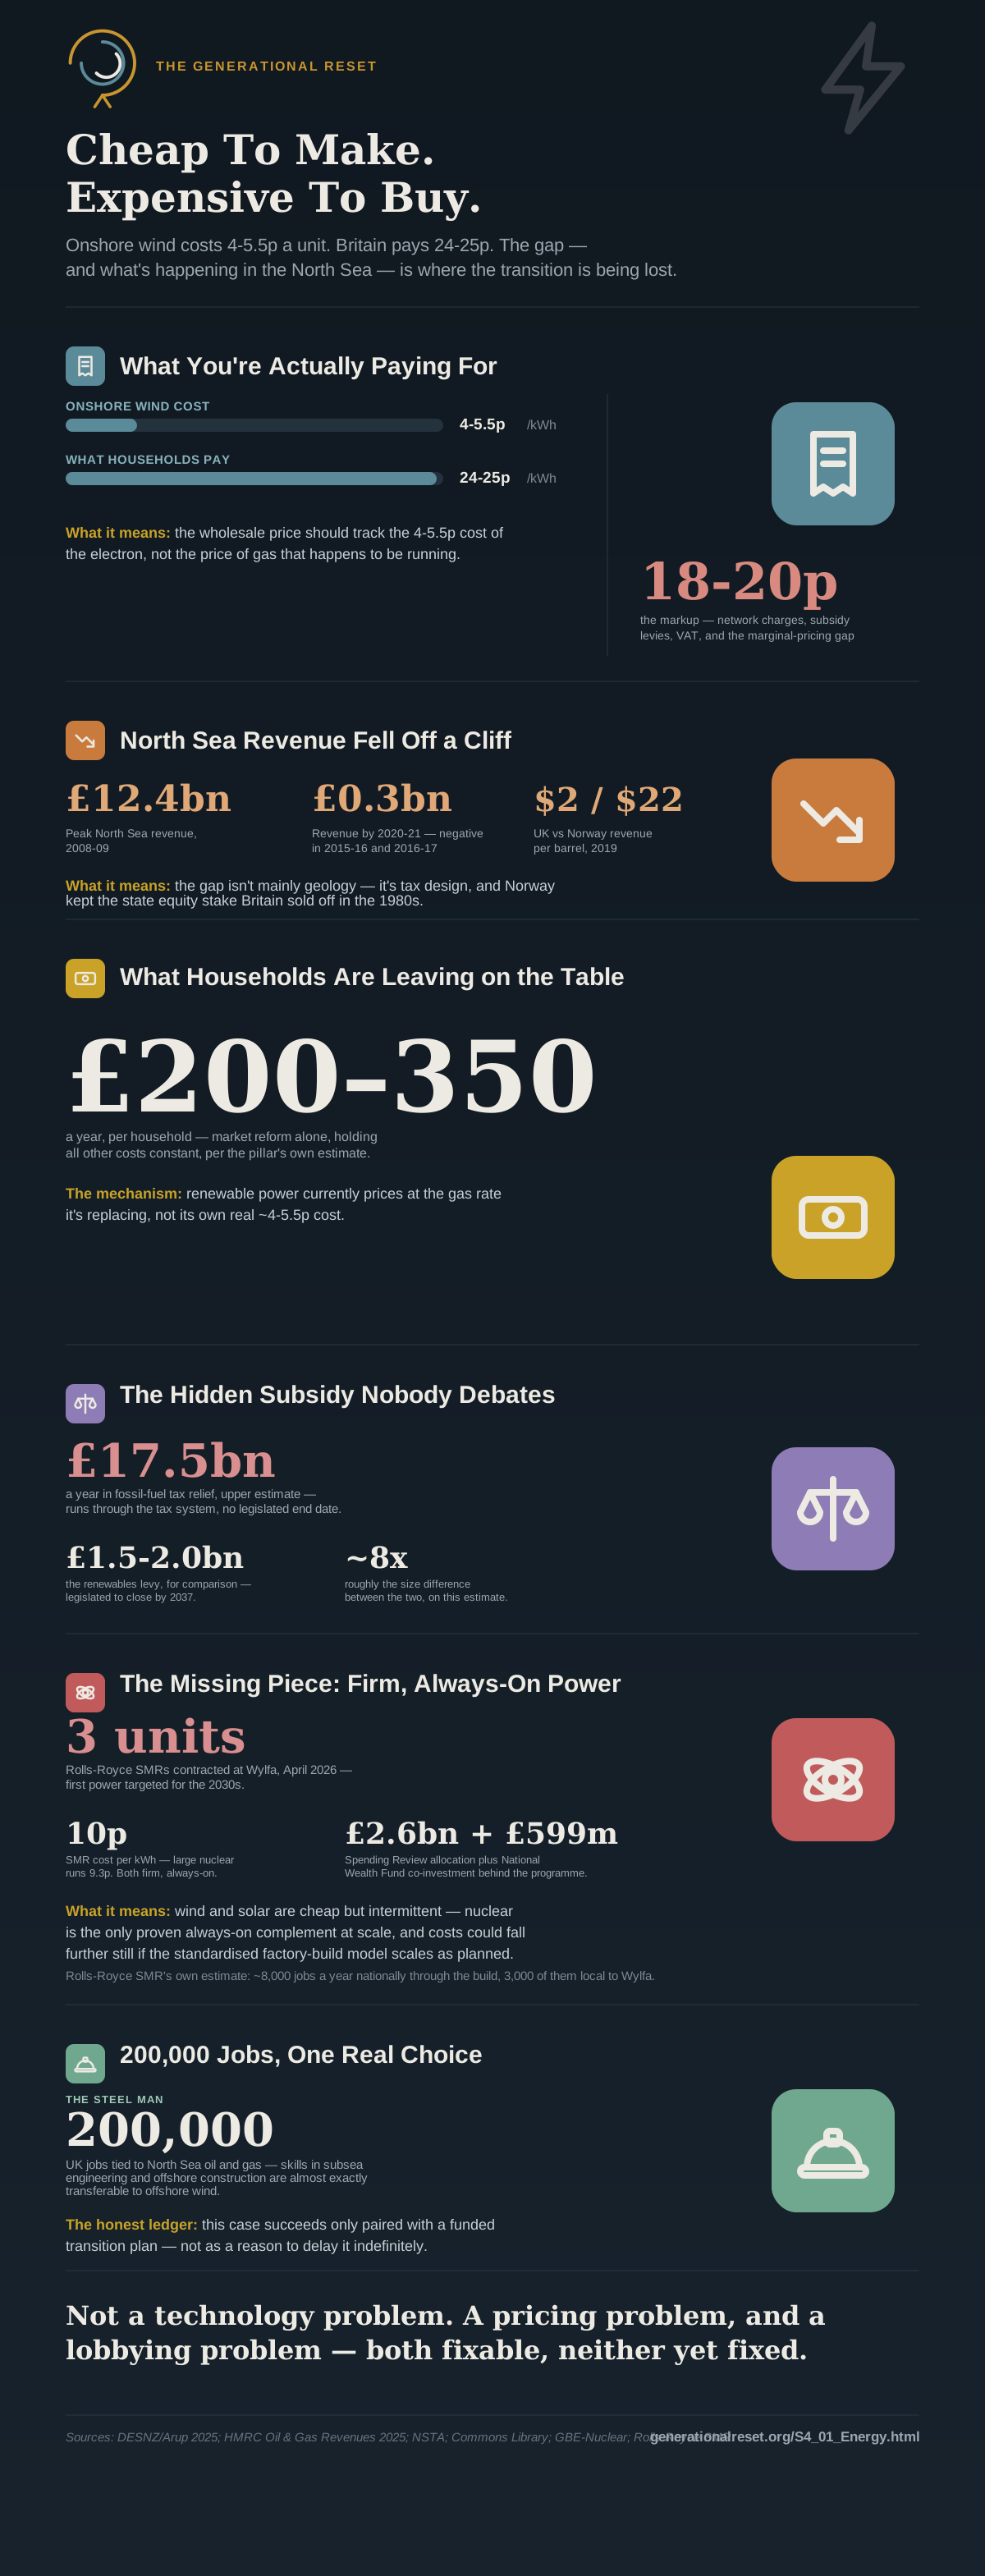
| Nuclear (SMR) | 10p | 20p | First units contracted at Wylfa (2026). Costs are uncertain before series production, and could fall sharply if standardised factory building works as projected. |
| Battery storage (4hr) | 8p | 12p | Cost of adding storage, not generation. Falling fast. Vehicle-to-grid could change this. |
1.3 The Case for Market Reform
There are three main reform options. One is a split market, in which renewables and nuclear trade at their actual cost and gas only tops up what is needed, priced accordingly. Another is zonal pricing, with regional prices reflecting local supply and demand. The third is to extend Contracts for Difference so that more generation is insulated from gas prices. The obstacle is commercial and political, not technical. Existing generators built their business models around the current system, and any reform has transition costs. But the long-run arithmetic is clear: a grid priced at the real cost of renewables with no fuel cost will be permanently cheaper for consumers than one tied to gas.
Reform the wholesale electricity market so that consumer prices no longer follow marginal gas prices, with a clear transition timetable that protects existing investment contracts while ending the windfall for generators with no fuel cost.
Under marginal pricing, generators selling at market prices are paid the price set by the most expensive one needed at any moment, almost always gas, even in hours when 70% of the grid runs on renewables with no fuel cost.1 Onshore wind generates at 4–5.5p/kWh; households pay about 26p/kWh. Market reform alone is estimated to cut the wholesale part of bills by £200–350 per household per year. Against that, GB balancing costs were £2.7bn in 2024/25 and are forecast to reach £6.4–8.3bn by 2030 without faster transmission investment, with transmission constraints already 71% of the total.6
Marginal pricing transfers value from consumers to generators selling at the gas-set price, whatever generation actually costs. This connecting argument is the project's own, built on the mechanism and cost data above; no single source states it. But removing that distortion and consumers seeing lower bills are not automatically the same thing. If the grid investment gap behind rising balancing costs is not closed as fast as market reform proceeds, the saving reform is meant to deliver could simply reappear as a different line on the same bill.
This section already names three different reform paths, none of them a straw man: a split market, in which renewables and nuclear trade at actual cost and gas only tops up what is needed; zonal pricing, with regional prices reflecting local supply and demand; or extending Contracts for Difference to older generation, gradually insulating more of the grid from gas prices. This pillar proposes the third.
Choosing extended CfDs over a full split market or zonal pricing is a value judgement the evidence alone does not settle. It puts protecting existing investment contracts, and a faster, simpler transition, ahead of the possibly larger but riskier and slower restructuring the other two would need. Zonal pricing in particular would create explicit regional winners and losers, a question of redistribution this pillar does not resolve, which extended CfDs avoid by design. A reader who values a cleaner, faster full restructuring above transition stability and investor confidence is not wrong on the evidence. They are weighing the same facts against a different value.
Reform the wholesale electricity market so consumer prices no longer follow marginal gas prices, extending Contracts for Difference to older generation on a timetable that protects existing investment contracts. The falsification test below sets out what would show that this particular path, not market reform in general, is failing to deliver the promised saving.
1.4 The Subsidy Picture: Both Sides of the Ledger
Public debate about energy subsidy usually comes down to two slogans, "renewables are propped up by subsidy" and "fossil fuels get the real subsidy", each used selectively. Government support for energy actually flows through at least three different routes that are rarely set side by side.
Direct government spending, roughly £35bn a year on the Public Spending Overview's "Energy & net zero" line, covers energy price support (including the 2022–23 crisis support), grid investment, and nuclear co-investment such as the Wylfa SMR programme. This is money the government spends, and it appears in departmental budgets.
Levy-funded support for renewables and low-carbon power (the Renewables Obligation, Contracts for Difference and Feed-in Tariffs) works differently. It has mostly been paid through charges added to energy bills rather than from general taxation. The OBR counts these "environmental levies" as tax receipts, and they came to about £14bn in 2025-26, most of it from these three schemes.7 This is the subsidy renewables' critics usually mean, and it is large: comparable to the top of the fossil fuel range below, and well above the bottom. From April 2026 to 2029, the government is paying 75% of the Renewables Obligation's cost on household bills from general taxation, about £2.3bn a year, which moves part of it from bills to taxpayers rather than shrinking it.8 The Renewables Obligation closed to new projects in 2017 and its payments end in 2037; CfDs run for fixed terms and pay money back when market prices are high, as they did in 2022.
Tax-side support for fossil fuels (decommissioning tax relief, investment allowances and similar reliefs) is not spending at all. It is revenue the Exchequer chooses not to collect. Because it never appears as a spending line, it is easy to miss, which is part of why the public debate is so lopsided. Estimates range from £3.5bn to £17.5bn a year depending on method: the low end counts only the narrowest direct reliefs, while the high end follows the OECD/IMF convention of counting wider implicit support. Unlike the Renewables Obligation, it has no end date.
The width of that range needs explaining. North Sea oil and gas production is taxed at a combined marginal rate of about 78% (ring-fenced corporation tax, the supplementary charge and the Energy Profits Levy together). The investment allowances that bring the effective rate down exist because a 78% marginal rate would otherwise stop almost all new investment, not because producers are lightly taxed in absolute terms. That is the low end of the range. The high end is driven largely by something else: the IMF/OECD convention of counting the UK's reduced 5% VAT rate on household gas and electricity, support that goes to households rather than producers, as an implicit fossil fuel subsidy. The two ends of the £3.5–17.5bn range mostly measure different things rather than disagreeing about the same thing. The full reasoning and sources are in the Net Zero working paper.
2. The North Sea: What the Evidence Supports
The North Sea debate is usually framed as immediate closure against unlimited expansion. The evidence supports neither. The defensible position is more specific, and more uncomfortable for both sides.
2.1 The Steel Man for Continued Production
Seven arguments are made for continuing North Sea production. The strongest is about jobs and skills: about 200,000 UK jobs are directly or indirectly tied to North Sea oil and gas9, concentrated in Aberdeen and north-east Scotland, with skills (subsea engineering, offshore construction, pipeline installation) that transfer almost exactly to offshore wind, carbon capture and hydrogen. This is a real case for managed decline with an explicit, funded transition plan, not for open-ended expansion.
The tax revenue argument matters but needs close examination. Net North Sea tax revenue fell from £12.4 billion in 2008-09 to just £0.3 billion in 2020-21, and was negative in 2015-16 and 2016-17. In 2019 the UK received less than $2 per barrel in revenue, against Norway's $22 from the same waters. In the years before the 2022 crisis, roughly half of all North Sea tax revenue went straight back out in relief payments. HMRC estimates that tax relief on future decommissioning will cost the Exchequer £11.7 billion in present value terms: £5.8 billion in tax repaid to companies and £5.9 billion in ring-fence corporation tax that will no longer be collected.10 That is a discounted figure for the relief alone. The spending it relates to is the NSTA's central estimate of £44 billion (2024 prices) for total industry decommissioning costs from 2025 onwards11, so the two numbers measure different things and should not be divided into each other to produce a "taxpayer share".
2.2 Geology or Policy? What the UK–Norway Gap Shows
A common explanation for why Norway captures so much more value from North Sea oil than the UK is that Norway's geology is easier: bigger fields, cheaper to reach. There is a real geological story, but on the evidence it explains less of the gap than it is usually given credit for.
The real part: the UK sector of the North Sea is older and more depleted than at its 1980s–90s peak, and the fields still being worked are on average smaller and more technically complex than the giant fields that drove peak production. The North Sea Transition Authority's benchmarking shows the average cost of producing a barrel of oil equivalent on the UK Continental Shelf rose from £13.82 in 2020 to £19.49 in 2024.12 That is a real and worsening cost problem, and it is the government's own reason for one of the most generous investment allowances of any oil and gas tax regime in the world, with relief reported as high as 91p for every £1 a company invests.13
What geology does not explain is the size of the gap with Norway. Since 1970 the UK government has captured roughly $11 in revenue per barrel produced; the Norwegian government has captured close to $30. That is a gap of roughly $19 a barrel, across five decades of production from the same basin.14 Analysis of the gap attributes most of it to two things, neither of them geology: a higher tax take, and the Norwegian state's direct ownership stake in its own oil and gas fields, through its State's Direct Financial Interest and the majority-owned Equinor, which earns dividends on top of tax. The UK government has no real equivalent.14 Norway extracts from the same basin, with plenty of its own small, mature, technically difficult fields, and still captures roughly three times the UK's revenue per barrel.
Norway did not think of something Britain never had access to. Britain had the same tool and gave it up. In 1975–76 the government created the British National Oil Corporation to give the state a direct ownership stake in North Sea proceeds, the same role Norway's Statoil, founded a few years earlier, was built to play. In the same period the state also held a majority stake in BP: 51% in 1977. Both were sold during the 1980s. BNOC's upstream assets were floated as Britoil in 1982 and 1985, BP was fully privatised by 1987, and Britoil was absorbed into the now fully private BP in 1988.15 Norway kept its equivalent and built on it. Britain sold its equivalent to the company that went on to become the dominant private operator of the same fields.
That history changes what "the industry needs subsidy to operate" means in practice. When BP and Shell, the two largest private operators in the basin (BP itself once majority state-owned), responded to the 2022 windfall tax, neither argued that the fields had become geologically unworkable. BP said it would have to review its planned £18 billion of UK investment because of the levy; Shell said its £20–25 billion UK investment plan over the decade depended on the investment allowance built into the same measure.16 Both companies have produced profitably from this basin for decades under a lighter tax regime than Norway's. What they were signalling is that they will not accept Norwegian-level tax without Norwegian-level relief to soften it. That is a negotiating position from companies working a resource the state once had a direct stake in and chose to sell, not a geological constraint. Hence the policy position below: continued production on ordinary commercial terms is welcome, but the evidence does not support further public subsidy for production that is only profitable with it.
None of this means the answer is to rebuild a British Statoil now. That option was open in the 1970s, when BNOC was created alongside a state stake in BP and the basin was heading toward peak production. Today is very different. The basin has been worked down to smaller, costlier, more marginal fields, so a new state operator would be buying into the tail of the resource, not its peak, just when the country needs to move North Sea capital and skills into clean energy rather than commit fresh public money to extending fossil fuel production. The BNOC history matters for understanding how the UK ended up with a weaker hand than Norway, and for showing that "we could never have done this" is not true. It does not change what to do now, which is the position set out below: manage what remains under strict fiscal discipline, fund the transition, and stop treating further public subsidy as the only way to keep production going.
2.3 Who Pays When a Field Closes
The legal chain of liability. Under section 29 of the Petroleum Act 1998, the Secretary of State can require a decommissioning programme from the operator, licensees, joint-venture partners, owners of the installation, and their associated and parent companies.17 Everyone served is jointly and severally liable, so any one of them can be made to pay the whole cost, and the liability continues after they sell. Section 34 goes further, letting the Secretary of State pursue former owners who were never served a notice. Notices can be withdrawn when a company sells out, but in practice this rarely happens.
The order of recourse is therefore current owners, then their partners, then previous owners and their parent companies, and only then the state. The National Audit Office found in 2019 that 80% of UK assets were, or had been, owned by large operators, and on that basis the government rated the risk of taxpayers paying for a default as low.18
What taxpayers pay anyway. Decommissioning costs are relieved against ring-fence corporation tax (30%) and the supplementary charge (10%), so about 40p of every pound spent comes back to the company.19 Fields that paid Petroleum Revenue Tax get more, because decommissioning losses can be carried back against PRT paid years or decades earlier. The Energy Profits Levy gives no deduction for decommissioning.
The guarantee contracts. Since 2013 the government has signed Decommissioning Relief Deeds, contracts that guarantee companies the tax relief they expect; 109 were in force at the end of 2024-25. By then the Treasury had made 24 payments under them, totalling about £355 million, and had set aside a further £133 million for costs arising from companies that have defaulted, most of it expected within five years.20 This is where default risk actually reaches the public purse.
The delay problem. In April 2026 the NSTA fined EnQuest Heather £16.5 million, £500,000 for each of 33 wells left unplugged for five to six years after production stopped, finding that the company had "pursued a conscious strategy to defer the costs". EnQuest disputes the finding and has said it may appeal.21 The NSTA's 2025 update shows more than 500 wells in the plugging backlog, and total cost estimates up 11% on the 2022 baseline, against a target of a 10% reduction by 2028.11
2.4 What the Evidence Supports
Taking all the arguments together, the evidence does not support "stop everything now". It supports four things. Maximise revenue from existing fields under strict, enforced fiscal discipline, with no additional public co-investment or relief. Require decommissioning security in cash or near-cash, held in an independent trust and calculated on the full pre-tax cost rather than the post-tax cost, as a condition of every licence transfer to a company below investment grade. Approve no new exploration licences that need public co-investment or extra tax relief to be commercially viable. And fund a fully costed Just Transition programme from a ring-fenced levy on current production revenue.
The current system relies on letters of credit and parent company guarantees, which are only as good as the company behind them: acceptable for a major, weak for a thinly capitalised buyer. Applying the cash requirement only when assets transfer to companies below investment grade targets the risk without penalising well-capitalised owners. If, five years after it is introduced, guarantee payouts for defaulted obligations have not fallen below the current £133 million provision, or sales of late-life assets have fallen by more than the number of early closures avoided, the proposal has failed and should be revisited.
3. Lobbying, Vested Interests and Democratic Accountability
The technology for a much cleaner UK grid has existed for decades. The delay in deploying it at scale is mainly political, not technical or economic, and how it happened is documented. ExxonMobil's own scientists understood the mechanics of climate change from the 1970s.24 The corporate response was to fund doubt, the same playbook the tobacco industry used. You do not need to win the scientific argument; you only need to keep it looking unsettled long enough to delay regulation.
In the UK, the oil and gas industry has spent millions a year on direct lobbying, with access to ministers that environmental groups cannot match, and the revolving door between government energy departments and the industry is well recorded. 2022 was a revealing test. The case for speeding up the clean transition had never been stronger; it was visible on every household's energy bill. Yet the policy response included approving new North Sea licences. The lobbying machine was strong enough to turn a crisis caused by dependence on fossil fuels into a public argument for more of them.
The deeper problem goes beyond individual corruption. Most politicians are not corrupt in a simple transactional sense; the system creates conflicts of interest that produce bad outcomes without any explicit exchange. A minister who holds shares in an oil company, whose party has taken donations from one, or who plans to join an industry board after leaving office does not need to be bribed to make decisions that happen to suit fossil fuel interests. The bias is there before they walk into the room.
4. The Way Forward
4.1 Immediate Priorities (2025-2030)
-
Reform the wholesale electricity market so consumer prices no longer follow marginal gas prices, protecting existing investment contracts while ending the windfall for generators with no fuel cost.
-
P5 Speed up planning approvals for renewables, tackle the grid connection queue that is delaying projects by years, and set binding connection timelines backed by regulatory consequences.
-
P2 Require all new EVs sold in the UK from 2027 to be ready for vehicle-to-grid, with standard protocols, smart tariff infrastructure, and minimum battery-charge protections for drivers.
-
Require decommissioning security in cash or near-cash, held in an independent trust, as a condition of every North Sea licence transfer to a company below investment grade, calculated on the full pre-tax cost and not reliant on the company's future solvency.
-
P4 Publish and fund a fully costed Just Transition plan for North Sea workers, paid for by a ring-fenced levy on current production revenue, with specific retraining routes into offshore wind, CCS and hydrogen.
-
Require full lobbying transparency for energy policy: all ministerial meetings, submissions and material financial interests published within 30 days.
4.2 Medium Term (2030-2040)
-
Achieve a grid where gas is a minor, occasional backup rather than the price-setter, through continued renewable buildout, storage and completed market reform.
-
Deliver the Wylfa SMR programme (three Rolls-Royce units contracted under GBE-N in April 2026, backed by a £2.6bn Spending Review allocation and up to £599m from the National Wealth Fund) under a financing model that does not need consumer-funded risk subsidy on the scale of Hinkley Point C. The NWF's role here is catalytic co-investment, not the sovereign wealth model proposed elsewhere in the Generational Reset.
-
P6 Build enough long-duration storage to cover several days of low wind and low sun without gas backup.
-
Complete the phased decommissioning of North Sea infrastructure under a regulated programme with full public accountability for costs.
4.3 What Success Looks Like
The test of this framework is not whether it satisfies ideological positions on either side but whether it delivers measurable results for citizens: a lasting fall in the wholesale part of electricity bills as gas is displaced; real independence from volatile global fossil fuel markets through domestic renewables; a funded, specific, time-limited transition programme for North Sea communities and workers; and energy policy made in the public interest, with conflicts of interest visible and accountable.
5. Counter-Arguments
'Decoupling consumer prices from the marginal cost of gas removes the price signal that currently pays for the flexible backup power the grid still needs on low-wind, low-solar days'
Decoupling the retail price from gas's marginal cost does not remove gas's cost signal from the system. It moves that signal into a mechanism built for the job. Proposal 6 reforms the capacity market to pay for firm backup power at its real long-run cost, and invests in long-duration storage to cover several days of low wind and sun directly. Reliability is paid for through a market designed to value it, instead of being folded into the price of every unit a consumer buys, whether it came from wind or gas.
'Blaming three decades of delay on lobbying lets ordinary local opposition off the hook: pylons, objections to onshore wind and resistance to EV mandates have slowed things too'
Local resistance is real, and this pillar's own proposals deal with it: fixing the grid connection queue and its planning barriers is Proposal 5. But local planning friction explains delays of a few years on particular projects. It does not explain a policy response that favoured fossil fuels in a crisis caused by dependence on them, which is what 2022 showed: the case for speeding up the transition had never been stronger, visible on every household's bill, and the response included approving new North Sea licences. That is the mark of organised interests capturing policy, traceable back to ExxonMobil's own scientists understanding climate change in the 1970s and the manufactured doubt that followed, not of scattered local planning objections.
'Ruling out new North Sea exploration that needs public money swaps a climate problem for an energy security problem: less domestic production means more reliance on imported gas just when supply security matters most'
UK North Sea gas is sold into an international market at the global price, not kept for UK consumers at a domestic discount. Under the current market design, more domestic production does not by itself protect British households from a global gas price shock; that is exactly how the 2022 supply shock became a UK-wide price crisis, however much gas came from the North Sea. The proposal also does not end North Sea production: existing fields keep producing as much as possible under fiscal discipline. What stops is new exploration that needs public subsidy to be commercially viable, which is production the market has already judged not worth paying for on ordinary terms.
Cross-Pillar Dependencies
| Pillar | Connection |
|---|---|
| Economy | The clean energy industrial strategy links directly to the Economy pillar. The North Sea's skilled energy workforce, whose skills transfer directly to offshore wind and subsea work, is the human capital that bridges the transition. The Economy pillar's clean energy industrial strategy must deliver jobs and regional development in the coastal communities next to offshore fields. |
| Public Office Covenant | Financial interests in fossil fuels and energy among the people setting North Sea licensing, windfall tax and transition policy are conflicts of interest that the Covenant's disclosure rules address directly. Full financial disclosure, cooling-off periods and lobbying registers change the conditions these conflicts operate in. |
| Political Renewal | Long-term energy decisions, from the North Sea transition to grid investment and offshore wind industrial strategy, need political commitment beyond the five-year cycle. The independent mandates that protect these investments from reversal after elections are more credible when the political system itself rewards longer time horizons. |
| NHS | The NHS estate is one of the largest energy users in the public sector. Energy efficiency investment in NHS buildings links the net zero programme to cutting both the NHS maintenance backlog and its running costs. |
| Welfare | Fuel poverty affects 2.36 million households in England on the official measure (2025), and more on campaigners' wider measures,25 a welfare cost driven by energy prices and poorly insulated homes. The retrofit and grid investment proposed here would directly reduce welfare costs. Cold, damp homes are a health cost, a welfare cost and an energy cost at once. |
| Housing | NHC homes should meet or beat the Future Homes Standard for energy efficiency. Retrofitting social housing links housing quality to reducing fuel poverty and NHS demand. New social housing is a chance to build energy efficiency in from the start, which is much cheaper than retrofitting later. |
| Public Debt | The Sovereign Wealth Mechanism's main funding sources include commodity and windfall revenue. The tax regime for new North Sea licences should include a contribution to the SWM as a condition of licensing. The Energy and Public Debt pillars must be designed together on North Sea transition revenue. |
| Defence | Offshore infrastructure (wind farms, cable routes, pipelines) is increasingly a target for state-sponsored disruption. Energy security and defence need coordinated policy on protecting critical national infrastructure at sea. This is a direct and growing dependency. |
| Criminal Justice | Energy poverty in deprived communities is one of the social conditions the Criminal Justice pillar identifies as underlying causes of offending. This is not a direct causal link but a shared background: poverty, insecure housing and cold homes compound each other. |
7. Proposals for Change
These are the evidence-based proposals of this pillar, put forward for public discussion and challenge. Energy policy involves real trade-offs and disputed timescales. The Generational Reset invites challenge, more evidence and better arguments.
Electricity Market
-
Reform the wholesale electricity market so consumer prices no longer follow marginal gas prices, with a transition timetable that protects existing investment contracts.
-
Extend Contracts for Difference to older generation, gradually insulating more of the grid from swings in gas prices.
-
P2 Require all new EVs from 2027 to be ready for vehicle-to-grid, with standard communication protocols and smart tariff infrastructure.
North Sea
-
Maximise revenue from existing fields under strict fiscal discipline: no additional public co-investment, and no additional tax relief beyond proven commercial necessity.
-
Require decommissioning security in cash or near-cash, held in an independent trust, as a condition of every licence transfer to a company below investment grade, calculated on the full pre-tax cost.
-
Approve no new exploration licences that need public co-investment or additional tax relief to be commercially viable.
-
In each annual decommissioning cost update, publish the Exchequer's share of relief for each operator alongside the NSTA's table of operator performance. Each operator's decommissioning record is already public; what taxpayers pay for each operator is not.
-
P4 Fund a fully costed Just Transition plan from a ring-fenced levy on current production revenue, with specific retraining routes into offshore wind, CCS and hydrogen.
Grid and Storage
-
P5 Tackle the grid connection queue by setting binding connection timelines backed by regulatory consequences for Ofgem.
-
P6 Invest in enough long-duration storage to cover several days of low wind and low sun without gas backup.
-
P6 Reform the capacity market to pay for firm backup power at its real long-run cost, making the economics of storage and demand flexibility fully visible to investors.
Lobbying and Transparency
-
Require publication within 30 days of all ministerial meetings with energy industry representatives, all lobbying contacts and all material financial interests, as an explicit requirement linking this pillar to the Public Office Covenant.
-
Bar former energy ministers and senior energy civil servants from taking roles in fossil fuel companies for at least five years after leaving office.
The barriers here are political, not technical: markets built for the old world, planning systems too slow for what is needed, and a lobbying machine that has delayed action for three decades. Better technology alone won't fix that. Better democracy will.
Sources: DESNZ / Arup, Electricity Generation Costs 2025 | UK Government Revenues from UK Oil and Gas Production, September 2025 | National Grid ESO, Future Energy Scenarios 2024 | HMRC, Estimates of the Remaining Exchequer Cost of Decommissioning, February 2026 | NSTA, UKCS Decommissioning Cost and Performance Update 2025 | House of Commons Library, Taxation of North Sea Oil and Gas, 2025
The Generational Reset is a non-partisan, public-interest project. Not affiliated with any political party. | generationalreset.org
The Generational Reset | S4_01: Energy | For public discussion. Not affiliated with any political party. | generationalreset.org