THE GENERATIONAL RESET
Section Three: The Wider Conversation. The big choices Britain faces about what kind of economy it wants to be, and what it would take to get there.
This document sits in Section Three, The Wider Conversation, rather than Section One, because the economy pillar is less an account of how the current budget is spent than an argument about what Britain's economy is organised to do, and what would have to change for it to do something different. It is more contested, more forward-looking and more fundamental than the spending analysis in Section One. It is also the pillar on which every other pillar's long-term viability depends.
Executive Summary
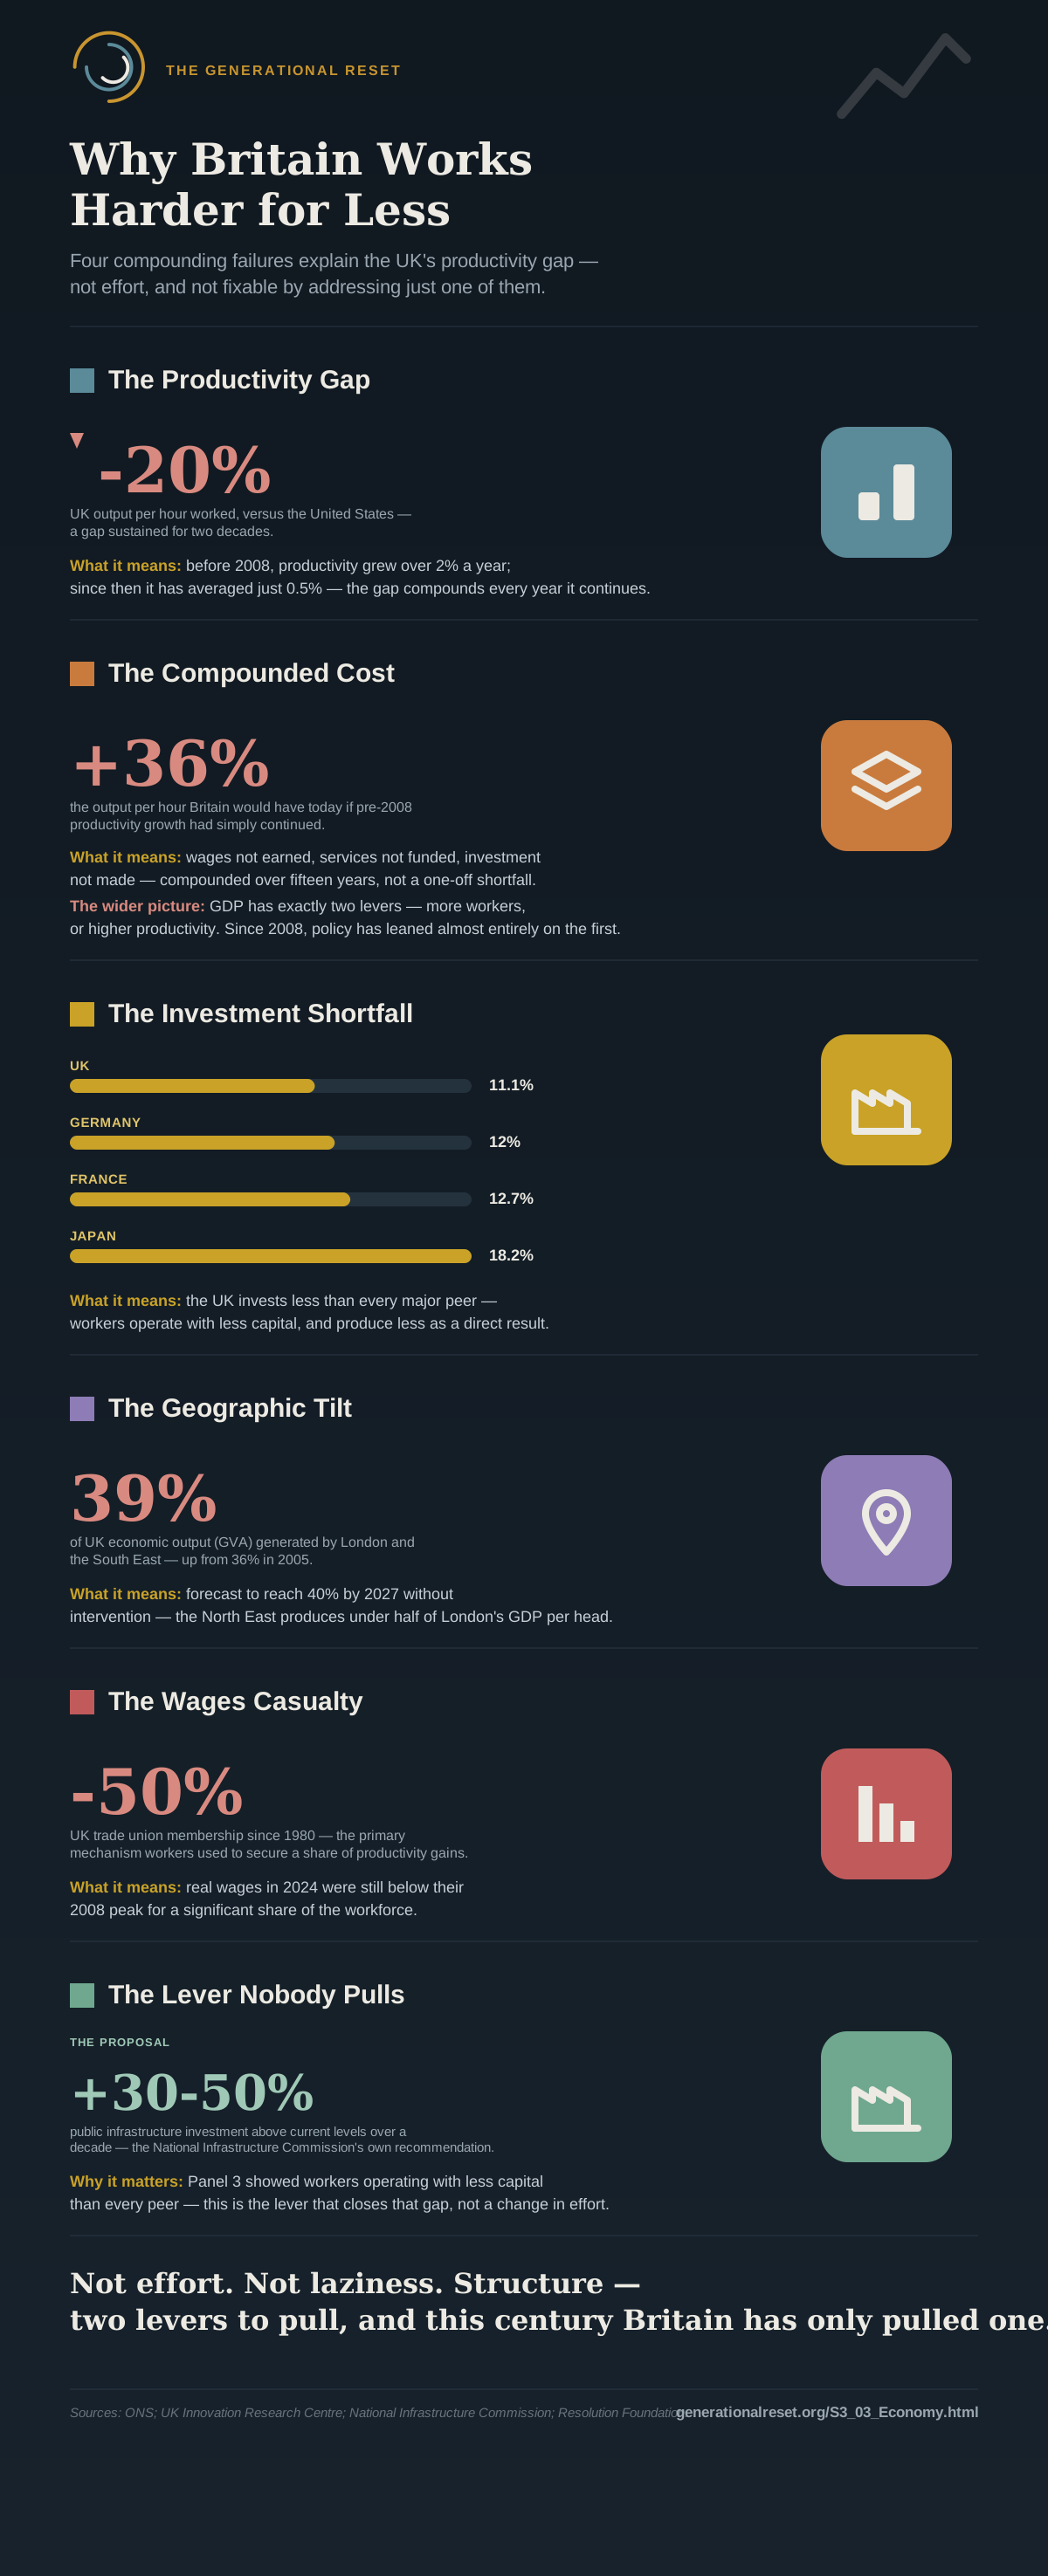
The UK has a productivity problem. Output per hour worked is roughly 20% below the United States and trails France, Germany and the Netherlands by similar margins. Before 2008, productivity grew at over 2% a year. Since then it has averaged 0.5%. The ONS estimated in 2018 that output per hour would have been about 21% higher had the pre-2008 trend continued.1 Growth has stayed weak since, so on the same method the gap is now about a third. That gap is wages not earned, public services not funded and investment not made, compounded over fifteen years.
This pillar makes five arguments. First, the productivity failure has four causes that reinforce each other: chronic underinvestment, a financial system geared to short-term returns, a long tail of low-productivity firms serving low-income local markets, and extreme regional concentration. Second, the comparison with Norway, which took comparable North Sea revenues and now holds a sovereign wealth fund of over $2.2 trillion (around £1.7 trillion) while the UK has nothing, is the clearest illustration of the choice between an economy run for long-term shared prosperity and one run for short-term returns. Third, the gap between regions, with London and the South East producing 39% of national output and rising, is not inevitable; it follows from policy choices that can be changed. Fourth, wages, work and the decline of collective bargaining are where all these failures land on real people. Fifth, the reforms needed (patient capital institutions, regional investment mandates, a wages compact) are not new. They are the UK's version of what comparable economies have built and kept for decades.
The economy pillar underpins every other pillar in the Generational Reset. The productivity gap, the regional divide, the wages crisis and the failure of ownership are not economic problems sitting alongside social ones. They are how social problems are created, sustained and passed down the generations.
Key Proposals
Route Crown Estate offshore wind lease revenue into the Sovereign Wealth Mechanism. Not a separate British Wealth Fund — the same Sovereign Wealth Mechanism already proposed in the Public Debt pillar, joining as a third funding stream alongside depleting-asset revenue and inheritance tax receipts. Finite national assets converted into permanent financial assets, not consumed in the present.
Reform pension fund regulation to require minimum UK productive investment. Statutory allocations to infrastructure, housing, and early-stage technology — with statutory teeth, not voluntary Mansion House commitments.
Introduce a National Infrastructure Mandate. Infrastructure spending per head converging across regions over fifteen years, with legally binding regional floors and independent audit of Treasury allocation decisions.
Launch a Clean Energy Industrial Strategy. Capturing the manufacturing value of UK offshore wind by conditioning contracts on UK-manufactured content and building supply chain skills in coastal communities.
Create a Sectoral Fair Pay Agreement system. Minimum terms by sector negotiated between employer associations and trade unions, with statutory backstop authority for the Low Pay Commission where negotiation fails.
Embed the capital-versus-current spending distinction in primary legislation. OBR-certified economic return as the test, alongside committing to infrastructure investment 30–50% above current levels over a decade.
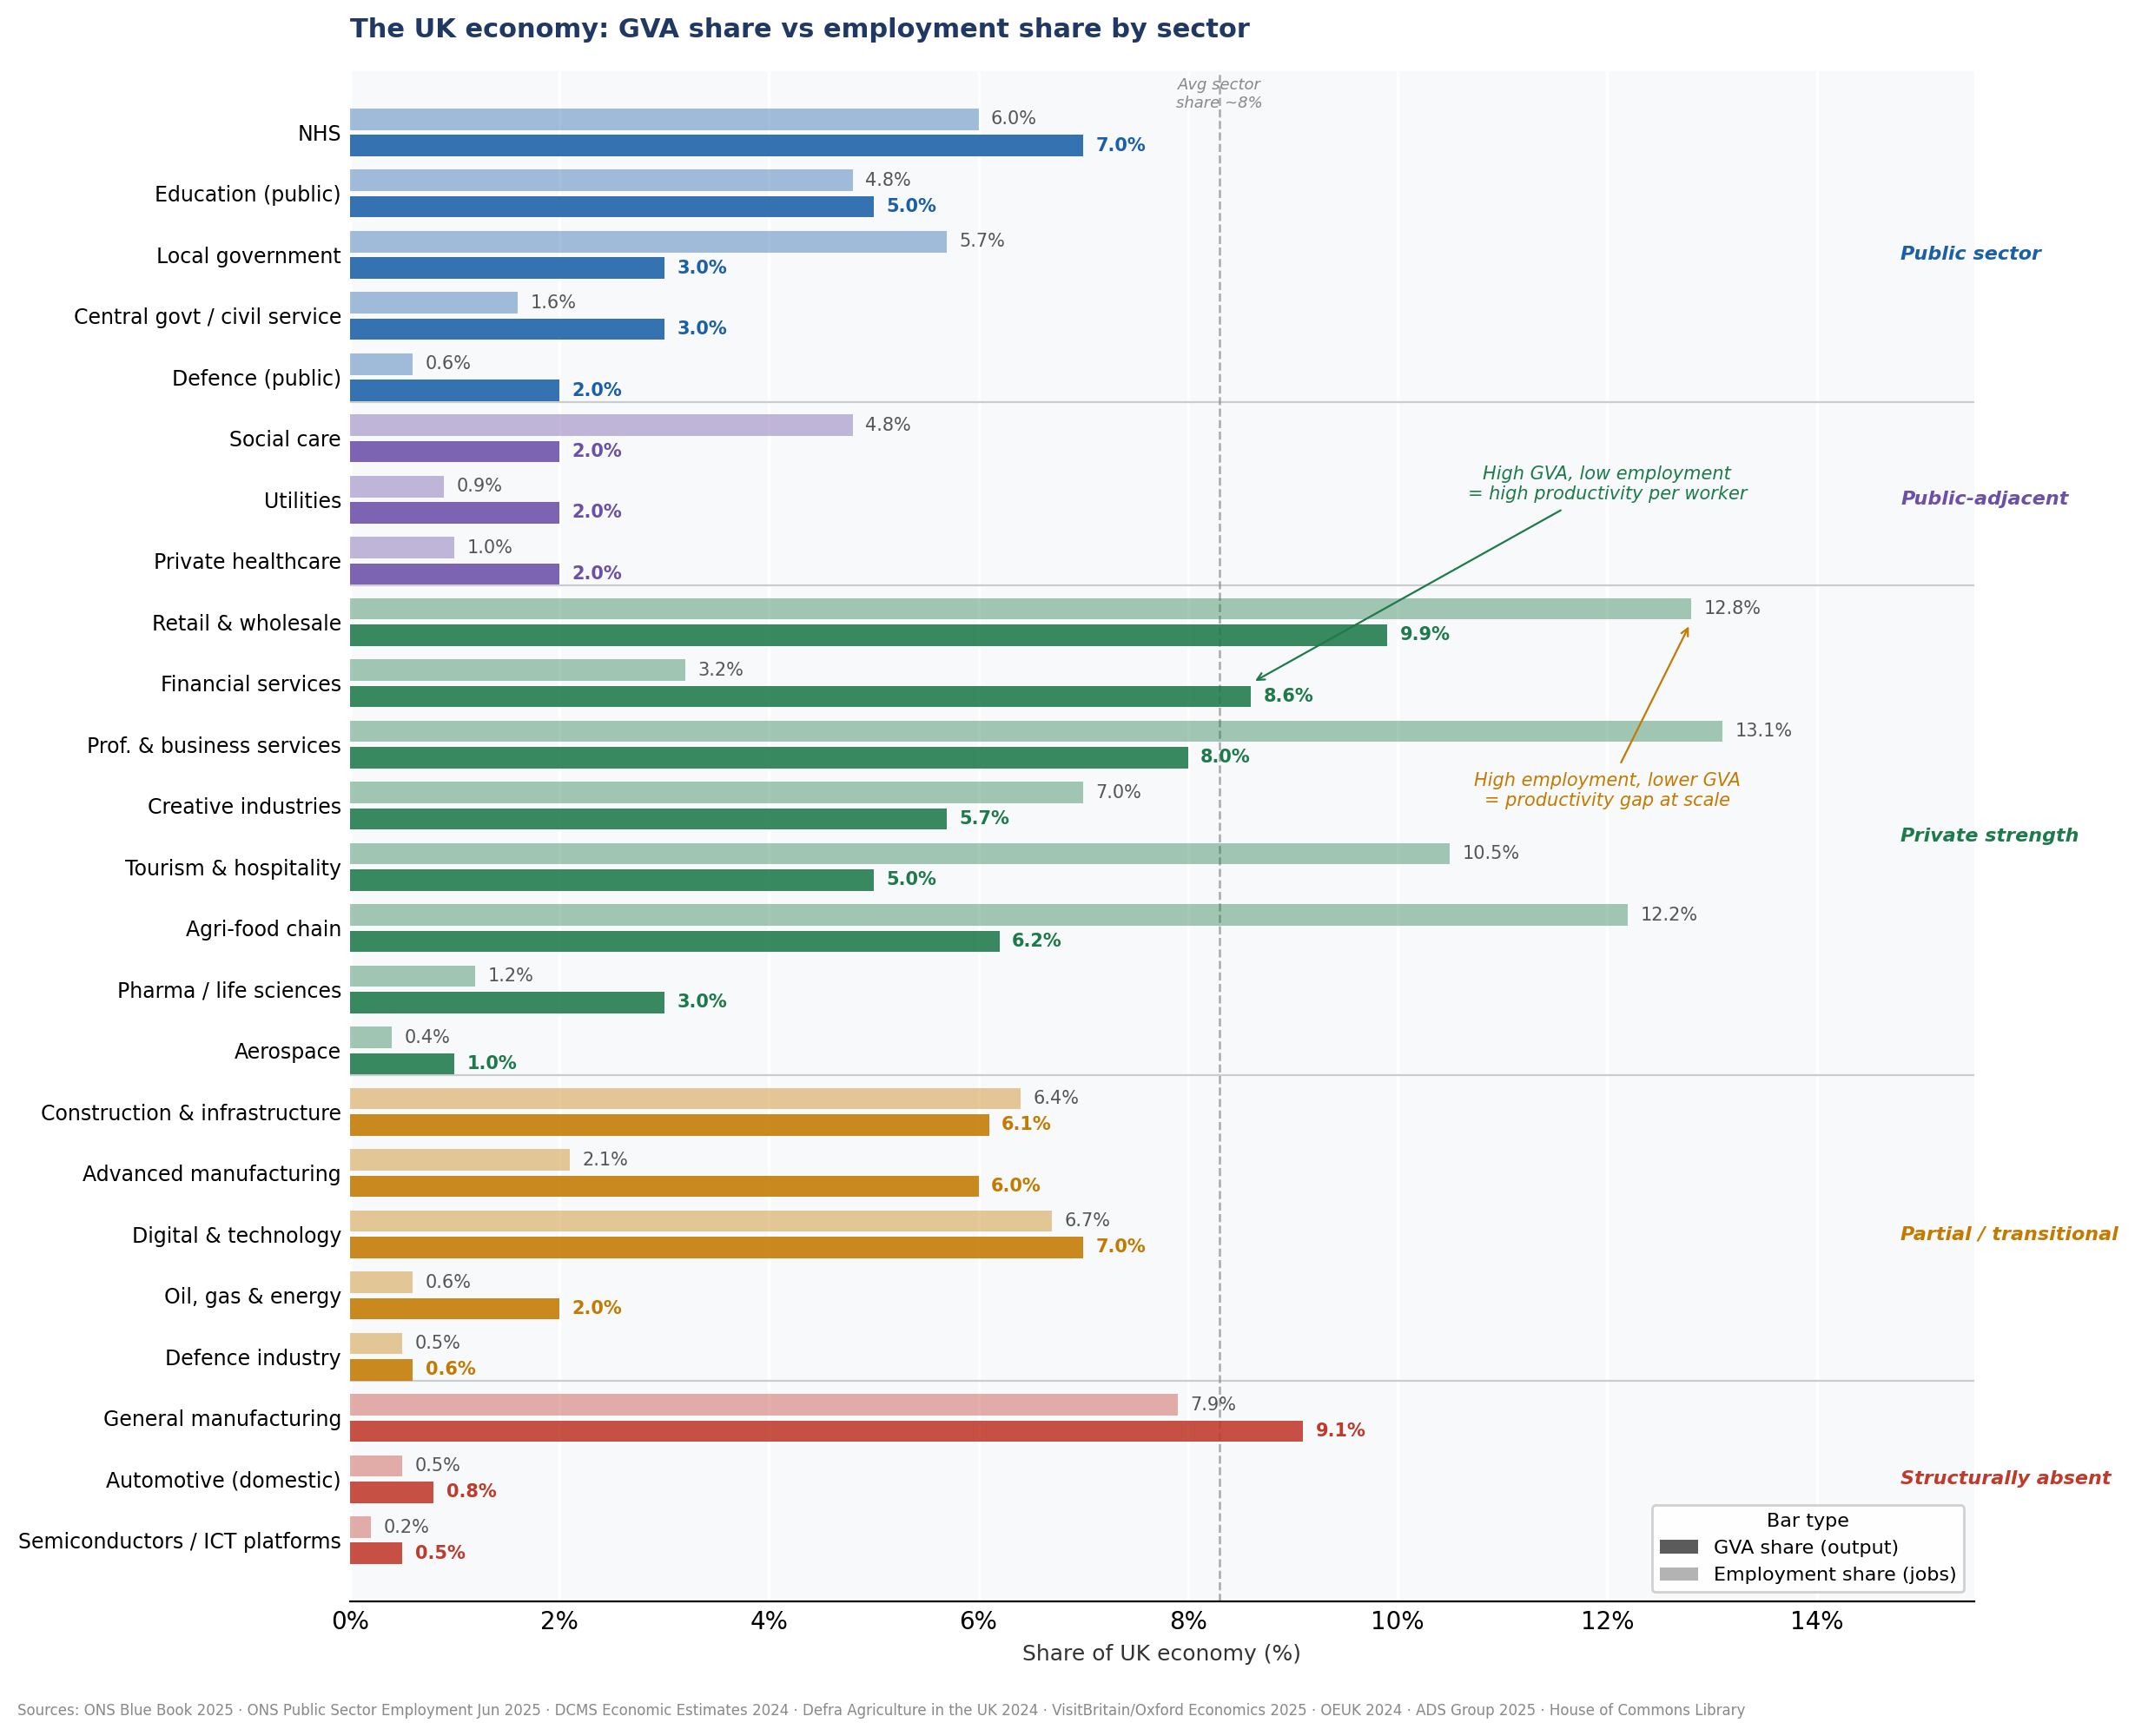
How to read this chart: the darker bar is each sector's share of the UK's total economic output (GVA); the lighter bar is its share of jobs. Where the darker bar is bigger, the sector produces more value than its headcount alone would suggest, so it is high-productivity. Where the lighter bar is bigger, more people work in it than its output alone would suggest.
1. The Diagnosis: Four Failures That Feed Each Other
The UK's productivity failure is not one problem with one cause. It is four failures, each of which makes the others worse.
1.1 Chronic Underinvestment
UK companies invest 11.1% of GDP, behind Japan at 18.2%, France at 12.7% and Germany at 12%.2 UK workers have about a third less capital per hour worked than workers in the United States, Germany, France and the Netherlands.3 In manufacturing the gap is 47%. A country that does not equip its workers cannot expect them to outperform countries that do. This is arithmetic, not a mystery, and the consequences run through every sector: hospitals in crumbling buildings, schools with outdated equipment, businesses running technology two generations behind their competitors.
1.2 Financialisation
The UK's financial sector is the second largest in the world. It is also, in important ways, cut off from the productive economy it is supposed to serve. Private equity makes its returns mainly by restructuring ownership, loading companies with debt, charging fees and selling at a multiple, not by making companies more productive. British pension funds hold huge pools of long-term capital, which in Germany, France and Norway go into infrastructure and industry, but they were steadily pushed toward liquid, lower-return assets. The result is a vicious circle: underinvestment produces low productivity, low productivity produces weak returns, and weak returns undermine the case for investment.
1.3 The Long Tail of Low-Productivity Firms
The UK has a long tail of low-productivity businesses that drags down the average. Mostly they are not badly managed. They serve local markets where people have too little money to support higher-value activity. Local service firms such as restaurants, shops and hairdressers make up 94% of the least productive third of businesses.4 Their problem is weak wages and demand, and it follows directly from the gap between regions.
1.4 Regional Concentration
London and the South East produce 39% of UK GVA, up from 36% in 2005 and forecast to reach 40% by 2027 without intervention.5 GDP per head in the North East is less than half London's. London alone now accounts for about a quarter of UK business R&D (£13.3 billion of £55.6 billion in 2024), and its spending rose 23% in cash terms between 2022 and 2024.6 These are not separate problems; they are four views of one. The forces that concentrate advantage in London reinforce themselves unless there is deliberate investment elsewhere.
UK output per hour has been roughly 20% below the United States for two decades. UK business investment is 11.1% of GDP, near the bottom of the G7, against Germany's 12%, France's 12.7% and Japan's 18.2%.2 London and the South East produce 39% of national GVA, up from 36% in 2005.5 Local service businesses make up 94% of the least productive third of firms. Trade union membership has fallen from over half of employees around 1980 to 22.4% in 2025.7
Each of these facts could be read as a separate problem with its own fix. This project's own connecting argument, which no single source states, is that they reinforce each other in a cycle. Underinvestment weakens returns, which weakens the case for more investment. Regional concentration drains purchasing power from local markets, which limits what local firms can charge and pay: the long tail described above. With collective bargaining weakened, whatever productivity gains do happen go mostly to capital rather than wages, weakening local demand further. A policy that raises investment without tackling regional demand, or raises regional infrastructure spending without restoring workers' bargaining power, treats one part of a self-reinforcing loop as if it were the whole.
The causation above fits several responses, not only this pillar's comprehensive one. One is to tackle underinvestment alone through patient capital reform, expecting more capital per worker to lift wages and regional output in time. Another is to tackle regional concentration alone through infrastructure investment, expecting spread-out opportunity to pull investment and wages with it. A third is to restore collective bargaining alone, expecting wage-led growth to force productivity-raising investment. The fourth, which this pillar proposes, is to treat all four as one interlocking problem that needs action on every front at once.
Choosing comprehensive reform over a single lever is a judgement about risk and sequencing that the evidence alone does not settle. It accepts a bigger, harder-to-sell programme now, rather than a politically easier single reform that this pillar's own causation argument predicts would fall short. A reader who thinks one credible lever done well is more achievable than a four-part programme done partly is not wrong on the evidence. They are weighing the same interdependence against a different appetite for political risk.
The six-proposal package below (patient capital institutions, pension fund reform, a National Infrastructure Mandate, a Clean Energy Industrial Strategy, a Sectoral Fair Pay Agreement system, and capital-spending discipline in law) tackles underinvestment, regional concentration and weakened bargaining power together, not as separate initiatives. The falsification test below sets out what would show the diagnosis itself is wrong, not just that one proposal underperforms.
2. What Britain Has: The Steel Man
2.1 Financial Services: World-Class, but Pointed the Wrong Way
London is the world's second-largest financial centre. Financial services contribute £209 billion in GVA, 8.6% of the economy, and employ 1.1 million people at above-average wages.8 No other G7 economy gets as large a share of its output from financial services. This is a real, globally competitive strength. This pillar does not argue for shrinking the sector. It argues for pointing the financial system toward productive investment, which would strengthen the sector's long-run contribution rather than weaken it.
2.2 Pharmaceuticals: World-Class, but Dangerously Concentrated
AstraZeneca and GSK are world-class research companies. They are the UK's only two entries among the world's top 100 corporate R&D investors, at 14th and 33rd.9 The life sciences sector accounts for about 25% of all UK business R&D spending, and the COVID-19 vaccination programme showed what the sector and the NHS can do together.
The risk is severe: two companies account for 88% of the sector's R&D spending. If either restructures, moves its research to the United States or Switzerland, or hits a difficult period, the UK's one credible R&D strength largely disappears. A national industrial base cannot safely rest on the decisions of two corporate boards.
2.3 Creative Industries: Consistently Strong
The UK's creative industries contributed £145.8 billion in GVA in 2024 and grew about four times faster than the wider economy that year (4.6% against 1.0%). The UK is the world's third-largest exporter of creative services, behind Ireland and the United States.10 Music, film and television, games and advertising are areas of real, sustained, globally recognised excellence. The UK is the largest centre for film and high-end television production in Europe, attracting £4.8 billion of inward investment in 2024 alone.
The catch is where the benefits go. Over half of creative industry output is produced in London, so the sector is as geographically concentrated as financial services. And over half of the film and television investment comes from US streaming companies, not domestic industrial strategy, so part of the foundation is borrowed rather than owned.
2.4 Aerospace: Mid-Tier Strength, Spread Across the Regions
UK aerospace had a turnover of £41.5 billion in 2025, and the aerospace, defence, security and space sectors together exported £50 billion, 45% of what they sold.11 Rolls-Royce is a world-class aero-engine maker and BAE Systems a major defence contractor. Unusually for a UK industry, aerospace is both internationally competitive and spread around the country: its big employment centres in Bristol, Derby, Lancashire and on the Clyde anchor regional economies in a way financial services and the creative industries do not.
Even so, the UK is a strong mid-tier player, not a dominant one. Rolls-Royce ranks 227th among the world's corporate R&D investors, behind Airbus, Boeing, RTX, Lockheed Martin, Thales and Safran. The sector is a real asset, but it cannot by itself deliver the industrial renewal the UK's problems require.
3. The Norway Comparison
Norway found North Sea oil at about the same time as the UK. Both extracted broadly comparable revenues over roughly the same decades. Both are mid-sized northern European democracies with similar political cultures and stable institutions. The resource was essentially the same. What differed was the decision about what to do with the money.
In 1990 Norway set up what is now the Government Pension Fund Global, originally the Petroleum Fund, with a simple mandate: surplus petroleum revenue would be invested abroad and compound for future generations. In 2025 it held over $2.2 trillion (about £1.7 trillion), equal to 1.5% of every listed company in the world and roughly four times Norway's GDP. Its returns now exceed the oil and gas revenue paid into it, so it will keep growing after the North Sea runs dry. In effect, every Norwegian has about $390,000 of sovereign wealth working for them.12
The UK chose differently, and kept choosing differently for three decades. Between 1980 and 1990, Margaret Thatcher's governments received about £166 billion in North Sea tax revenue, in 2011 prices.13 They spent it: on the costs of industrial restructuring, on the unemployment bill that came with deindustrialisation, and on income tax cuts. The receipts were large and the moment was brief, and it passed without any institution being built to hold and grow the proceeds.
The counterfactual is easy to sketch, though the numbers are this project's own rough calculation. North Sea tax receipts since 1980 come to something like £480 billion in today's prices, most of it in the 1980s. Had 10% of them gone into a fund earning 3% a year after inflation, it would now be worth over £100 billion and yield about £3–4 billion a year. Had 20% gone in at a 5% real return, it would be worth over £400 billion and yield about £20 billion a year, roughly a tenth of today's NHS England budget, indefinitely, from money that instead paid for tax cuts that have since been partly reversed.
3.1 Financialisation: What the Economy Is Organised to Do
The Norway comparison shows one specific failure, and a broader one lies beneath it. Over the last forty years the UK economy has been steadily reorganised to generate returns for people who already hold financial and property assets, rather than productive output that spreads prosperity widely. This process, financialisation15, is not a conspiracy. It is the accumulated result of individually rational decisions, each made in response to short-term incentives, with no thought for what the economy would look like forty years on.
Private equity makes its returns mainly by restructuring ownership, loading companies with debt, charging fees and selling at a multiple. The business may or may not be better at the end; the financial return largely does not depend on it. British pension funds in theory hold the long-term capital that could fund the twenty-year infrastructure and industrial investment that anchors economies like Germany's. From the 1990s they were steadily pushed toward bonds and liquid financial assets, away from patient, illiquid investment in infrastructure and industry. So the UK has the long-term capital it needs sitting in pension funds, and a financial system that keeps it there instead of putting it to work. Canada's "Maple Eight" pension funds went the other way and became some of the world's most sophisticated long-term investors, because they were set up to invest in infrastructure and private equity rather than government bonds.
4. The Sectoral Picture: Where Britain Competes and Where It Is Absent
The UK's economic structure tells a more specific story than the aggregate figures. Across the main sectors there is a consistent pattern: strong positions in services that generate concentrated returns, partial positions in industries with real industrial depth, and near-absence from the sectors that will dominate the next fifty years. The chart above compares each major sector's share of output with its share of jobs. Where the output bar is well above the jobs bar, the sector is high-productivity, producing more value per worker. Where jobs exceed output, productivity is lower. The pattern tells the story of the UK economy more clearly than any summary statistic.
Figure 1: UK sectors by GVA share (output) and employment share. Darker bar = GVA, lighter bar = jobs. Source: ONS Blue Book 202516 and sector-specific sources.
4.1 Where the UK Leads
Financial services produce £209 billion in GVA and employ 1.1 million people, and London is the world's second-largest financial centre.8 The creative industries contribute about £146 billion a year, growing about four times faster than the wider economy in 2024, and the UK is the third-largest global exporter of creative services. Professional and business services employ 4.5 million people, joint largest private-sector employer with retail. Tourism and hospitality together make up around 5% of GDP and employ 3.6 million people. Aerospace, second in the world by turnover, exports 70% of its output. These are real strengths. What they share is geographic concentration: over half of creative output, and most financial and professional services activity, is in London and the South East.
4.2 Where the UK Is Absent
Software and platforms account for 24.9% of all private R&D investment worldwide, and US firms contribute 77% of that. The UK's highest-ranked ICT firm in the global rankings is BT, at 389th: a legacy telecoms network, not a technology innovator. The UK has no equivalent of SAP, Salesforce, Ericsson or any major software platform.
Semiconductors show a particular version of this absence. The UK has Arm, a world-class chip designer, but Arm licenses designs rather than making chips. The UK has a few specialist fabs for compound and power semiconductors but no capacity to make advanced chips. The Netherlands has ASML, which makes the lithography machines every chipmaker depends on, and Germany has Infineon and Zeiss. The UK's place in the semiconductor chain is to design a small slice and rely on others to make almost all of it.
Automotive is the most telling comparison with Germany. Germany's car industry alone accounts for 34.2% of all R&D investment by the top 800 EU-headquartered companies. The UK's highest-ranked automotive R&D investor is Aston Martin, at 553rd, a low-volume luxury brand. Jaguar Land Rover is Indian-owned; Mini and Rolls-Royce cars are German-owned. Some manufacturing capacity remains, but the R&D, and the decisions about where future products are developed, sit elsewhere. Manufacturing is now about 8% of UK GDP, against 18% in Germany and 19% in Japan.17 France, at under 10%, shows that deindustrialisation is not unique to Britain, but Germany shows it is not inevitable either. It was a policy choice, made repeatedly and rarely named as one.
4.3 Exposure to AI
The UK's economic model rests on services (finance, professional services, law, consulting, back-office operations), exactly the sectors most exposed to AI taking over cognitive work. The UK has a large workforce in knowledge jobs that AI is beginning to automate, and relatively little of the manufacturing, engineering or deep-tech base that could offer other routes.
Financial services, the UK's crown jewel, lead the G7 in adopting AI skills. This is cited as a strength. But a financial sector that leads in adopting AI is automating its own workforce faster than anyone else. The UK risks leading the world in eliminating its own best-paid jobs without an industrial base big enough to absorb the people displaced. Clean energy is the most pressing current opportunity. The UK has the world's second-largest offshore wind capacity but imports most of its turbines, blades and subsea cables. Whether the UK builds the manufacturing base to supply its own clean energy is being decided now, mostly by default.
5. The Wages and Work Problem
All of these failures land, in the end, on the people who work. The productivity gap means wages that do not reflect what workers could produce. The regional divide means much of the work available across the country cannot support a decent standard of living. Financialisation means the gains from growth go increasingly to people who own assets rather than people who work for wages.
Real wages in 2024 were still below their 2008 peak for a large share of the workforce. The decline of collective bargaining, with union membership falling from over half of employees around 1980 to about a fifth today7, removed the main way workers used to secure a share of productivity gains. The gig economy and zero-hours contracts have shifted risk from employers to workers, discouraging the long-term investment in skills and loyalty that high-productivity economies depend on.
Retail and hospitality show how the problem works. Retail and wholesale account for 9.9% of GVA and 12.8% of all jobs, the largest private-sector employer in the economy. In hospitality, 21.6% of workers are paid the minimum wage, the highest share of any sector. These sectors cannot raise productivity through better management alone, because the ceiling is set by the spending power of the local customers they serve. Low wages produce low productivity, and low productivity justifies low wages. The circle cannot be broken from inside the sector. It needs action across the whole economy: regional investment that raises local demand, higher wage floors that spread spending power, and public services that cut the cost of living for low-paid workers.
6. The Strongest Case Against Reform
'The Norwegian model worked because Norway is Norway'
Norway had the political institutions, the national consensus, and enough distance from a major continental market to make long-term decisions without being punished at once by capital flight or lost competitiveness. The UK is a large, open economy tightly bound into global financial markets, and the Liz Truss episode showed how fast markets can react. This argument deserves respect, but it does not settle the question. Germany's KfW, France's Caisse des Dépôts and Canada's Maple Eight pension funds all operate in open, market-integrated economies, and all direct long-term capital into productive investment. The UK's missing institutions are a policy choice, not fate.
'Productivity strategies have always failed. What makes this different?'
The UK has launched many productivity strategies since 2010, and none has substantially closed the gap. The Generational Reset's answer is that earlier attempts failed because of how their institutions were built, not because of their strategy. That claim is only credible if it names what failed. There are three precedents, each with a specific cause.
The Green Investment Bank was privatised in 2017 for £2.3bn. The government kept a "special share" meant to protect its green mission, but that share can only block a change to the bank's stated purpose; it cannot veto individual investments. The Public Accounts Committee called this "deeply regrettable". Under private ownership, only about 40% of the renamed Green Investment Group's support went to UK projects, with the rest going to the wider European market.18 A protected charter with no say over investments is not a real constraint.
The British Business Bank has never had capital anywhere near the scale of its most-cited comparator: £4.9bn in assets against KfW's €540.7bn, roughly a hundredth of the size.19 This is not simply a lack of political will that a braver Chancellor could fix. KfW is classified in the national accounts as a financial institution rather than part of government, so its borrowing does not count toward Germany's headline public debt, even though the state guarantees it. The German state can therefore capitalise it at scale without the cost appearing in the debt figures. The British Business Bank has no equivalent treatment: its capital shows up in UK public sector net debt, the number the OBR and the gilt market watch. Any UK plan for an institution "like KfW" has to either accept that visibility or explicitly design around it.
The UK Infrastructure Bank was launched in 2021 with £22bn to deploy. In about three years of independent operation it managed only £1bn across ten deals, which the Public Accounts Committee described as "conventional" (solar farms, broadband) rather than the riskier projects private capital avoids, which it existed to unlock. It also had no performance measure beyond a financial return target, so there was no way to define success other than not losing money.20 It was absorbed into the National Wealth Fund in October 2024, which deployed £3.6bn in its first year, a much faster pace. But Parliament's Treasury Committee has found it still cannot show convincingly that its money brings in investment that would not otherwise have happened, rather than replacing it.21 Faster deployment has not yet answered the question that sank its predecessor.
The reforms in this pillar have to answer all three lessons specifically. They need safeguards over individual investments, not just a protected purpose (the Green Investment Bank lesson). They need an explicit position on how patient capital is treated in the public debt figures, since KfW-scale capitalisation is an accounting choice as much as a political one (the British Business Bank lesson). And they need mandatory, independently audited reporting of additionality from the first day, not a target added after a decade of unanswered questions (the UK Infrastructure Bank and National Wealth Fund lesson).
'Deindustrialisation was necessary. The UK cannot rebuild a manufacturing base'
There is a serious case that the UK's deindustrialisation made economic sense. It is largely right about mass manufacturing, and largely wrong about the sectors that will matter over the next fifty years. Semiconductors, clean energy technology, advanced materials and aerospace systems will not move to low-wage economies. They will go wherever the right mix of skills, infrastructure and institutional support exists. The UK's absence from them is not inevitable.
Cross-Pillar Dependencies
| Pillar | Connection |
|---|---|
| Education | The skills mismatch data (41% of UK workers whose field of study does not match their job, against an OECD average of 38%) feeds directly into the productivity analysis here. The UK Skills Framework is a joint Education and Economy tool and must be designed and funded jointly. Restoring FE funding is both an education equity measure and an economic productivity measure. |
| NHS | Low wages and insecure work are major drivers of the health outcomes gap, the mental health crisis and preventable hospital admissions. The wages and work compact is also health policy. The NHS workforce crisis is partly a failure of wages and working conditions that the economy pillar's wage reforms are needed to fix. |
| Welfare | This pillar's analysis of regional divergence and wages describes the economic mechanism behind the child poverty figures in the Welfare pillar. The two-child limit, inadequate in-work benefits and zero-hours employment are welfare tools trying to manage economic outcomes that need Economic Renewal to fix at source. |
| Housing | The land value capture framework links directly to the Sovereign Wealth Mechanism that this pillar's Crown Estate offshore wind revenue now feeds. The NHC is the vehicle for capturing land value and reinvesting it in social infrastructure. The 95% inheritance tax on all wealth at death closes both routes by which housing wealth has been built up and passed down the generations. |
| Defence | The industrial base argument runs through both pillars. Procurement that favours domestic supply chains is industrial policy and regional economic policy at once. BAE Systems, Rolls-Royce and the shipyards are anchor employers around which high-wage regional economies are built. |
| Public Debt | Low GDP growth makes debt ratios worse even if the debt itself is flat. Growth is not an alternative to fiscal discipline but its most reliable partner. Interest rates running below the growth rate is the most powerful debt reducer available, and that needs the Economic Renewal this pillar proposes. This pillar's Crown Estate offshore wind revenue, previously proposed here as a standalone British Wealth Fund, now goes into Public Debt's Sovereign Wealth Mechanism as a third funding stream instead of duplicating it under another name. See Public Debt Reform 4. |
| Energy | The clean energy industrial strategy links directly to the Energy pillar. The North Sea's skilled energy workforce, whose oil and gas skills transfer to offshore wind and subsea work, is the human capital that bridges the transition. The economy pillar must make sure industrial strategy delivers the promised jobs and regional development. The National Wealth Fund's £599m co-investment in the Wylfa SMR programme (April 2026) is the NWF working as intended, as a catalytic co-investor. It is separate from the Sovereign Wealth Mechanism fed by this pillar's offshore wind revenue (Public Debt Reform 4), which compounds on the sovereign fund model with no withdrawal of capital for day-to-day spending. |
| Political Renewal | The UK's chronic underinvestment reflects a five-year political cycle that cannot sustain twenty-year economic strategies. PR and the longer horizons of coalition government are what make this pillar's patient capital argument workable. The reforms proposed here are more credible when the political system behind them rewards long-term thinking. |
| Public Office Covenant | The financialisation diagnosis, a political class with large financial interests in rising asset prices, is the economic background to the conflicts of interest the Covenant addresses. The Covenant's transparency rules are partly a precondition for this pillar's reforms being politically possible. |
| Criminal Justice | The regional deprivation described here, with insecure work and stagnant wages concentrated in particular places, is the economic mechanism that drives demand on the criminal justice system in the hardest-hit communities. Economic Renewal and justice reform have to happen together, not one after the other. |
8. Proposals for Change
These are the evidence-based proposals of this pillar, put forward for public discussion and challenge. They are choices about how the economy should be organised, not programme commitments. The Generational Reset invites challenge, more evidence and better arguments.
Patient Capital: Building the Institutions
-
P1 Route Crown Estate offshore wind lease revenue into the Sovereign Wealth Mechanism (Public Debt Reform 4) as a third funding stream, rather than setting up a separate British Wealth Fund with its own governance. The money would not be available for day-to-day spending, and withdrawing capital would need cross-party support. This puts into practice the principle that finite national assets should become permanent financial assets, not be used up now, through one institution instead of two.
-
Recapitalise the British Business Bank and the National Wealth Fund (which absorbed the UK Infrastructure Bank in October 2024) at a scale comparable to KfW, with an explicit government position on keeping that capital outside public sector net debt where the investment is backed by assets, rather than accepting a fraction of KfW's scale as fiscally unavoidable. They would make long-term, below-market loans to strategic industries and provide patient debt capital that commercial banks will not. Independently audited additionality reporting should be required from the start, not added after a decade of unanswered questions.
-
P2 Reform pension fund regulation to require minimum allocations of defined benefit and defined contribution assets to productive UK investment (infrastructure, housing and early-stage technology), enforced in law rather than left to voluntary Mansion House commitments.
Regional Investment
-
P3 A National Infrastructure Mandate requiring infrastructure spending per head to converge across regions over fifteen years, with legally binding regional minimums and independent audit of the Treasury's capital allocation decisions.
-
Make the UK Skills Framework proposed in the Education pillar a regional economic tool, with each combined authority keeping a live register of skills needs matched against local FE and apprenticeship provision.
-
P4 A Clean Energy Industrial Strategy that captures the manufacturing value of the UK's offshore wind capacity by making contracts conditional on UK-made content, providing capital to develop supply chains, and building skills in the coastal communities next to offshore fields.
Wages and Work
-
P5 A Sectoral Fair Pay Agreement system that goes beyond individual employment contracts to set minimum terms by sector, negotiated between employer associations and trade unions, with the Low Pay Commission empowered to set binding sector minimums where negotiation fails.
-
A simpler two-category worker status (employee or self-employed), with an independent classification tribunal and the burden of proof on the employer, ending the use of the current three-category system to deny employment rights.
-
Restore collective bargaining coverage toward the levels of comparable European economies over twenty years, by making it easier in law rather than compulsory.
Government Capital Spending
-
P6 Write the distinction between capital investment and day-to-day spending into primary legislation. Borrowing for productive investment that pays future returns is different in kind from borrowing to fund current consumption. The distinction must be enforced, not just stated, with OBR certification of the expected economic return as the test.
-
P6 Commit to raising public infrastructure investment to the levels recommended by the former National Infrastructure Commission, 30–50% above current levels over a decade, with regional fairness built into how capital is allocated.
The economy pillar does not stand alone. The productivity gap, the regional divide, the wages crisis and the failure of ownership are how social problems are created, sustained and passed down the generations, not economic problems that merely sit alongside them. Getting the economy right is the same argument as the rest of this project, seen from a different angle, not a separate precondition for it.
The Generational Reset is a non-partisan, public-interest project. It is not affiliated with any political party, does not accept corporate funding, and publishes all its work under open licence for public discussion and adaptation.
For public discussion. Not affiliated with any political party. | generationalreset.org
The Generational Reset | S3_03: The Economy | For public discussion. Not affiliated with any political party. | generationalreset.org