Executive Summary
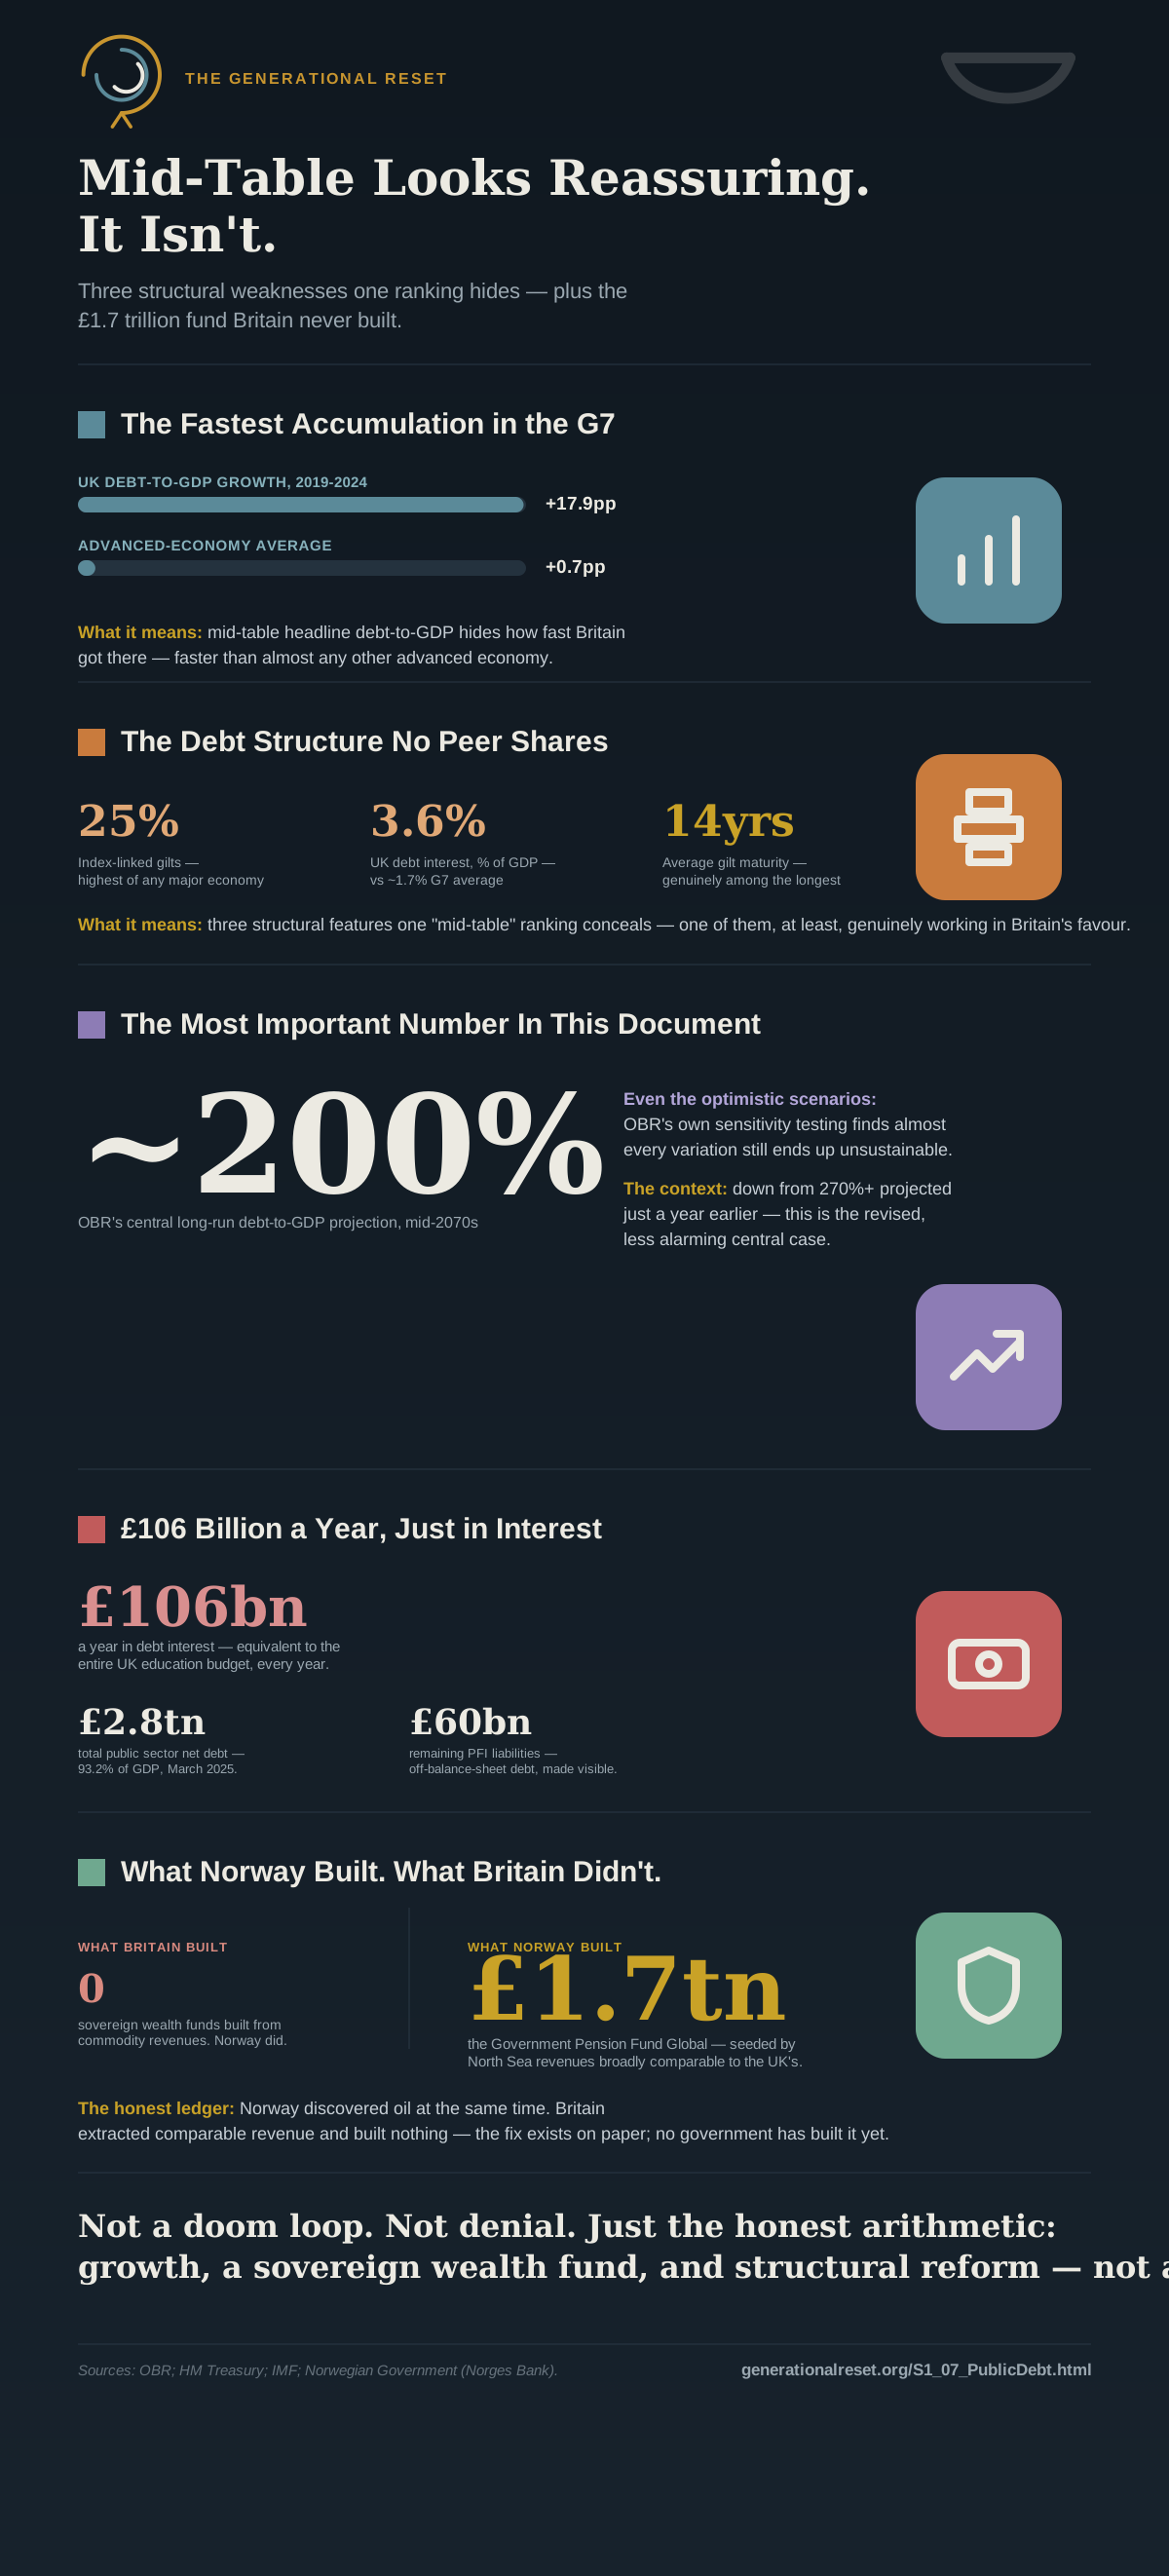
UK public debt stands at about £2.9 trillion, 93.8% of GDP at the end of March 2026. Debt interest reached £106 billion in 2024-25, close to the entire £119 billion education budget, and £109 billion in 2025-26.1 The OBR's October 2026 forecast has it rising to £160 billion, 4.2% of GDP, by 2031-32, above the previous highs of the 1960s and 1980s.2 Without reform, the OBR's long-run modelling puts central-case debt at around 300% of GDP by the mid-2070s, and its scenario testing finds that "almost all" plausible variations on that central case, including much more optimistic ones, still put the public finances "at some point" on an unsustainable path.3
This pillar makes five arguments. First, the UK's debt problem is worse than its headline G7 ranking suggests, because of how fast debt has built up, the unusually large share of inflation-linked debt, the cost of borrowing, and a persistent deficit on day-to-day spending that means the UK borrows even for current costs. Second, the answer is not austerity: the record of 2010-2019 shows that cutting public services to hit debt targets creates long-run fiscal costs of its own. Third, economic growth is the most powerful way to reduce debt and must go alongside fiscal consolidation. Fourth, a Sovereign Wealth Mechanism, funded by real revenue from depleting assets rather than by borrowing, is the change that would have prevented today's position and must now be built. Fifth, a Corporate Infrastructure Compact, linking what large businesses contribute to infrastructure investment, would tackle the market failure that has left UK public infrastructure chronically underfunded.
This pillar does not propose a target debt-to-GDP ratio by a particular date. The UK has had ten sets of fiscal rules since 1997, most of them changed or abandoned before they were met.4 What matters is the underlying changes that decide whether debt rises or falls over a generation.
Key Proposals
Embed the capital-versus-current spending distinction in primary legislation. With OBR certification of economic return criteria for all borrowing classified as capital investment.
Require a plain-English Generational Debt Statement at every Budget. Debt trajectory over 10, 25, and 50 years with OBR-mandated confidence intervals, and a requirement that elected officials acknowledge the intergenerational implications.
Reduce the index-linked share of the gilt stock toward European peer levels. About a quarter of gilts are linked to inflation; keep new index-linked issuance low, as the Debt Management Office now does, with a published target for the stock share over 15 years.
Establish a Sovereign Wealth Mechanism. Seeded by a rising share of revenues from depleting and time-limited assets, plus Crown Estate offshore wind lease revenue, governed independently on the Norges Bank model — with first-loss and return guarantees explicitly prohibited.See how Budget 2026 relates to this
Introduce a Corporate Infrastructure Levy. Tiered, on companies above £100 million annual turnover, ring-fenced to the Sovereign Wealth Mechanism with a legally mandated infrastructure investment mandate.
Make structural current-account balance a legally binding target by 2035. With automatic parliamentary review if structural borrowing exceeds 1% of GDP for three years, and an explicit, OBR-enforced prohibition on PFI-style mechanisms.
1. The Diagnosis
On headline debt-to-GDP, the UK sits mid-table among G7 economies.5 That comparison misleads, because three features make the UK's position much worse than the ranking suggests.
The first is the speed of the build-up. Between 2019 and 2024, UK gross debt rose by about 14.9 points of GDP6, against an average of 3.2 points across the EU7; among large European economies only France (14.4 points) rose by as much. The second is exposure to inflation. About 25% of UK gilts are index-linked, by far the highest share of any major economy.8 When inflation spiked in 2022-23, UK interest costs surged in a way French, German and US costs did not, and no other G7 economy has this weakness on anything like the same scale. The third is the persistent deficit on day-to-day spending. The UK borrows to pay current costs, not just to invest. Most comparable economies, whatever their total debt, are closer to balance on day-to-day spending.
2. The Norway Comparison: The Road Not Taken
Norway found North Sea oil at about the same time as the UK, and the UK extracted broadly comparable revenues over roughly the same period. Norway built the Government Pension Fund Global, worth about £1.7 trillion (around $2.2 trillion) at the end of 202510, by investing a set share of its oil revenue rather than spending it. The fund's returns help pay for Norwegian public spending. Norway does not run a deficit on day-to-day spending, and its debt interest is negligible relative to GDP.
The UK spent its North Sea revenues.11 It ran deficits on day-to-day spending throughout the years of peak extraction, built up debt, and now pays £106 billion a year in interest. The contrast is not incidental. It is the central story of UK fiscal policy over the past forty years, and the main reason this pillar proposes a Sovereign Wealth Mechanism as its central reform.
3. The Steel Man for Current Policy
'Borrowing to invest is not the same as borrowing to consume'
This argument is sound, and the Generational Reset accepts it. A government that borrows to build infrastructure, fund education or invest in the energy transition may generate future returns that more than cover the interest. The current government's fiscal rules, which separate the day-to-day budget from capital investment, are more defensible than blanket debt reduction. The Generational Reset's Reform 1 puts that distinction into primary legislation rather than leaving it to convention.
'Headline debt comparisons hide what matters: whether debt is sustainable'
True as far as it goes. The UK has one of the deepest and most liquid government bond markets in the world, and its gilts have among the longest maturities of any major economy. These are real advantages. But they do not change the exposure to inflation-linked debt, the speed of the build-up, or the OBR's long-run projection. The sustainability argument justifies going gradually, not doing nothing.
'Austerity has a record too'
The years 2010-2019 were a live experiment. The UK achieved modest cuts in the deficit relative to GDP at considerable cost: stagnant real wages, deteriorating public services, widening regional gaps, and arguably the political conditions that produced Brexit. The OBR itself has noted that repeated fiscal tightening was repeatedly undone by shocks. The lesson is not that debt doesn't matter. It is that how debt is reduced matters as much as the target, which is why this pillar does not propose austerity.
4. Rejected Instruments, and Why
4.1 Printing Money to Pay Debt
Modern Monetary Theory rightly points out that a government that issues its own currency cannot go bankrupt in that currency. The real constraint is the economy's productive capacity: creating money beyond it generates excess demand and prices rise. In the UK's case, an open economy heavily dependent on imported goods and energy, with inflation expectations still sensitive after 2022-23, paying for debt by creating money would trigger a falling pound and imported inflation, hitting hardest those least able to protect themselves. MMT's internal logic does not make it a safe operating choice for the UK.
4.2 Financial Repression
Deliberately holding interest rates below market levels, or letting inflation run above target, to erode the real value of debt has a long history. It transfers wealth from savers to the state. It is rejected here not as a concept but as a deliberate policy. The reforms in this pillar aim to get growth above interest rates through growth itself, without compromising the Bank of England's independence or taxing savers through inflation without Parliament's authority.
4.3 First-Loss Guarantees and PFI-Style Schemes
The Private Finance Initiative bought around £60 billion of public assets and committed the state to £199 billion of future charges for them, running into the 2040s, long after much of that capital has worn out.12 Any funding of a Sovereign Wealth Mechanism that involves the government underwriting private returns is PFI by another name. The Generational Reset explicitly bans first-loss guarantees and return guarantees as ways of funding the SWM. The PFI lesson must be written down, not left implied.
5. The Proposed Reforms
Reform 1: Separate Capital Investment from Day-to-Day Spending in Law
The current fiscal rules separate the day-to-day budget from capital spending, but the distinction has been applied inconsistently. The Generational Reset proposes writing it into primary legislation, with the OBR required to certify that any borrowing classed as capital investment meets published criteria for expected economic return. That stops the "investment" label being used to exempt politically convenient day-to-day spending from fiscal discipline, while making sure real long-term investment is not squeezed by the rules for current spending.
Write the distinction between capital investment and day-to-day spending into primary legislation. Require OBR certification of economic return criteria for all borrowing classed as capital investment. Allow no reclassification without an explicit vote in Parliament.
Reform 2: A Generational Debt Statement
Every Budget and fiscal event would include a plain-English Generational Debt Statement setting out: the current debt, its interest cost and its trajectory; projected debt per working-age person over 10, 25 and 50 years under current policy; the share of current spending being borrowed and passed to future taxpayers; and the OBR's long-run demographic projection and what it implies. This is a transparency requirement, not a limit on borrowing. The public cannot hold governments to account for fiscal decisions they cannot see.
Reform 3: Reduce Exposure to Inflation-Linked Gilts
The UK's reliance on index-linked gilts, about 25% of the stock, is a weakness no other major economy shares. New issuance has already moved most of the way: index-linked gilts were planned at about 6.5% of 2026-27 issuance, within the 5–10% typical of European peers.13 The problem now is the stock built up over earlier decades. The Generational Reset proposes that the Debt Management Office set an explicit, published target for the index-linked share of the stock over 15 years, achieved by keeping new index-linked issuance low as older linkers mature. It does not force early repayment of existing gilts. The 15-year horizon is deliberate: a gradual shift minimises market disruption and gives pension funds time to adjust how they hedge against inflation.
Reform 4: A Sovereign Wealth Mechanism
The UK receives revenue from North Sea licences, spectrum auctions, the bank levy and occasional windfall taxes, and spends it all as ordinary revenue in the year it arrives. The Generational Reset proposes that a set share of revenue from time-limited or depleting assets, starting at 20% and rising to 50% over a decade, be ring-fenced in a Sovereign Wealth Mechanism. It would not be a spending fund but a reserve for reducing debt and investing in the future. Norway's Government Pension Fund Global, built from North Sea revenue, is now worth about £1.7 trillion. The UK has no equivalent because the revenue was spent rather than saved.
The SWM must be funded from real revenue (commodity revenue, transfers of public assets, spectrum proceeds), not from borrowing. First-loss guarantees and return guarantees are explicitly banned as ways of funding it. Its governance follows the Norges Bank model: an independent board, a published investment mandate, annual accounts audited by the OBR, and a legally binding infrastructure mandate setting out which public goods the SWM must fund.
There would be one institution, not several. As the inheritance tax reform in Economic Renewal grows, its receipts will be lumpy from year to year: a few large estates settling in a given year can swing the total substantially, in a way that revenue from depleting assets such as the North Sea and spectrum mostly does not. Rather than set up a second fund to manage that volatility, a set share of inheritance tax receipts goes into this same SWM once the reform reaches Stage 2, under the same governance and no-guarantee rules. For that money, the SWM's job is to smooth out the swings, not to hold it as permanent capital the way it holds depleting-asset revenue. The two streams share one institution and one set of rules, not one purpose. The two-jar distinction in the Two-Jar Fiscal Framework working paper applies: depleting-asset revenue behaves like Jar Two capital, while smoothed inheritance tax receipts behave more like a buffer for volatile ordinary revenue, and the SWM's mandate should treat them accordingly instead of mixing them into one balance.
A third stream joins for a different reason. The Economy pillar previously proposed a separate "British Wealth Fund", funded by Crown Estate offshore wind lease revenue and built on the same principles as this SWM: independent governance, no access for day-to-day spending, and turning the return on a national asset into permanent capital. Rather than create a second, near-identical institution under another name, that revenue now goes into this SWM as a third stream. It is unlike the other two: not depleting like North Sea and spectrum revenue, and not lumpy like inheritance tax receipts, but a steady and probably growing royalty income as offshore wind expands. It sits on the permanent-capital side of the SWM's mandate with the depleting-asset stream, not on the smoothing side reserved for inheritance tax. That makes three streams, two purposes, one institution.
Establish a Sovereign Wealth Mechanism funded by a set share of revenue from depleting and time-limited assets, plus Crown Estate offshore wind lease revenue (previously proposed as a separate British Wealth Fund in the Economy pillar, now folded in as a third stream rather than run as a second, near-identical fund). It would be governed independently on the Norges Bank model, with a published, legally binding investment mandate audited by the OBR, and explicitly barred from using first-loss guarantees or government return guarantees to raise capital. From Stage 2 of the inheritance tax reform (see Economic Renewal §4), a set share of inheritance tax receipts also goes into the SWM, specifically to smooth the year-to-year swings in that revenue: one institution, three funding streams, two purposes and one set of governance rules, not three separate funds. This is the change that would have prevented today's fiscal position, and it must now be built, belatedly, to stop it happening again.
UK public debt stands at £2.9tn (93.8% of GDP at end-March 2026), with debt interest of £106bn in 2024-25, close to the entire £119bn education budget.1 Norway's Government Pension Fund Global, built from North Sea revenues broadly comparable to the UK's, is now worth about £1.7 trillion.10 The UK extracted comparable revenues over the same period and spent them as ordinary revenue rather than saving any share.11
Norway and the UK started from comparable resources and differed only in the institutions they built. This connecting argument is the project's own, built on the facts above; no single source states it. With nothing to ring-fence it, revenue from depleting assets was treated like any other year's tax receipts, available for whatever spending pressure was greatest at the time. The £106bn annual interest bill is presented here as the accumulated cost of that missing institution, not of a smaller or less valuable resource than Norway's.
The causation above fits responses well beyond a sovereign wealth mechanism, two of which this pillar names and rejects in §4: paying for debt by creating money, coherent on Modern Monetary Theory's own terms but rejected here as unsafe for an open, import-dependent economy with inflation expectations still sensitive after 2022-23; and financial repression, holding rates below market levels to erode debt's real value, rejected as a deliberate transfer from savers to the state. A third option, which this pillar does not formally reject but which continues by default unless something changes, is to keep treating revenue from depleting assets as ordinary annual receipts: the status quo that produced the current position.
Choosing a ring-fenced, independently governed SWM over creating money, financial repression, or continuing to spend depleting-asset revenue as ordinary receipts rests on a value judgement this pillar makes openly: tying future governments' hands, through independent governance and an explicit ban on guarantees, is worth the loss of short-term fiscal flexibility, because that same flexibility is what let North Sea revenue be spent the first time. A reader who trusts future governments to use that flexibility responsibly, or who thinks the inflation risk of creating money is overstated for the UK, is not wrong on the evidence. They are weighing the same facts against a different view of how much discretion the state should keep.
A Sovereign Wealth Mechanism funded by a rising share of revenue from depleting and time-limited assets (20% at first, rising to 50% over a decade), plus Crown Estate offshore wind lease revenue and, from Stage 2 of the inheritance tax reform, a stream of inheritance tax receipts to smooth their volatility; governed independently on the Norges Bank model with first-loss and return guarantees banned. The falsification test below sets out what would show the institutional protections are not holding.
Reform 4b: The Corporate Infrastructure Compact
Companies operating in the UK do not pay the full cost of the infrastructure they use. They benefit from publicly educated workers without bearing the full cost of that education. They use roads, power grids, digital networks and the NHS without paying for the demand they place on them. This is a market failure, and one reason UK public infrastructure has been chronically underfunded compared with its peers.
The Generational Reset proposes a tiered Corporate Infrastructure Levy on companies with turnover above £100 million, with the rate linked to how much each sector depends on infrastructure. Energy-intensive manufacturers, large logistics firms, data centres and financial services use infrastructure differently and should contribute accordingly. The levy, on top of corporation tax, goes straight into the SWM under a legally binding mandate to invest in infrastructure. The return to companies is not a cash rebate but a more productive place to do business.
Reform 5: End Persistent Borrowing for Day-to-Day Spending by 2035
The OBR's October 2026 forecast has the current budget moving into surplus in 2029-30, by £15 billion, and puts the chance of that happening at 56%.2 A surplus has been projected and missed again and again. The Generational Reset proposes making balance on the day-to-day budget, adjusted for the economic cycle, a legally binding target with automatic enforcement: if the OBR certifies that underlying borrowing for day-to-day spending will exceed 1% of GDP for three years running, a mandatory parliamentary review is triggered, requiring an explicit vote on any departure from the target. This is not austerity by default but accountability by design. Exemptions for certified national emergencies must be defined in law, not left to ministers' discretion, to prevent abuse.
6. What This Is Not
This pillar does not propose austerity. Cutting public services to hit an arbitrary debt number is not the reform proposed here. The record of 2010-2019 shows that austerity without deeper reform creates long-term fiscal costs of its own through underinvestment, lower productivity and fewer people in work. The Generational Reset targets the underlying causes: the reliance on inflation-linked debt, the lack of a sovereign wealth mechanism, the blurring of investment and consumption, the political invisibility of debt passed to future generations, and the failure of companies to contribute to the infrastructure their businesses depend on.
7. Counter-Arguments
'A Sovereign Wealth Mechanism is just borrowing to invest, with extra steps'
What matters is not whether the state is spending money (under both borrowing and the SWM, it is) but whether that spending becomes a permanent financial asset earning a return or is simply used up. The SWM is funded from real revenue: a rising share of income from depleting assets, Crown Estate offshore wind lease revenue, the Corporate Infrastructure Levy, and a share of inheritance tax receipts from the Economic Renewal pillar. None of that needs new debt, and first-loss and return guarantees are banned by design. Borrowing to invest adds a liability with no matching asset. The SWM adds an asset that can outlast the revenue that built it, which is exactly what Norway's £1.7 trillion fund is.
'Norway's fund worked because oil revenue was booming when it was built. The UK is proposing the same idea decades after its own oil boom ended, with little revenue left to fund it'
True of oil, and this pillar does not pretend otherwise: North Sea tax revenue is a fraction of its 2008 peak. But the SWM does not rely on oil and gas alone. It pools revenue from Crown Estate offshore wind leases, a new and growing income Norway did not have when it built its fund, with the Corporate Infrastructure Levy and a share of inheritance tax receipts from the transfer of wealth already under way. The UK missed its oil-era window. That is not the same as having missed every window since.
'A Corporate Infrastructure Levy on large companies will just be passed on to workers and consumers, like other business taxes'
This is a real economic risk, not one to wave away: taxes that formally fall on companies are routinely passed on to some degree through wages and prices. Three things set this proposal apart from an equivalent flat tax rise, though. It applies only above £100 million of turnover, concentrating any pass-through on the firms best able to absorb it rather than on smaller employers. It is ring-fenced for the infrastructure those same large employers depend on, rather than disappearing into general taxation. And unlike ordinary tax revenue, every pound becomes a permanent SWM asset rather than being spent once. Some pass-through is likely. Leaving the infrastructure gap unfunded has its own pass-through cost, in higher long-run borrowing costs and slower growth.
Cross-Pillar Dependencies
| Pillar | Connection |
|---|---|
| Political Renewal | The Generational Debt Statement, requiring politicians to acknowledge what each budget passes to future generations, needs a Parliament willing to bind itself. A binding target for day-to-day balance needs cross-party commitment, which proportional representation makes far more achievable than a system of alternating majority governments with opposing fiscal views. |
| Public Office Covenant | Elected officials approving budgets that pass debt to future generations should have to acknowledge it explicitly. The Covenant's transparency and accountability principles extend naturally to fiscal decisions through the Generational Debt Statement. |
| NHS | The £15.9 billion NHS maintenance backlog adds directly to the long-run debt path. The health costs of an ageing population are the largest single driver of the OBR's projection of debt reaching around 300% of GDP. Reform that shifts the NHS toward prevention and slows demand growth is essential to long-run fiscal sustainability, and the Corporate Infrastructure Compact explicitly funds health infrastructure. |
| Education | Productivity growth is the most lasting way to reduce debt over the long run. A better-educated workforce means higher tax revenue and lower welfare costs. The SWM's infrastructure mandate should include skills infrastructure as a main investment category. |
| Welfare | Welfare spending, especially the state pension triple lock, is a large and growing day-to-day cost. Reform 5's balance target cannot be met without explicit decisions in the Welfare pillar about the long-run path of pensions and benefits. The two pillars must be read together on the fiscal arithmetic. |
| Economic Renewal | From Stage 2 of the inheritance tax reform, a set share of inheritance tax receipts goes into this pillar's SWM alongside its depleting-asset revenue: one institution, two funding streams with two purposes (permanent capital from depleting assets; smoothing for inheritance tax receipts). It is a shared institution, not a shared purpose, and the SWM's mandate should account for the two streams separately while sharing governance. |
| Economy | Slow growth makes debt ratios worse even if the debt itself is flat. The Economy pillar should be read alongside this one: growth is not an alternative to fiscal discipline but its most reliable partner, and growth above the interest rate is the most powerful debt reducer available. The Economy pillar's previously separate British Wealth Fund proposal (Crown Estate offshore wind lease revenue) is now folded into this pillar's SWM as a third funding stream rather than run as a second, near-identical institution; see Reform 4 above. |
| Housing | Capturing land value is a revenue source directly relevant to the SWM. The 116-fold rise in value when farmland gets planning permission for housing is currently a private windfall. Directing part of it into the SWM is one of the largest fiscal reforms available that needs no new tax, only the redirection of value the public creates. |
| Energy | The SWM's main funding sources include commodity and windfall revenue. The tax regime for new North Sea licences should make a contribution to the SWM a condition of licensing, not an afterthought. The Energy and Public Debt pillars must be designed together on North Sea transition revenue. |
| Defence | Resilient digital and physical infrastructure funded by the SWM has value for national security too. The Corporate Infrastructure Compact's investment mandate should be coordinated with the Defence pillar's infrastructure needs. |
| Criminal Justice | Ministry of Justice day-to-day spending in 2025–26 is 14% below its 2007–08 level in real terms, a deeper cut than most departments faced (IFS). The knock-on costs of that underinvestment (welfare claims, NHS demand, lost productivity from reoffending) appear across several budget lines, and the Public Debt pillar's framework should make them explicit. |
9. Proposals for Change
These are the evidence-based proposals of this pillar, put forward for public discussion and challenge.
-
Write the distinction between capital investment and day-to-day spending into primary legislation, with OBR certification of economic return criteria for all borrowing classed as capital investment.
-
Require a plain-English Generational Debt Statement at every Budget and fiscal event, setting out the debt path over 10, 25 and 50 years with OBR-mandated confidence intervals, and require elected officials to acknowledge what it means for future generations.
-
Set an explicit, published Debt Management Office target for the index-linked share of the gilt stock over 15 years, keeping new index-linked issuance low (about 6.5% in 2026-27) as older linkers mature.
-
Establish a Sovereign Wealth Mechanism funded by a set share of revenue from depleting and time-limited assets, starting at 20% and rising to 50% over a decade, governed independently on the Norges Bank model, with first-loss and return guarantees banned as ways of raising capital.
-
Introduce a tiered Corporate Infrastructure Levy on companies with turnover above £100 million, ring-fenced to the SWM under a legally binding mandate to invest in skills, health infrastructure, the energy grid and digital connectivity.
-
Make balance on the day-to-day budget, adjusted for the economic cycle, a legally binding target by 2035, with an automatic parliamentary review if the OBR certifies underlying borrowing above 1% of GDP for three years running, and with exemptions for certified national emergencies defined in law, not left to ministers.
-
Publish an explicit ban on PFI-style mechanisms (first-loss guarantees and return guarantees) as tools of public investment, with the OBR required to flag any proposal that reproduces PFI economics under another name.
The UK's debt is the accumulated arithmetic of a series of individually defensible decisions, none made with an eye to what the public finances would look like forty years later. Norway made different choices with comparable resources and built a £1.7 trillion sovereign wealth fund. The UK paid £106 billion in interest last year. The lesson is simple. The reform is not.
The Generational Reset is a non-partisan, public-interest project. It is not affiliated with any political party, does not accept corporate funding, and publishes all its work under open licence for public discussion and adaptation.
All figures from the ONS, OBR and IMF (2025-26 fiscal year and the March 2026 Economic and Fiscal Outlook unless otherwise stated) | For public discussion. Not affiliated with any political party. | generationalreset.org
The Generational Reset | S1_07: Public Debt | For public discussion. Not affiliated with any political party. | generationalreset.org